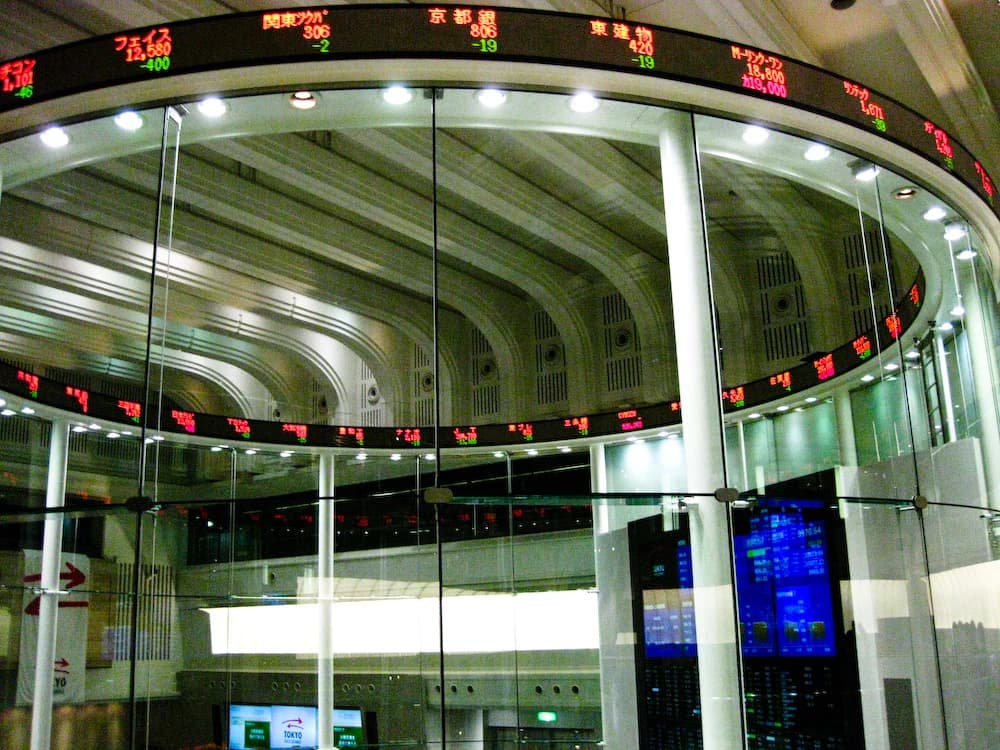
Chunghwa Telecom has approved an unsecured corporate bond issuance of up to NT$20 billion, a move that gives Taiwan’s largest carrier flexibility to refinance debt and fund capital spending without tying up assets as collateral.
Chunghwa Telecom Approves NT$20 Billion Bond Issue
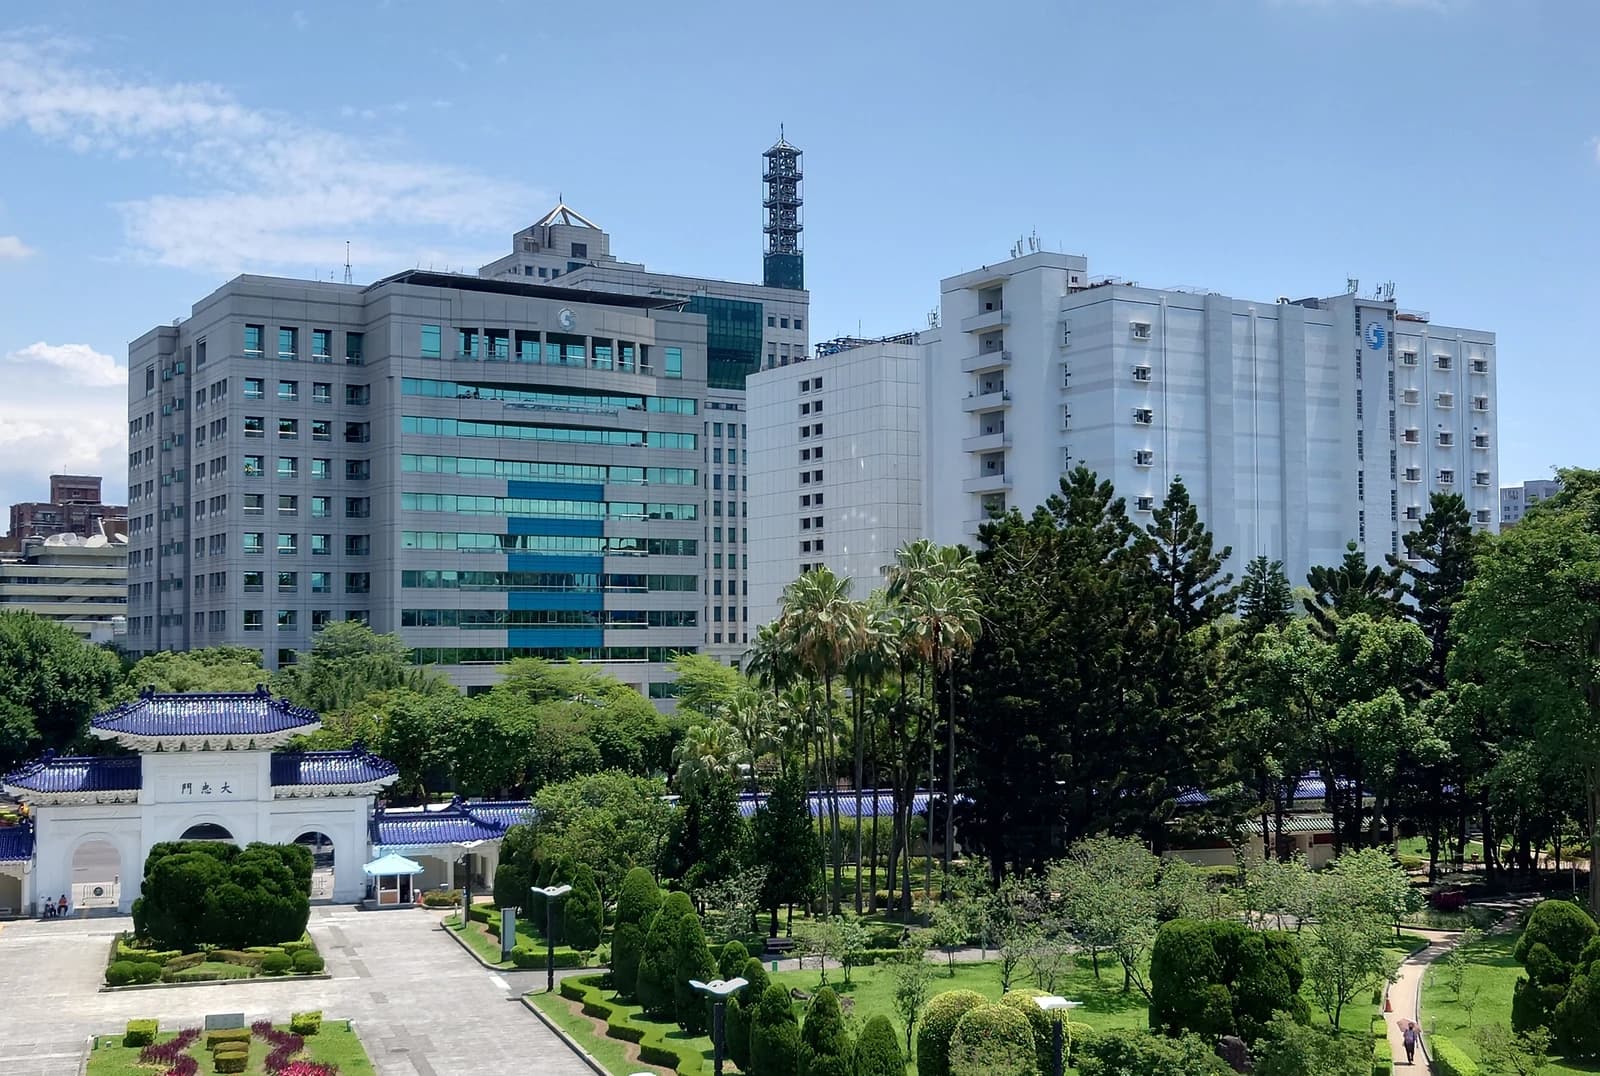
The decision matters because telecom operators are among the most capital-intensive listed companies, and bond financing remains one of the cheapest ways to support network upgrades, spectrum-related spending and working-capital needs. For investors, the structure is as important as the size: unsecured paper suggests Chunghwa can still access the market on the strength of its credit profile, rather than relying on asset-backed borrowing.
The company disclosed the board approval in a Nov. 6 filing, saying proceeds may be used for capital expenditures, debt repayment, working capital or other medium- to long-term business needs. In other words, the offering is likely to serve several balance-sheet functions at once, rather than finance a single acquisition or strategic pivot.
That breadth of use is consistent with how telecom groups manage cash flow cycles. Network investment is lumpy, while operating cash generation tends to be steady, so bond issuance often becomes a tool to smooth maturities and preserve financial flexibility. In a higher-rate environment, even large, defensive issuers have been leaning on debt markets to lock in longer-term funding before conditions shift again.
For Chunghwa, the move also comes with its shares already trading above both the 50-day and 200-day moving averages, a sign that the market has been rewarding the stock’s relative stability. The shares closed at NT$48.81 in the latest session, well above the 50-day average of NT$46.57 and the 200-day average of NT$43.10, though momentum indicators have eased from overbought levels after the stock’s recent run.
The bull case is that the bond sale reinforces balance-sheet discipline and gives management room to keep investing in broadband, 5G and other infrastructure without straining liquidity. The bear case is that if funding costs remain elevated, debt issuance could weigh on future margins and signal that capital intensity is rising faster than cash returns.
For income-focused investors, Chunghwa’s credit access remains a positive sign of financial resilience. For bond buyers, the issue should attract attention as a defensive telecom credit from a company with recurring cash generation. The key question now is pricing: if Chunghwa can place the notes at attractive spreads, it will confirm that demand for high-quality Asian corporate debt remains solid even as global rate expectations shift.
| Entity | Gains | Losses |
|---|---|---|
| Chunghwa Telecom | ▲Lower funding risk | ▼Higher interest expense |
| Bond investors | ▲Defensive telecom credit | ▼Yield compression if demand is strong |
| Equity holders | ▲Balance-sheet flexibility | ▼Potential dilution of returns from debt costs |
| Competing issuers | ▲Benchmark for market access | ▼Less room if spreads widen |