Upper Arlington’s $3.8 million sale led Columbus-area home transactions in July 2026, underscoring how the region’s luxury market continues to clear at prices that most buyers are shut out of even as broader housing conditions remain constrained.
Columbus luxury home sales led by Upper Arlington
The top 25 sales were dominated by affluent suburbs, with Upper Arlington, Bexley and New Albany accounting for most of the month’s largest deals. That concentration matters economically because the upper tier of the market is being supported by buyers with stronger balance sheets, limited financing sensitivity and a willingness to pay for scarcity in established school districts and amenity-rich neighborhoods. In a market where affordability has been squeezed by higher borrowing costs and elevated home values, those neighborhoods are still attracting cash-rich or high-income households, keeping the premium end of the market active even when transaction volume elsewhere softens.
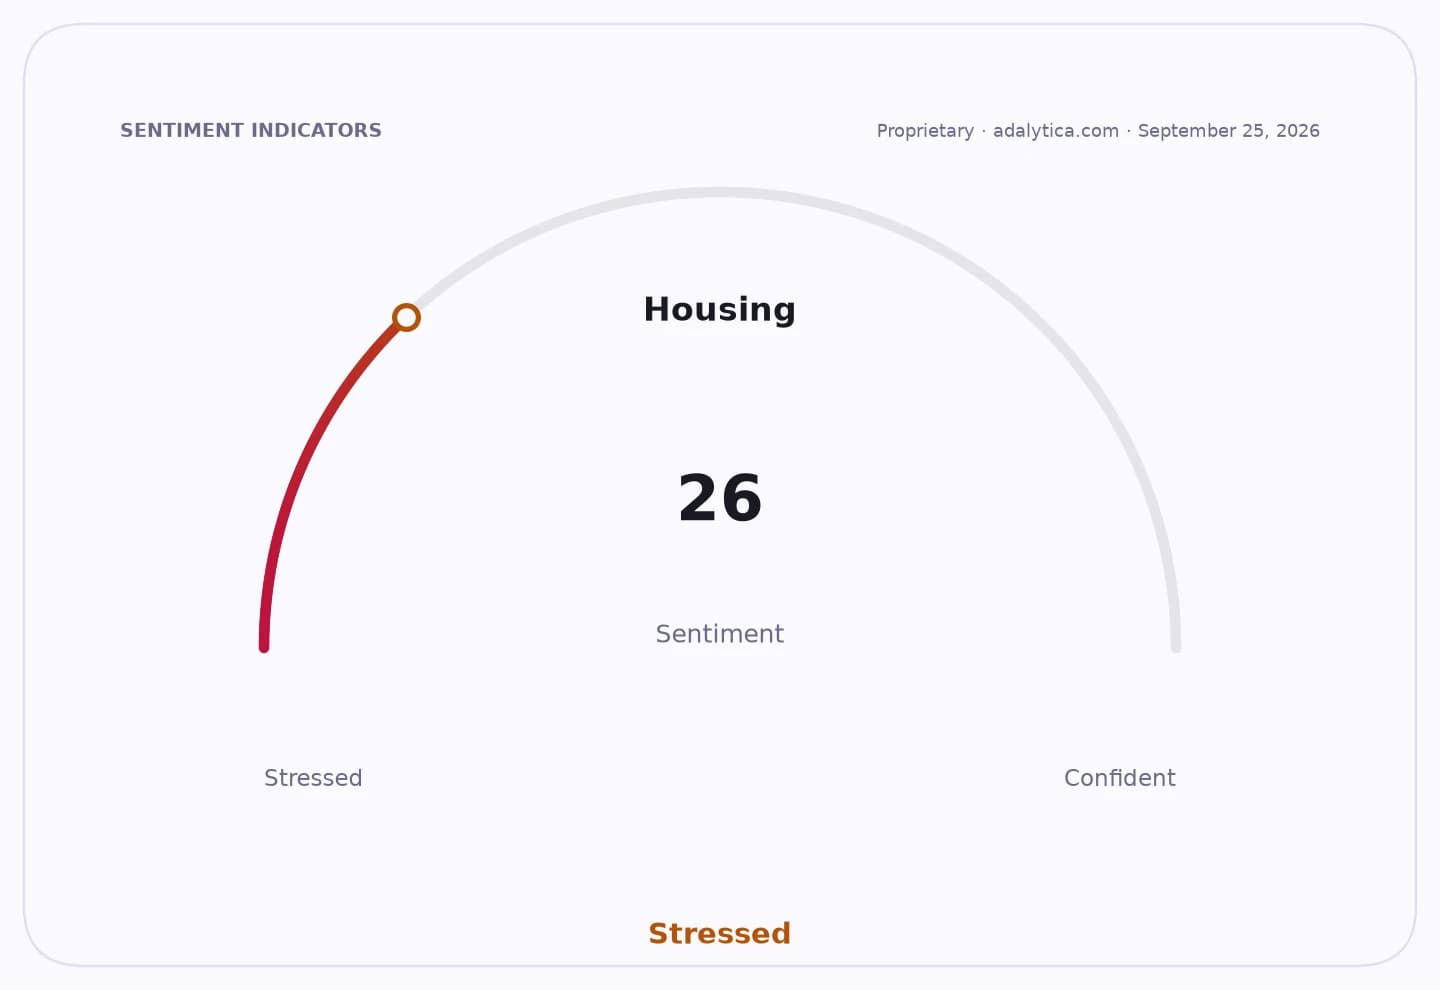
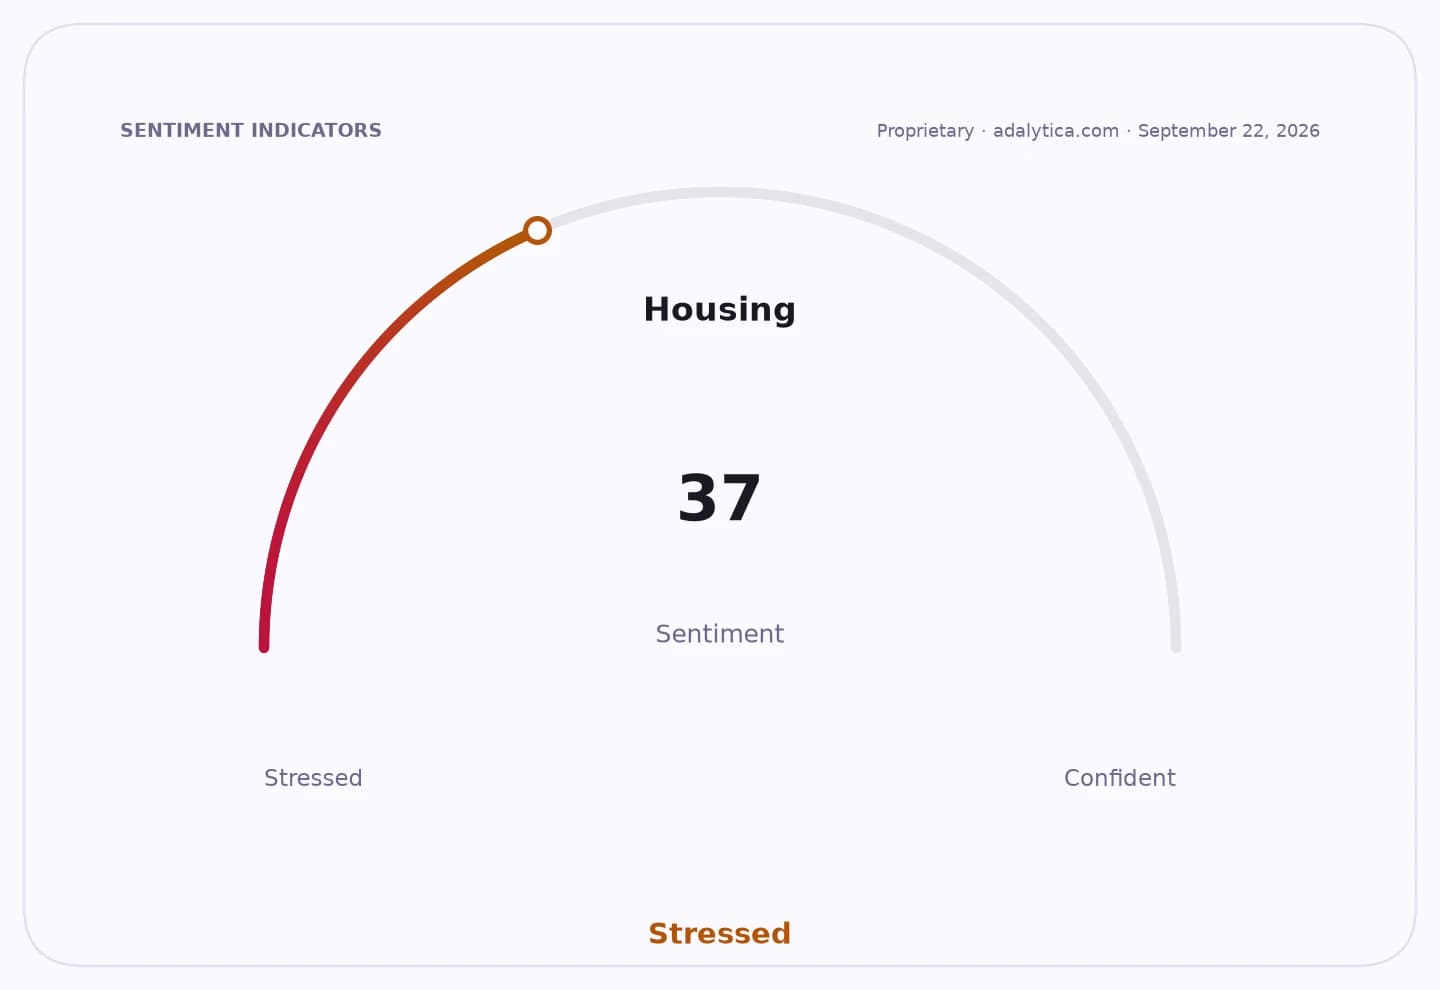
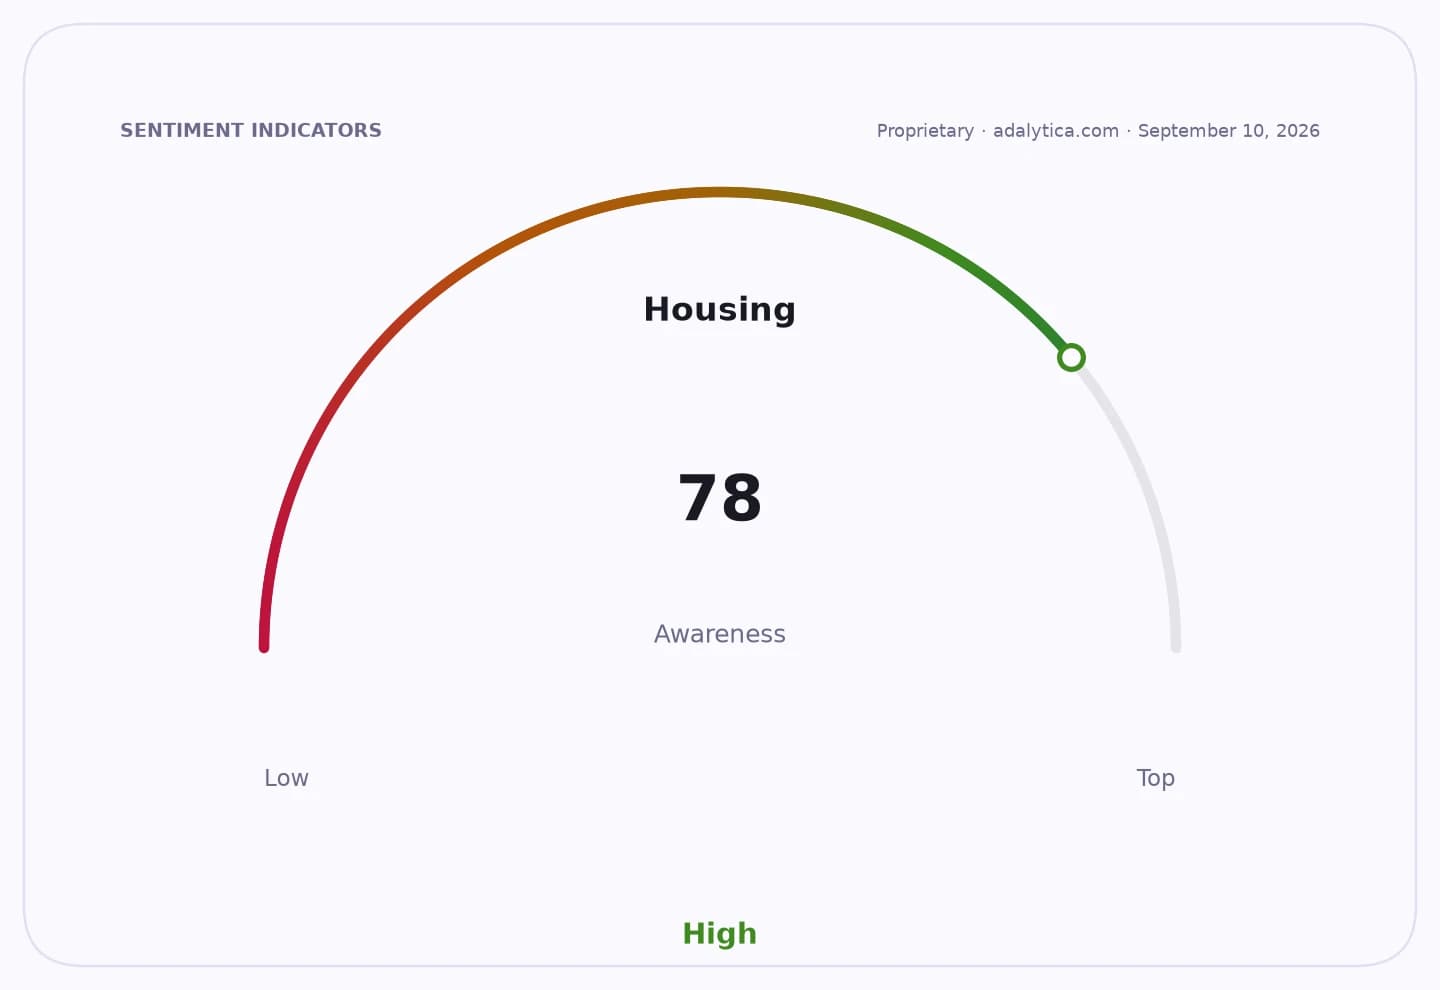
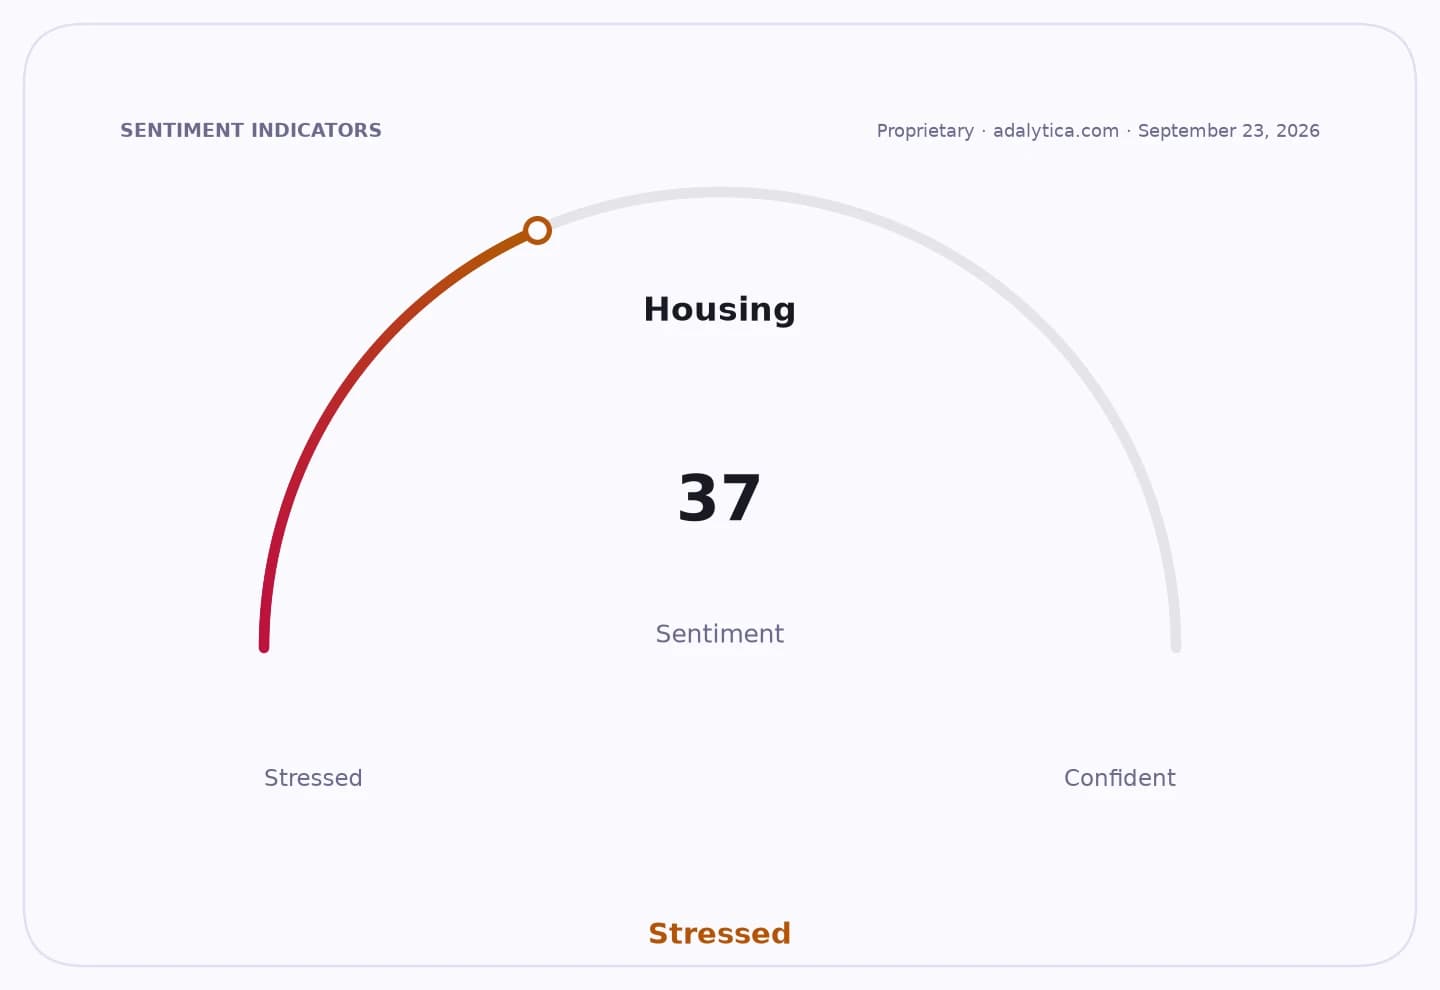
Sentiment IndicatorsⓘProprietary · adalytica.com · September 5, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The July list included six homes at $2 million or more and multiple sales above $1.5 million, with Upper Arlington alone producing the month’s three highest closings. Bexley followed closely, while New Albany and Worthington also featured prominently. That pattern suggests the luxury segment is less about a single trophy property than a durable pricing tier across several enclaves. For sellers, it points to continued pricing power in tightly held submarkets. For buyers, it confirms that premium inventory remains scarce and expensive, particularly in western and eastern suburbs closest to established employment centers and private-school networks.
The broader housing backdrop reinforces that reading. Columbus-area home sales in July fell 12.4% from June to 1,239, according to county auditor data, while the Case-Shiller index for the region shows prices still grinding higher, with the latest June reading up 0.37% month over month and about 0.85% projected for July. That combination — fewer transactions but resilient prices — is typical of a market that is absorbing higher financing costs by rationing inventory rather than slashing valuations. It also suggests that the upper end is acting as a stabilizer for headline price metrics even as turnover remains uneven.
Nationally, the 10-year Treasury yield sat near 4.8%, a reminder that mortgage rates remain elevated enough to keep many would-be buyers on the sidelines. Yet luxury homes are less exposed to rate pressure than entry-level housing, where monthly payment sensitivity is highest. That helps explain why the Columbus market’s most expensive deals continue to trade while broader sales volumes remain subdued. It also keeps pressure on the supply side: owners who are not forced to sell can wait, limiting the number of premium listings and supporting asking prices.
For investors and housing-market participants, the key takeaway is that Columbus remains a bifurcated market. The upper end is being driven by scarcity, income and neighborhood prestige, while the rest of the market continues to wrestle with affordability and lower turnover. Homebuilders, lenders and real estate brokerages with exposure to affluent suburbs stand to benefit more than those tied to first-time buyers. But if borrowing costs stay near current levels, the luxury segment may keep outperforming in price while still seeing only modest growth in transaction count.
The next question is whether this pattern broadens or narrows. If rates ease, activity could improve across the market, but premium neighborhoods are already demonstrating that they can command multimillion-dollar pricing even without a strong volume backdrop. If rates stay high, Columbus luxury homes are likely to remain a selective but resilient pocket of demand.
| Entity | Gains | Losses |
|---|---|---|
| Upper Arlington, Bexley, New Albany sellers | ▲Strong pricing power | ▼Limited inventory leverage |
| Luxury buyers with cash or high income | ▲Access to premier neighborhoods | ▼Less negotiating room |
| Realtors serving affluent suburbs | ▲High-value commissions | ▼Lower transaction volume elsewhere |
| First-time and rate-sensitive buyers | ▲— | ▼Affordability pressure |