Disney beat Wall Street’s earnings expectations and said it will increase content spending, a sign it is still willing to lean into streaming and studio investment even as the media business stays under pressure to prove it can grow profitably.
Disney raises content spending after earnings beat
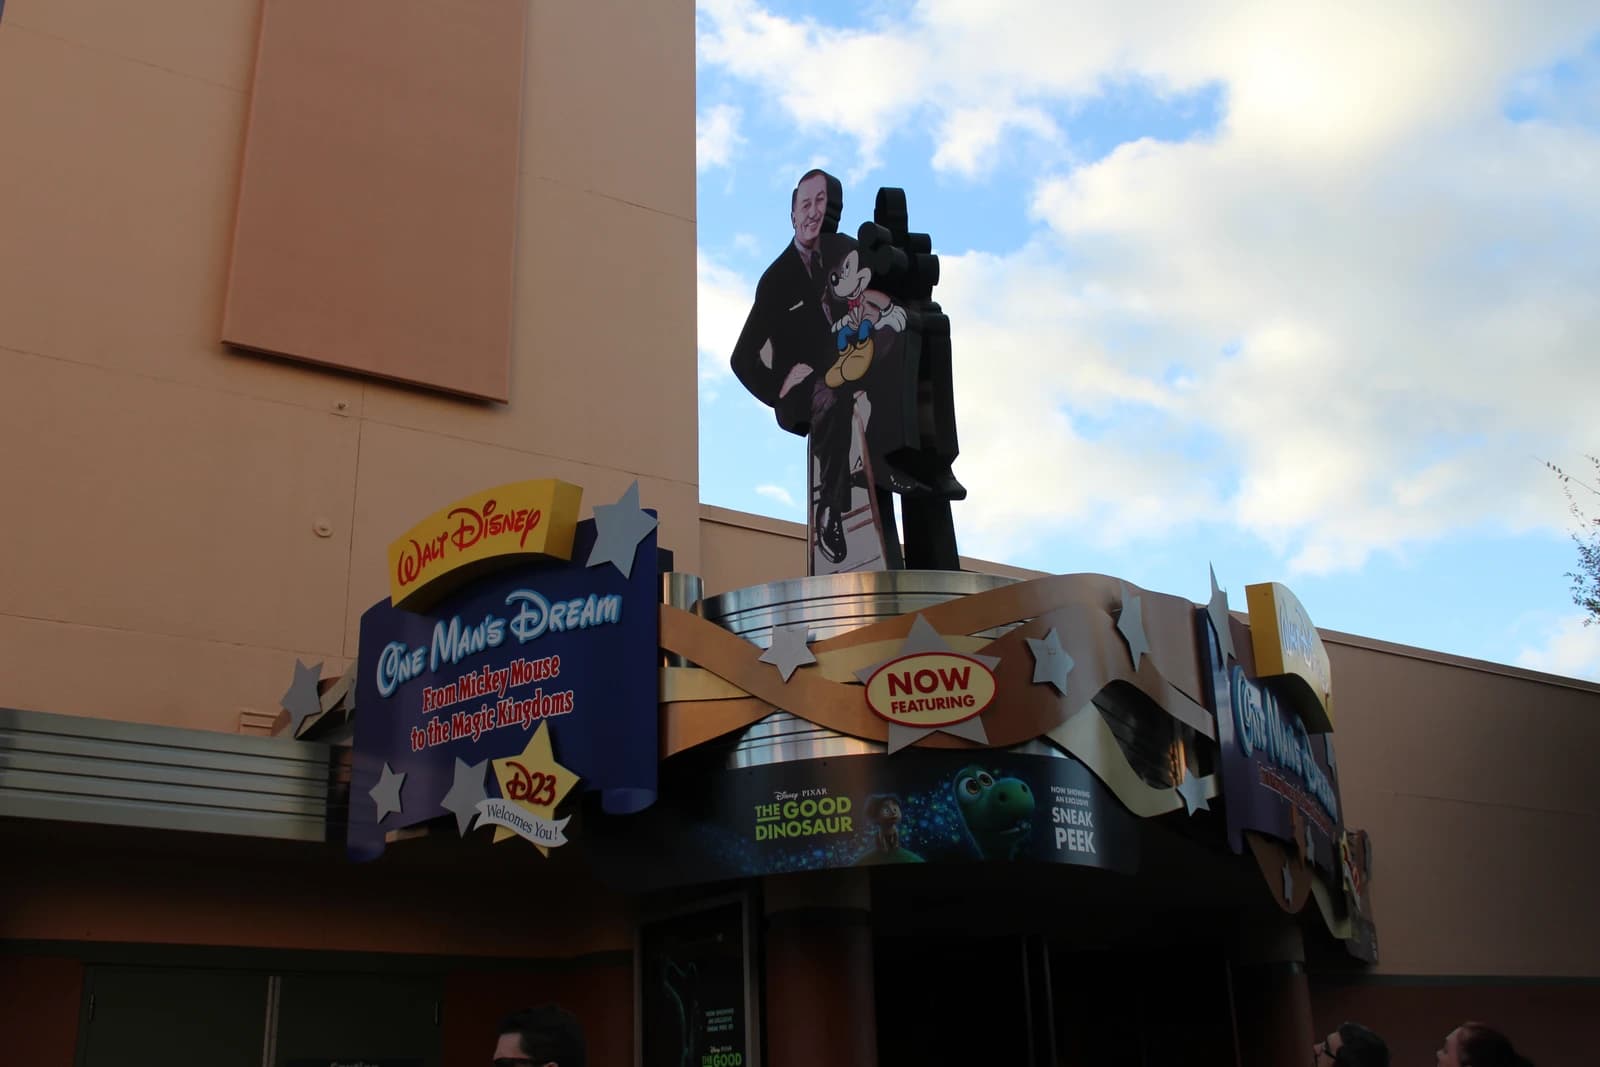
The bigger takeaway for investors is that Disney is choosing expansion over retrenchment. Higher spending on programming and franchises can support subscriptions, advertising and licensing, but it also raises the bar for returns at a time when media companies are being punished for undisciplined cash burn.
Sentiment Indicators
That spending decision matters because content remains the core input for Disney’s direct-to-consumer business. The company’s latest filing said the success of its streaming services depends in part on content and investment decisions, including more technology spending and local programming abroad, underscoring that the push is not just about filling a library but about competing globally against Netflix and other streamers.
Netflix shares were already under pressure, and Disney’s move highlights how expensive the fight for attention remains across the sector. Disney’s own stock has traded above both its 50-day and 200-day moving averages, with momentum indicators still constructive after a strong run, suggesting investors had been rewarding the company’s improving execution before the latest earnings update.
The backdrop is mixed for the broader market. Adalytica’s consumer spending sentiment gauge is in “extreme fear,” which points to a cautious household environment for discretionary entertainment spending, even as the S&P 500 trade-signal snapshot shows neutral overall sentiment. That makes Disney’s ability to convert content investment into pricing power, engagement and ad revenue especially important.
Disney’s earnings beat gives it room to spend, but it also sets up the next test: whether higher content outlays can keep streaming growth on track without eroding margins. Investors will be watching for management’s guidance on the pace of spending, subscriber trends and whether the company can turn more programming investment into stronger cash generation over the coming quarters.
| Entity | Gains | Losses |
|---|---|---|
| Disney | ▲Stronger content pipeline | ▼Higher spending burden |
| Streaming subscribers | ▲More programming options | ▼Potential price increases |
| Netflix and rivals | ▲Sector growth validation | ▼Tighter competition for viewers |
| Cost-conscious investors | ▲Better earnings beat | ▼Margin pressure from spending |