Europe’s business season starts with a split screen: investors are heading into a week of strategy updates and earnings against a backdrop of still-elevated services inflation, fragile domestic demand and signs that growth is losing momentum.
Europe Week Starts With PMI, Earnings, Riksbank
That mix matters because the next few sessions will help answer whether Europe is heading into a soft patch or simply cooling after a strong run. The stakes are highest for consumer-facing groups and rate-sensitive sectors, where guidance from Novo Nordisk, Société Générale, TUI, H&M and KWS Saat will feed directly into expectations for earnings, margins and household spending.
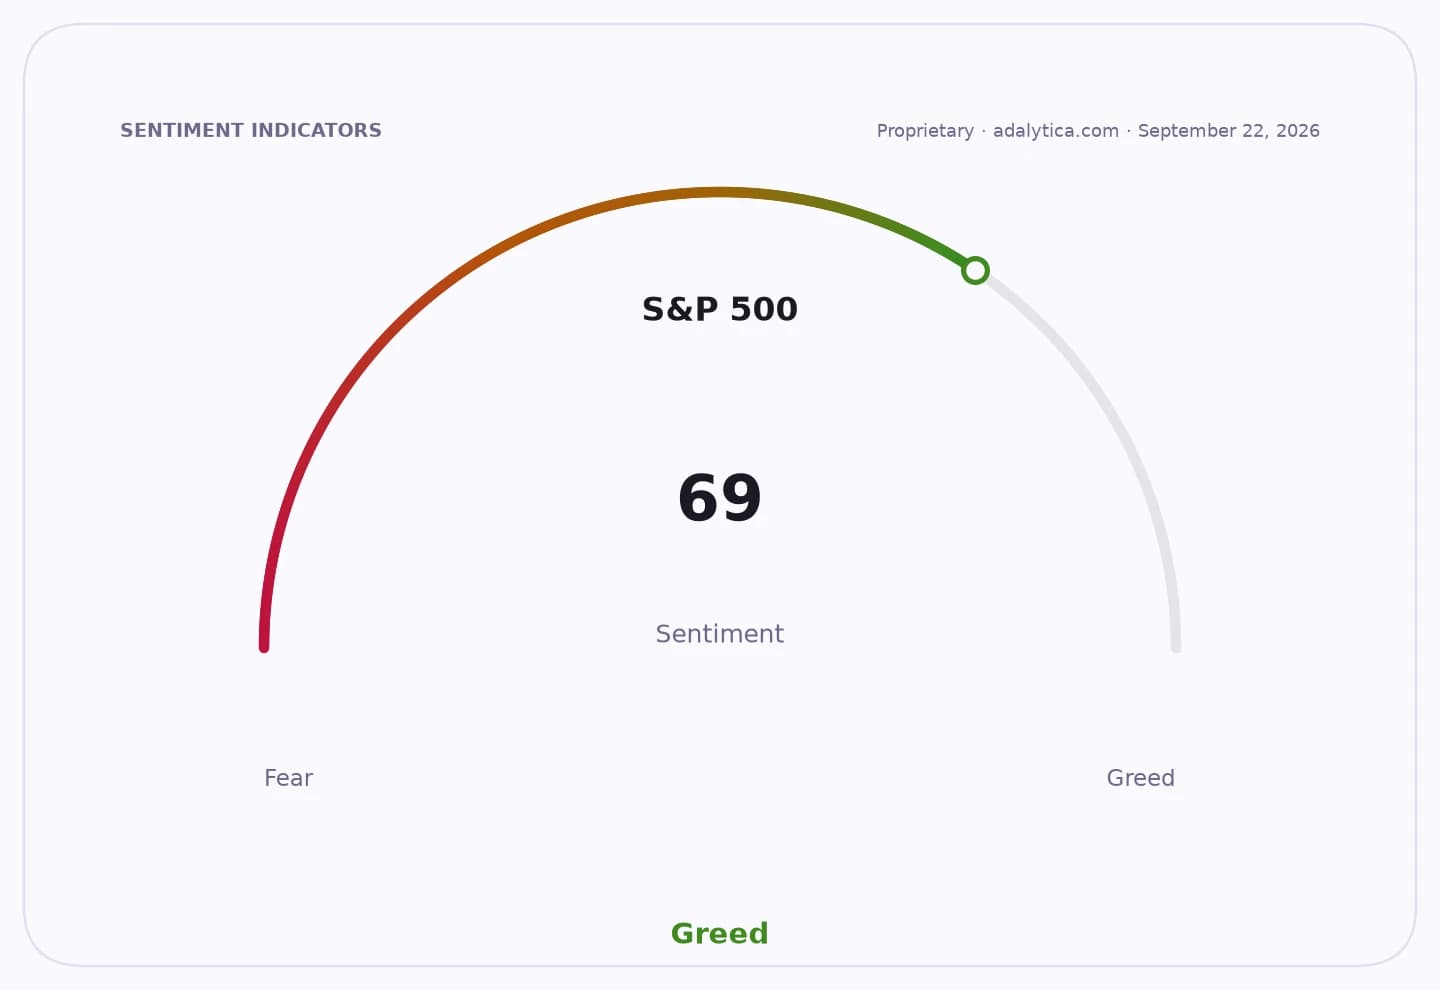
Sentiment IndicatorsⓘProprietary · adalytica.com · September 25, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The economic readout comes on Wednesday, when services PMI data for France, Germany, the euro area and Britain will offer a fresh snapshot of activity. Markets will be watching especially closely after recent evidence of slower momentum in luxury and discretionary spending, a warning sign for internal demand while borrowing costs remain restrictive.
Persistent price pressure in services is the other major thread. That keeps central banks, especially the Riksbank, under scrutiny on Thursday, when its rate decision will show whether policymakers think inflation is easing enough to justify any shift in tone.
For investors, the week is also a test of positioning in Europe-linked assets. The iShares MSCI EAFE ETF, which tracks developed markets outside the U.S., closed Thursday at 104.50 after losing ground from recent highs, while the Vanguard FTSE Europe ETF ended at 88.07. Both are trading below their recent 50-day moving averages, a sign of fading near-term momentum as traders wait for fresh catalysts.
The macro backdrop is mixed rather than outright weak. U.S. 10-year Treasury yields were at 4.96% on the latest reading and were seen little changed in the forecast ahead of Thursday’s session, while U.S. consumer prices were still rising on the month in August, underscoring why global policymakers remain cautious. That keeps the focus on whether Europe’s companies can defend margins even as demand cools.
The week’s corporate calendar could sharpen those themes. Novo Nordisk’s capital markets day and Société Générale’s strategic update on Monday may reset expectations for two of Europe’s closely watched financial and healthcare names, while TUI’s pre-close trading update on Tuesday will give an early read on tourism demand. H&M’s nine-month results on Thursday will be watched as a gauge of consumer resilience.
If the PMI data soften while company updates turn cautious, it would reinforce the view that Europe’s growth engine is stalling just as central banks are being asked to hold restrictive policy for longer. If the numbers surprise on the upside, investors may rotate back into cyclical and consumer names that have struggled to maintain momentum.
| Entity | Gains | Losses |
|---|---|---|
| Stronger Europe growth bulls | ▲Upbeat PMI surprise | ▼Slowdown narrative |
| Consumer and luxury retailers | ▲Solid H&M/TUI demand signals | ▼Weak discretionary spending |
| Banks and rate-sensitive stocks | ▲Clearer policy easing path | ▼Higher-for-longer rates |
| European equity ETFs | ▲Reacceleration in earnings growth | ▼Margin pressure and softer guidance |