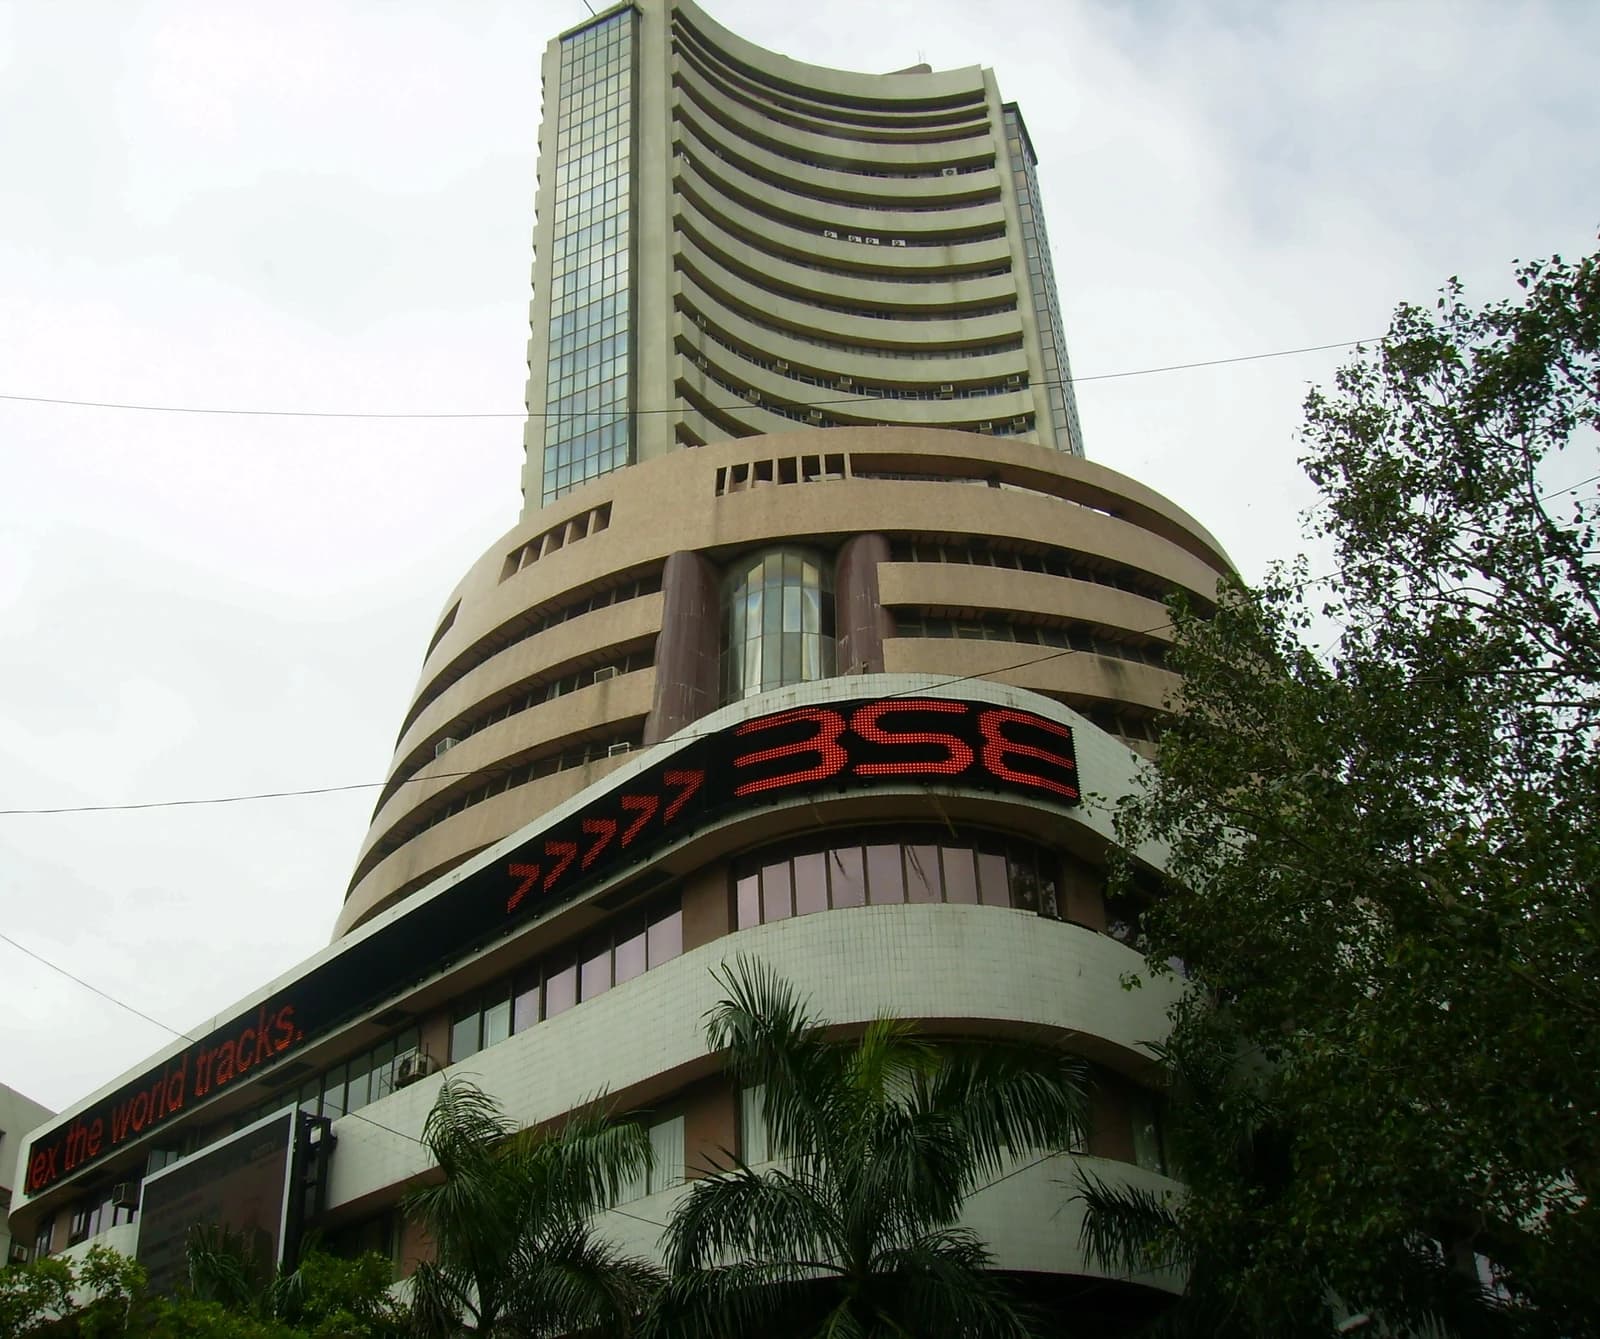
Corporate treasury operations are lining up to set up in GIFT-IFSC, a sign that India is trying to turn its flagship financial district into a real booking centre for cross-border cash management, payments and funding rather than just a policy showcase.
GIFT-IFSC Attracts Corporate Treasury Operations
That matters because treasury centres sit at the nerve centre of multinational finance: where cash is pooled, liquidity is managed, hedging is executed and intercompany funding is routed. If more companies shift those functions into GIFT-IFSC, India could capture fee income, deepen local dollar liquidity and strengthen its case as an alternative regional base for corporate finance work now concentrated in Singapore, Hong Kong and Dubai.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 14, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The push comes as New Delhi and Gujarat intensify efforts to make GIFT City useful for routine corporate operations, not just niche offshore structures. Treasury functions are especially attractive because they are less politically sensitive than manufacturing relocation, but still high-value: they can bring predictable flows from foreign exchange conversion, short-term deposits, trade finance and intercompany lending. For India, that is economically meaningful because it supports services exports, employment for finance and compliance professionals, and a broader internationalization of the country’s financial system.
The development also fits a wider pattern of multinationals looking to diversify operational hubs amid geopolitical friction and shifting tax regimes. A corporate treasury base in GIFT-IFSC can offer regulatory clarity, tax efficiency and proximity to Indian subsidiaries at a time when firms are reassessing Asia supply chains and cash pools. The latest move by NISM to launch cyber security and cyber resilience certification courses for the GIFT-IFSC ecosystem underscores that the authorities are also trying to build the plumbing — talent, controls and risk management — that treasury operations require.
For investors, the opportunity is less about a near-term market catalyst than about a gradual rerating of India’s financial infrastructure story. A deeper GIFT-IFSC ecosystem could benefit banks, custodians, fintech firms, professional services groups and landlords tied to the district, while also supporting the longer-term investment case for Indian financial liberalization. It could also matter for currency markets if more offshore treasury activity is intermediated through India rather than through external centres, although that shift would likely be incremental.
The market backdrop is supportive but not risk-free. Adalytica’s US dollar trade signals show the dollar still trading with elevated greed, while broader risk sentiment in equities has been fragile, which keeps the cost of global funding and FX hedging relevant for treasurers. Against that backdrop, corporate finance teams will only move if GIFT-IFSC can prove it offers not just tax advantages, but speed, legal certainty, banking depth and operational reliability.
The bull case is that GIFT-IFSC becomes a sticky regional hub for treasury and adjacent financial activities, with network effects drawing in banks, advisers and specialist service providers. The bear case is that companies test the waters but keep their main cash pools in established centres, limiting GIFT to a peripheral role. The next stage to watch is whether the current queue turns into executed mandates, because that will determine whether India’s financial hub ambition is becoming a balance-sheet reality.
| Entity | Gains | Losses |
|---|---|---|
| GIFT-IFSC | ▲More treasury mandates | ▼Peripheral financial centres |
| Multinationals | ▲Lower operating costs | ▼Higher-friction hubs |
| Indian banks and advisers | ▲New fee income | ▼Offshore incumbents |
| India’s policymakers | ▲Services-led credibility | ▼Slow reform narrative |