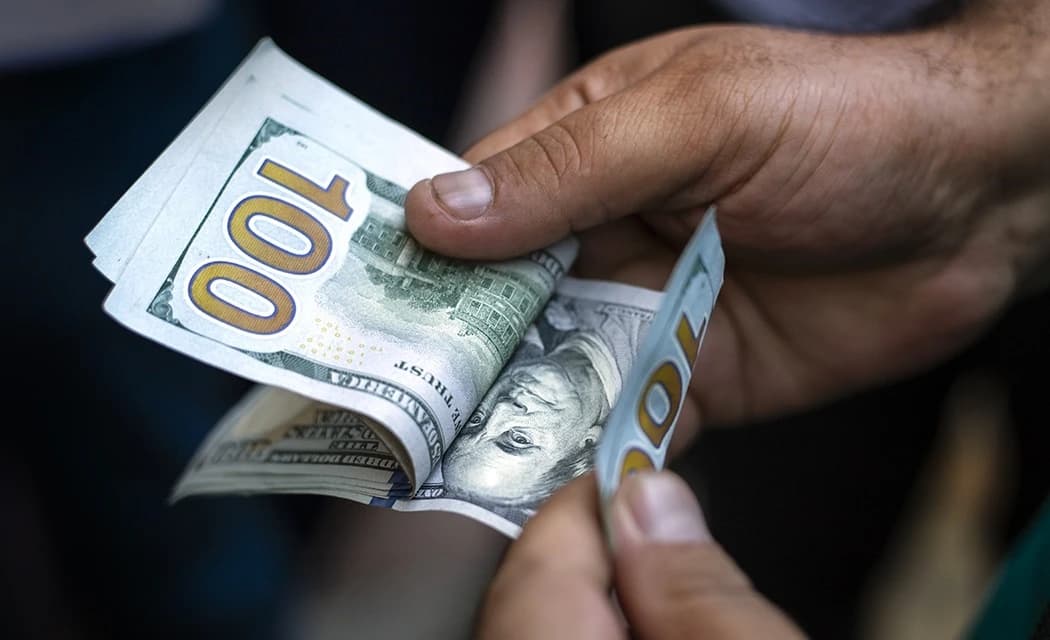
Global remittances are on track to reach $729 billion in 2025, nearly doubling in a decade and reinforcing their role as a vital source of foreign exchange for lower- and middle-income countries, according to an IFAD report.
Global remittances seen reaching $729 billion in 2025

That matters because remittance flows now rival or exceed many countries’ export earnings, helping households pay for food, rent and school fees while propping up balance-of-payments positions in economies where dollar inflows are often scarce. Unlike aid, the money goes straight to families, making it one of the most resilient forms of external financing.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 17, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The surge also has a market angle. Stronger and more persistent transfer flows support demand for money-transfer operators, banks with remittance rails and payment networks, while highlighting the structural importance of cross-border payments in consumer finance. Western Union, for example, has said its consumer money transfer business is a key measure of its share of the global remittance market, even as revenue there has faced pressure and the company now contends with a 1% U.S. excise tax on certain cash-funded international remittances.
For investors, the bigger takeaway is that remittances are becoming more important to currency stability and domestic demand in recipient markets, which can soften credit risk and support spending in fragile economies. They also make remittance corridors more exposed to regulation, foreign-exchange swings and fee competition, all of which can hit margins for operators and payments firms.
The report comes as the U.S. dollar remains firm and technical indicators on major remittance-linked stocks such as Western Union show continued pressure, with the shares trading below both their 50-day and 200-day moving averages. Visa, which benefits from cross-border payments activity, has held up better, helped by travel and e-commerce-related volume.
The next catalyst is whether remittance growth keeps outpacing slower global trade and aid flows, and how much of that expansion is absorbed by taxes, tighter enforcement and pricing pressure in major sending markets.
| Entity | Gains | Losses |
|---|---|---|
| Emerging-market households | ▲Steadier cash support | ▼More exposure to fees and FX swings |
| Recipient-country economies | ▲Stronger FX inflows | ▼Dependence on migrant income |
| Western Union and peers | ▲Higher transfer volumes | ▼Margin pressure from taxes and competition |
| Visa and payment networks | ▲More cross-border volume | ▼Limited direct benefit from cash-based corridors |