Grab Holdings lifted its full-year 2026 outlook after quarterly active users hit a record 57.2 million, underscoring how the Southeast Asian super-app is turning scale into faster revenue growth and improving profitability even with fuel costs elevated across the region.
Grab raises 2026 revenue and EBITDA outlook
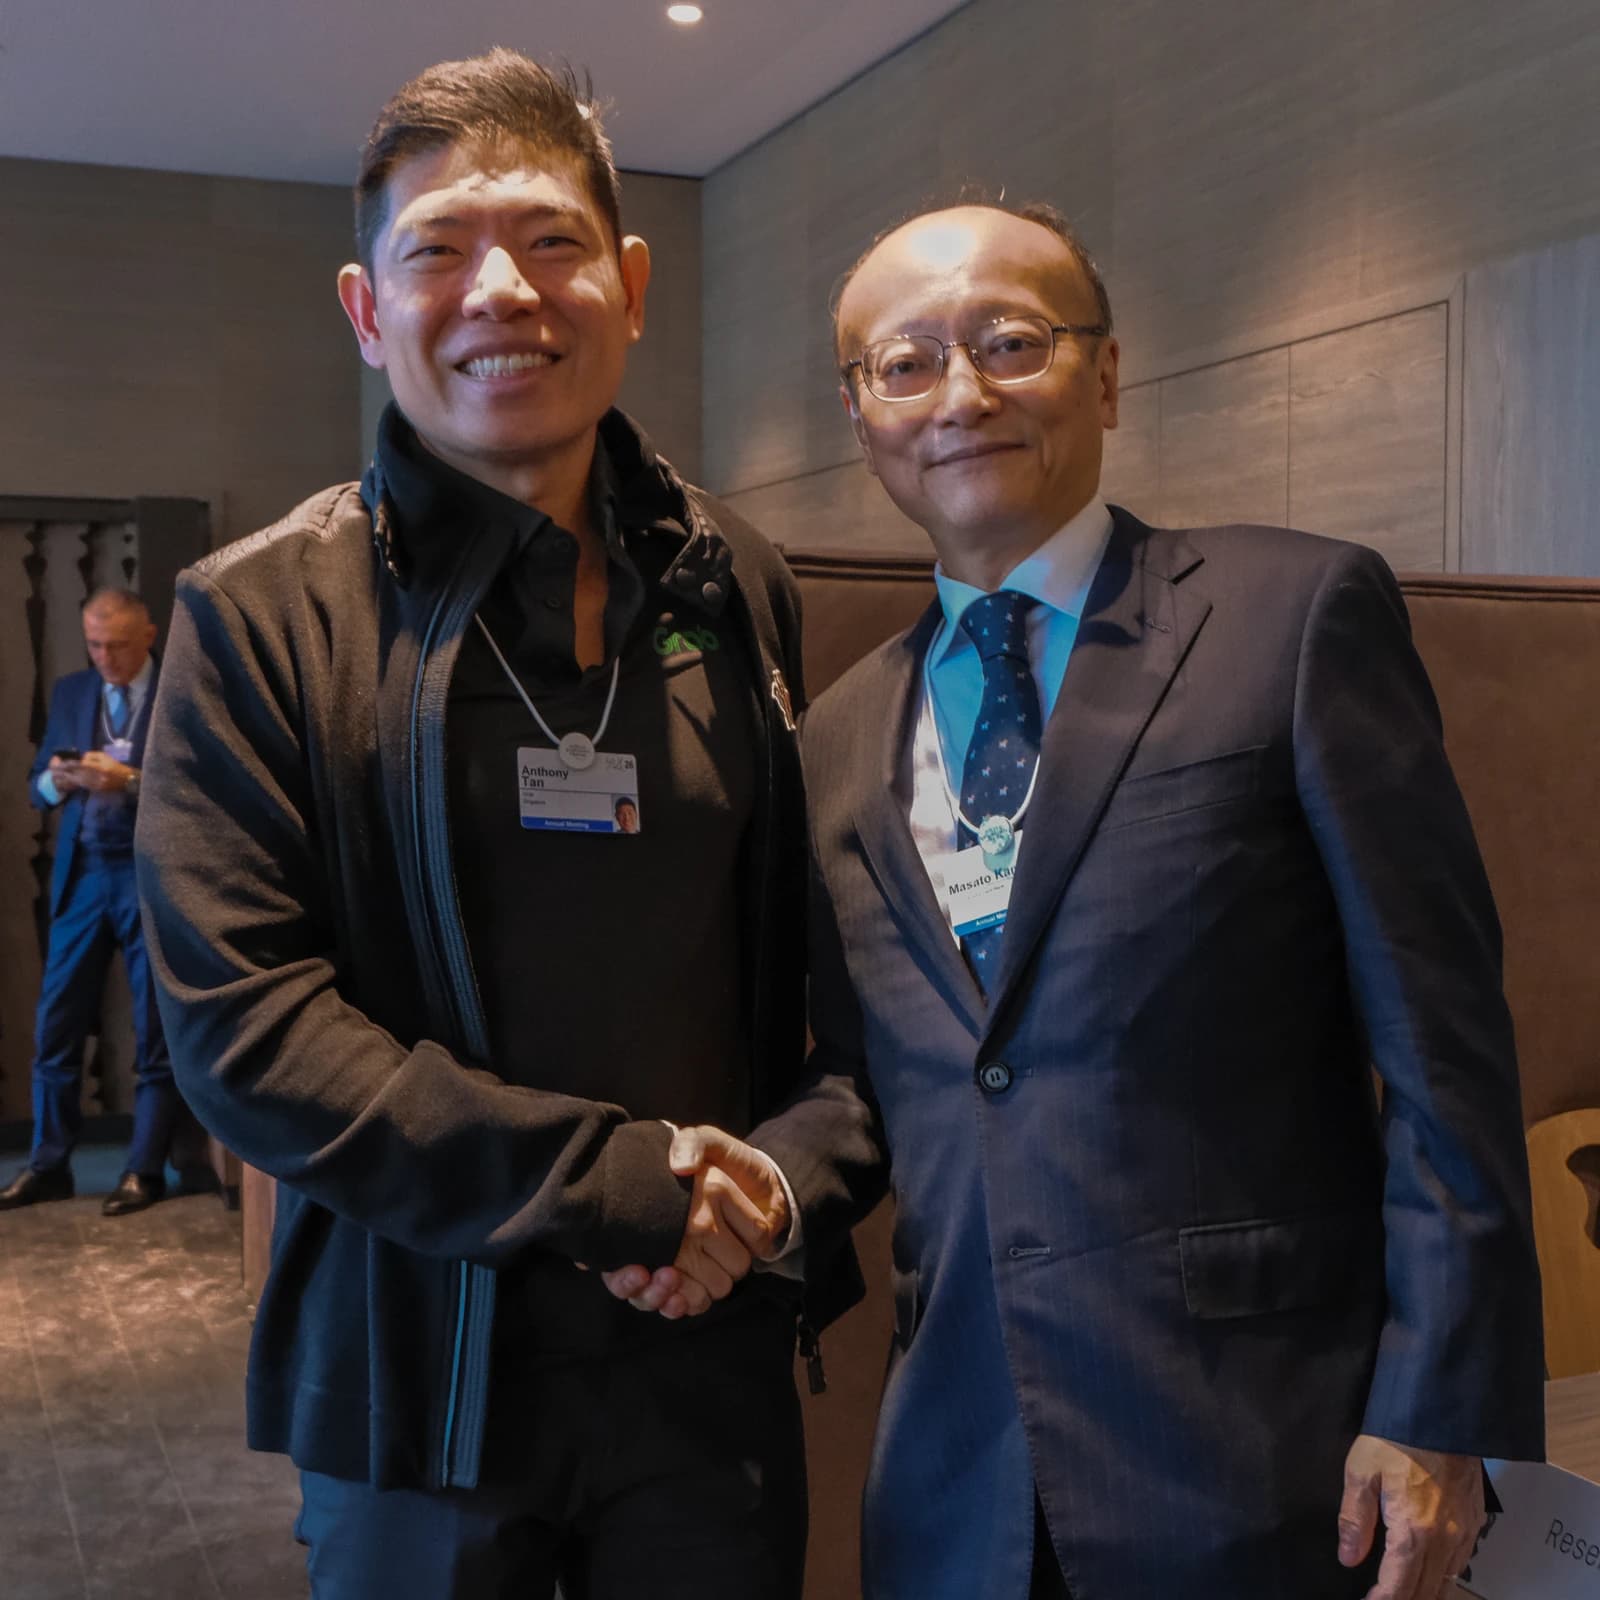
The stronger user base is the key economic driver: more riders, diners and merchants across Grab’s ride-hailing, food delivery and financial services businesses translated into 27% year-on-year revenue growth to $1.112 billion in the third quarter, while group gross merchandise value rose across both mobility and delivery. For investors, the update strengthens the case that Grab can keep widening margins in a low-penetration market where digital adoption remains early and operating leverage is still building.
Adjusted EBITDA jumped 73% to $237 million, the company’s 19th straight quarter of year-on-year improvement on that metric, while operating profit surged 297% to $108 million. Grab’s financial services arm delivered its first positive adjusted EBITDA of $12 million, a sign the company is broadening profitability beyond its core delivery and ride-hailing units.
The company now expects 2026 revenue of $4.15 billion to $4.20 billion, up from a prior range of $4.10 billion to $4.15 billion, and adjusted EBITDA of $790 million to $800 million, versus an earlier $720 million to $740 million. Management said the upgrade reflects operating leverage across the platform, helped by AI tools, merchant monetization and access to financing for drivers and sellers.
Grab also said adjusted free cash flow over the past 12 months reached $533 million, nearly double the prior period, and that it spent $400 million on buybacks in September and October. The company said a $60 million break fee tied to the abandoned foodpanda Taiwan acquisition will hit fourth-quarter costs, but will not change its 2026 revenue or EBITDA guidance.
The next test is whether Grab can keep converting user growth into cash flow and earnings while competing with regional peers and absorbing macro pressure in Southeast Asia. For shareholders, the focus now shifts to whether the raised targets prove conservative going into year-end.
| Entity | Gains | Losses |
|---|---|---|
| Grab | ▲Higher guidance, stronger cash flow | ▼Break fee from foodpanda deal |
| Investors | ▲Better earnings outlook, buybacks | ▼M&A execution risk |
| Drivers and merchants | ▲More demand, more monetization tools | ▼Pressure to share gains with platform |
| Rivals in Southeast Asia | ▲— | ▼Grab’s scale and profit momentum |