Greek savers are still getting almost nothing for their money, and that matters because the country’s banks are sitting on abundant deposits, face little pressure to compete for them, and are effectively paying households to stay put while rewarding only fresh cash.
Greek banks keep deposit rates near zero
That is the blunt message from European Central Bank data for September, which show the average Greek rate on one-day deposits at just 0.03%, versus 0.30% across the euro zone. For term deposits, Greece averaged 1.29%, well below the 2.37% euro-area average and second only to Slovakia at the bottom of the ranking. By comparison, banks in Italy were paying 2.90%, Finland 2.85% and Germany 2.43%.
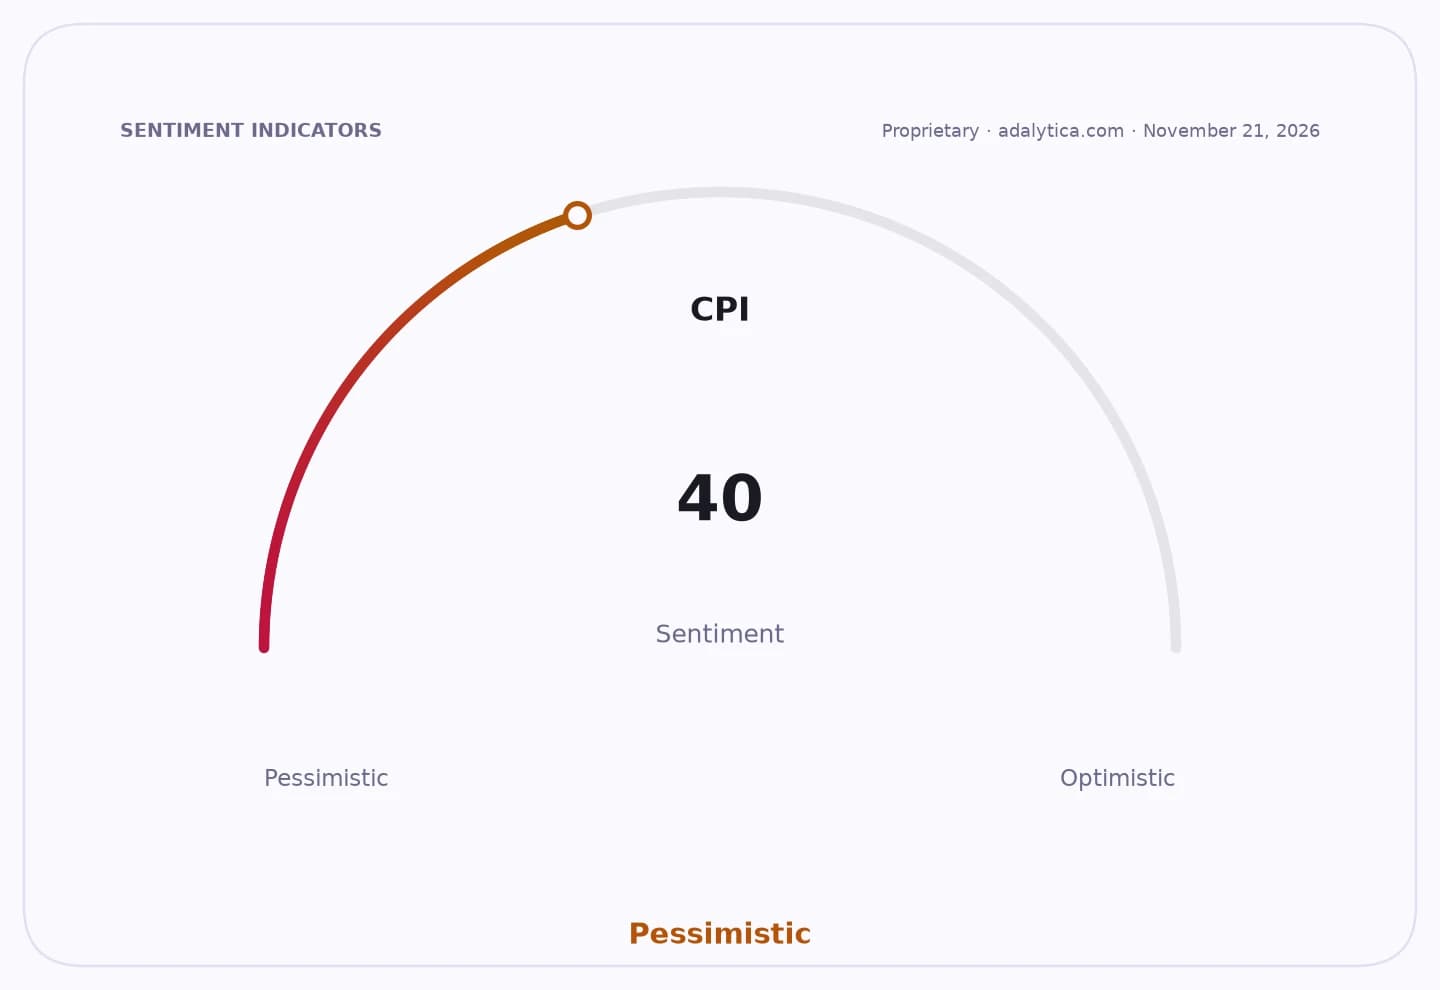
Sentiment Indicators
ECB Policy Direction
For investors, the story is not just about frustrated savers. It is about the economics of a banking system awash in liquidity. Greece’s loan-to-deposit ratio has fallen to about 60% from 133% in 2015, according to the Competition Commission, and deposits have risen by roughly 70 billion euros since 2018. In plain English: banks do not need the money badly enough to bid aggressively for it. When funding is plentiful and stable, margins tend to stay comfortable, even if customers lose out.
That is exactly why the market structure matters. The four systemic Greek banks controlled 94.07% of total deposits at the end of 2024, leaving little room for price competition. The Competition Commission also found that 80% of retail customers and 84% of businesses did not even shop around for deposit transfer information over the past two years. In a market this concentrated and this inert, banks can keep rates low for existing clients while offering better deals only on “new money” — sometimes as high as 2.25% from smaller lenders trying to win share.
There is also a practical friction that keeps deposits sticky: moving money between banks can trigger fresh source-of-funds checks, even when the money is already legal and already inside the Greek banking system. Cross-border transfers can bring even more compliance scrutiny. None of that blocks savers from chasing better yields, but it raises the cost and hassle of doing so, which helps the banks preserve pricing power.
For long-term investors, the implication is straightforward. Greek banks have a structural advantage from low funding costs and strong deposit retention, but consumers are not seeing much of that benefit. Unless competition from smaller lenders and digital entrants intensifies, deposit rates are likely to remain subdued, especially for existing customers. That makes the sector attractive from a funding-stability perspective, but it also means depositors should keep looking for better options — and shareholders should remember that a bank’s cheapest capital often comes from customers who never move.
| Entity | Gains | Losses |
|---|---|---|
| Greek banks | ▲Cheap stable funding | ▼Pressure to raise deposit rates |
| Existing depositors | ▲Safety of insured cash | ▼Near-zero returns |
| Smaller banks | ▲New customer inflows | ▼Margin pressure on offers |
| Savers who shop around | ▲Better promotional rates | ▼Compliance hassle and delays |