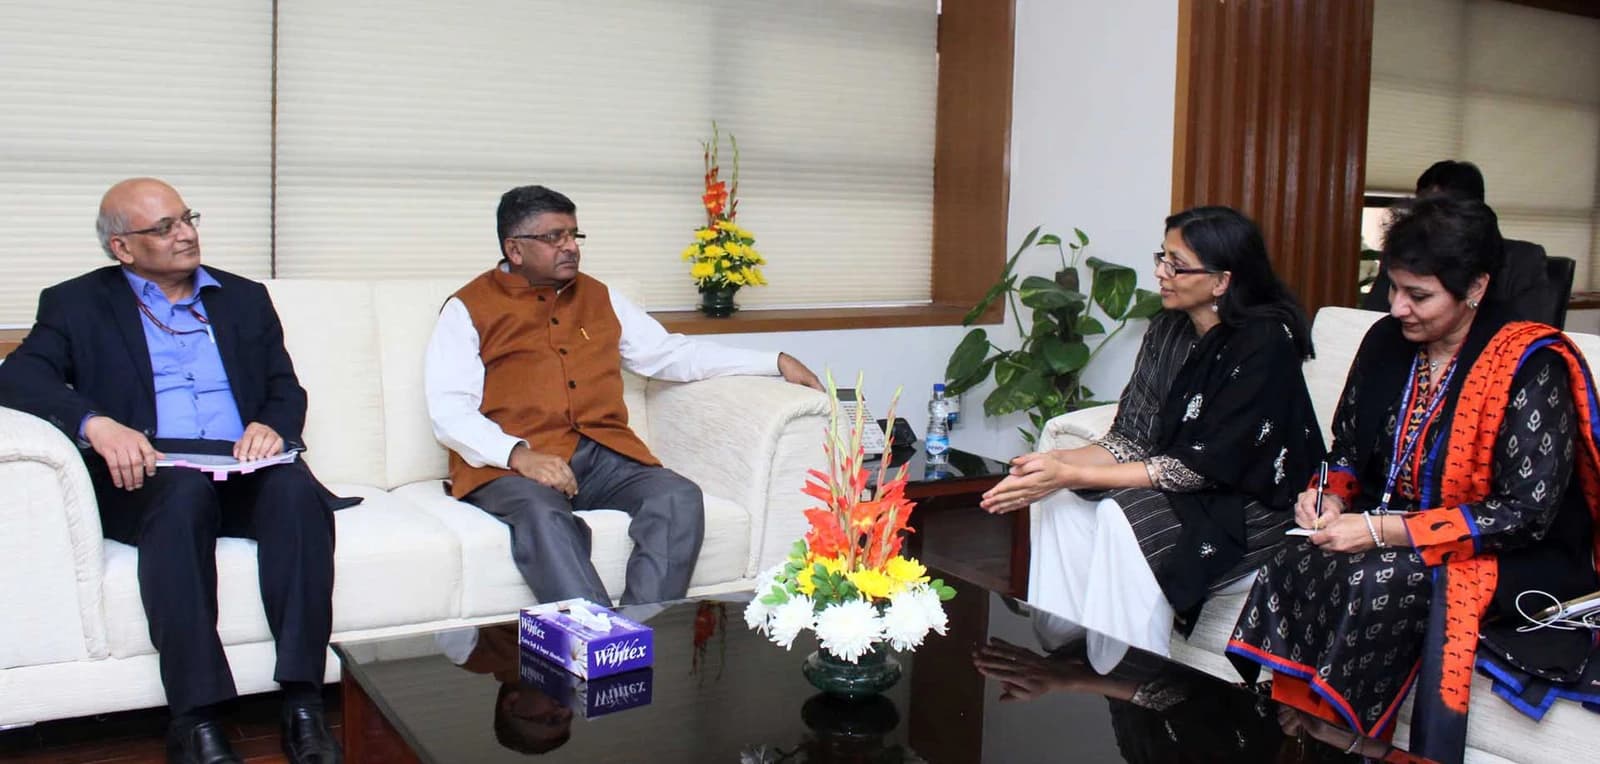
Haryana’s invitation to Singapore investors is another sign that India’s state governments are competing harder for foreign capital just as global money looks for alternatives to China and a weaker U.S. dollar backdrop improves appetite for emerging markets.
Haryana Courts Singapore Investors for FDI
The pitch matters because India’s growth story is increasingly being sold state by state, not just from New Delhi. For investors, that creates a broader, more tradable opportunity: capital is likely to flow into industrial parks, logistics, real estate, green energy, and export-oriented manufacturing clusters where policy support can translate into faster earnings growth than the market currently prices in.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 4, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Singapore is a particularly important target. Its sovereign wealth funds, infrastructure groups, ports operators, real estate investors and family offices are natural partners for Indian states seeking long-duration capital. Haryana sits next to Delhi and already has a deep industrial base, so any new commitments could reinforce its role as a manufacturing and services hub in north India rather than a mere satellite to the capital region.
That is where the market underestimates the story. India is trying to capture the same supply-chain diversification that has pushed manufacturers to Vietnam, Mexico and Indonesia, but with the added scale of a domestic market and a policy push to build out transport, power and digital infrastructure. If Singapore-linked capital helps accelerate that buildout, the winners are not only local developers and industrial names, but also listed companies tied to freight, power equipment, construction materials and finance.
The macro backdrop is supportive. Adalytica’s U.S. dollar trade signals show the greenback in a fear regime, while its China growth-target sentiment remains elevated. That combination points to an environment where investors are more willing to fund Asian growth stories outside China, especially those tied to capex and infrastructure rather than pure consumption. India remains one of the clearest beneficiaries of that rotation.
For equity investors, the key is to look past the headlines and toward the second-order effects. Foreign direct investment tends to show up first in land, warehouses, roads, utilities and industrial services before it reaches broad-market earnings revisions. Exchange-traded funds such as the iShares MSCI India ETF and the India-specific infrastructure and industrials complex remain the cleanest ways to express that view, while selective exposure to logistics, capital goods and private banks offers more upside if the capital cycle accelerates.
The real catalyst will be whether Haryana turns this courtship into signed commitments, especially in manufacturing, urban infrastructure and supply-chain assets. If it does, the story stops being a ceremonial investment pitch and becomes part of a larger re-rating of India’s industrial corridor. I believe the market still underprices that shift, and the investors who position early in India’s infrastructure and manufacturing enablers are likely to capture the best part of the upside.
| Entity | Gains | Losses |
|---|---|---|
| Haryana industrial corridor | ▲FDI inflows, jobs, capex | ▼Slow-moving domestic projects |
| Singapore investors | ▲India growth exposure, long-duration assets | ▼Returns from staying on sidelines |
| Indian infrastructure stocks | ▲Order visibility, valuation rerating | ▼Cash-rich incumbents without expansion |
| China-linked suppliers | ▲Less share of Asia capex | ▼Manufacturing diversification away from China |