India's economy is showing the kind of breadth investors want from a structural winner: industrial output jumped 8% in August, with manufacturing rising 9%, underscoring that the country's next leg of growth is being built on factories, capex and exports rather than on the current AI trade alone.
India industrial output rises 8% in August
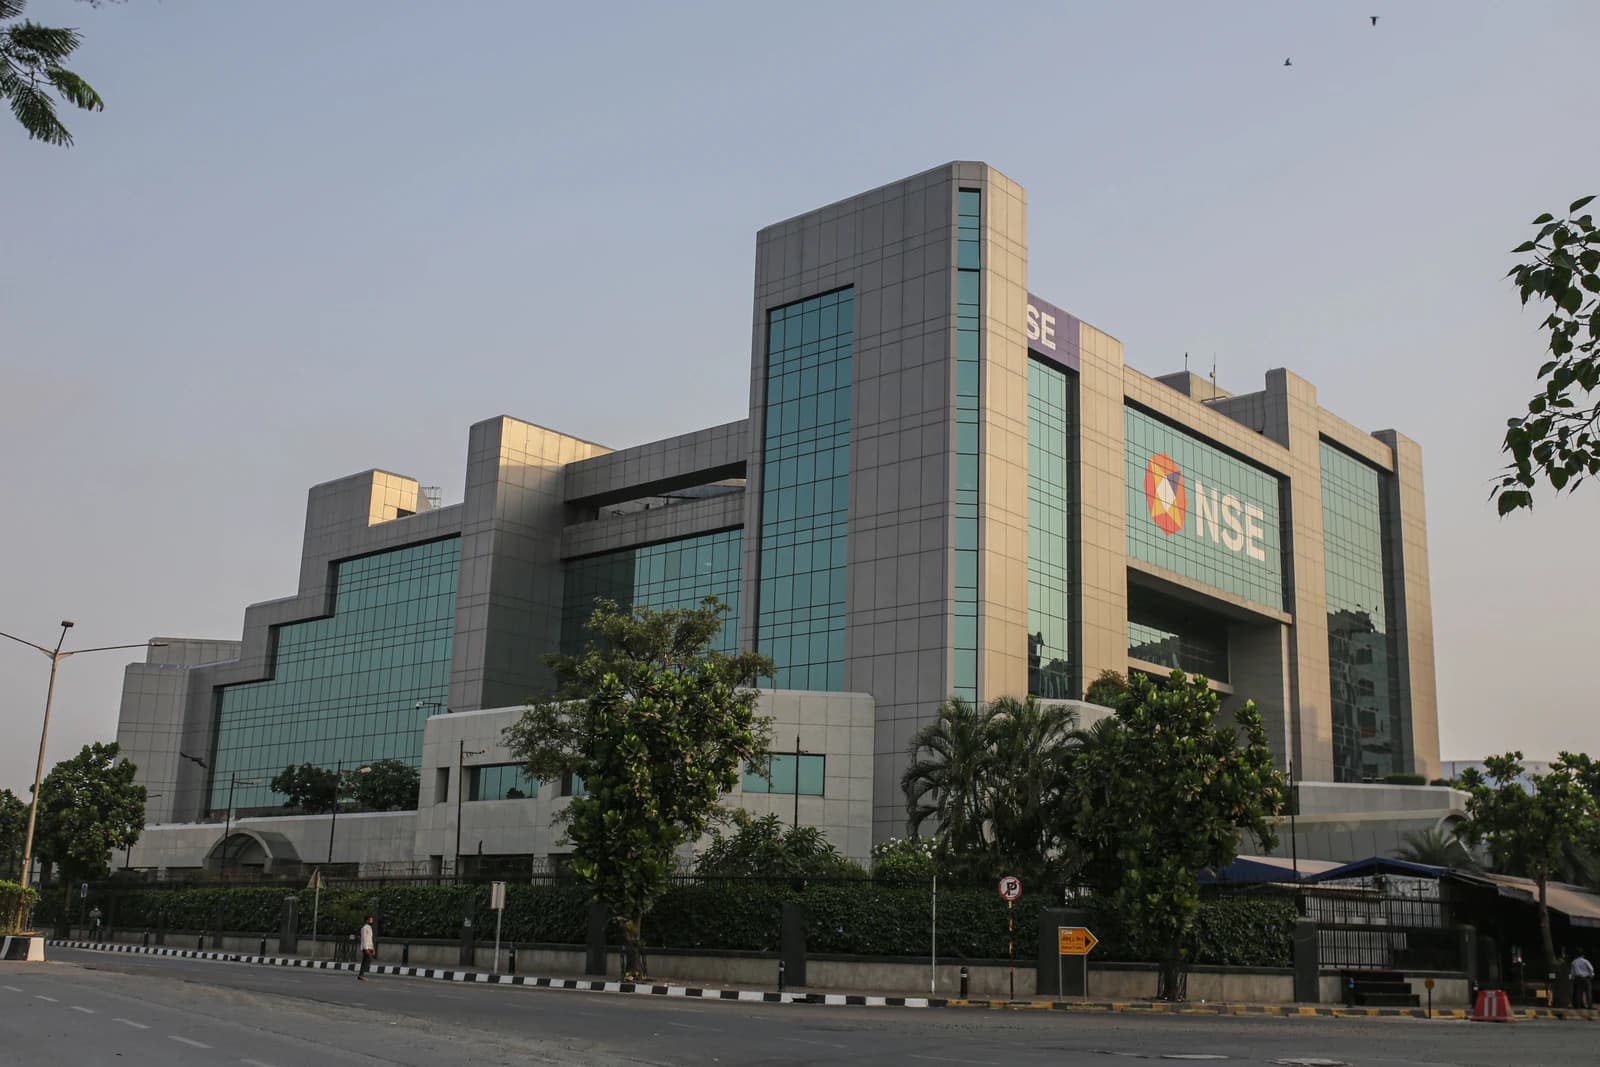
That matters because the market has been inclined to think about India in one narrow frame — as a beneficiary of global digital spending, services and AI-linked enthusiasm. But the latest output data point to something more durable: a domestic expansion engine that is still gaining traction. When manufacturing is growing at 9% and industrial production is accelerating, it suggests the investment cycle is still alive, supply chains are deepening and corporate revenue growth can broaden across sectors.
The bigger macro message is that India is not waiting for a single theme to carry it. The data fit a much larger story of steady GDP expansion and rising policy confidence. Global agencies have been lifting their growth outlooks, and the government is leaning on technology, innovation, startups, agriculture and exports to push the economy higher. Finance Minister Nirmala Sitharaman has said India could potentially surpass 10% growth with the right mix of effort and investment. Whether or not that exact target is reached, the direction of travel is what counts for markets: faster nominal growth, stronger industrial demand and a longer runway for earnings.
For investors, that creates an important asymmetry. India is no longer just a “wait for AI” or “buy consumer demand” story. It is increasingly a capital-expenditure story, a manufacturing story and an infrastructure story. That tends to favor the picks-and-shovels of the next cycle: industrials, capital goods, logistics, power, building materials, selected banks and the ETFs that capture the broader domestic growth trade. If the economy keeps compounding at this pace, the second-order beneficiaries are likely to outperform the headline AI names that have absorbed so much attention.
The latest price action already reflects some of that tension. India-focused ETFs have been volatile, with EPI and INDA both trading below their 50-day and 200-day moving averages, while MCHI — a China proxy — has also lost momentum. That tells us the market is not yet fully pricing India’s relative growth advantage as a sustained earnings story. In our view, that is the opportunity. The macro is improving faster than sentiment, and that gap is where returns are usually made.
The near-term catalyst is straightforward: if industrial production keeps printing strong numbers, and if capex and exports continue to support manufacturing, analysts will be forced to widen earnings assumptions across India’s domestic cycle. That should keep the multi-year thesis intact even if the AI trade cools globally. For investors looking for the next structural growth engine, India still looks under-owned, under-allocated and underappreciated.
| Entity | Gains | Losses |
|---|---|---|
| India industrials | ▲Higher output, stronger orders | ▼Weak-capex laggards |
| Domestic banks | ▲Loan growth, project finance | ▼Cash-rich defensives |
| India ETFs (EPI, INDA) | ▲Re-rating potential | ▼Short-term momentum traders |
| China proxies (MCHI) | ▲Relative comparison pressure | ▼Capital seeking faster growth |