U.S. demand for power equipment is outrunning supply, pushing Hitachi and Siemens to expand American facilities as utilities, data centers and factories strain an aging grid and transformer lead times remain long. The rush matters because transformers sit at the center of the electrification buildout: without them, new generation, transmission upgrades and large industrial projects cannot connect to the grid on schedule.
Hitachi, Siemens Expand U.S. Grid Equipment Capacity
The investment push reflects a broader industrial bottleneck that has become more important than the headlines around semiconductors. Bay Area land prices have been rising on logistics expansion even as semiconductor site growth cools, but the real constraint for the next phase of U.S. infrastructure is electrical hardware — the heavy transformers, switchgear and related equipment needed to move power where it is consumed. In that sense, the most valuable real estate in 2030 may be the factory floor that can produce grid hardware, not the warehouse that stores it.
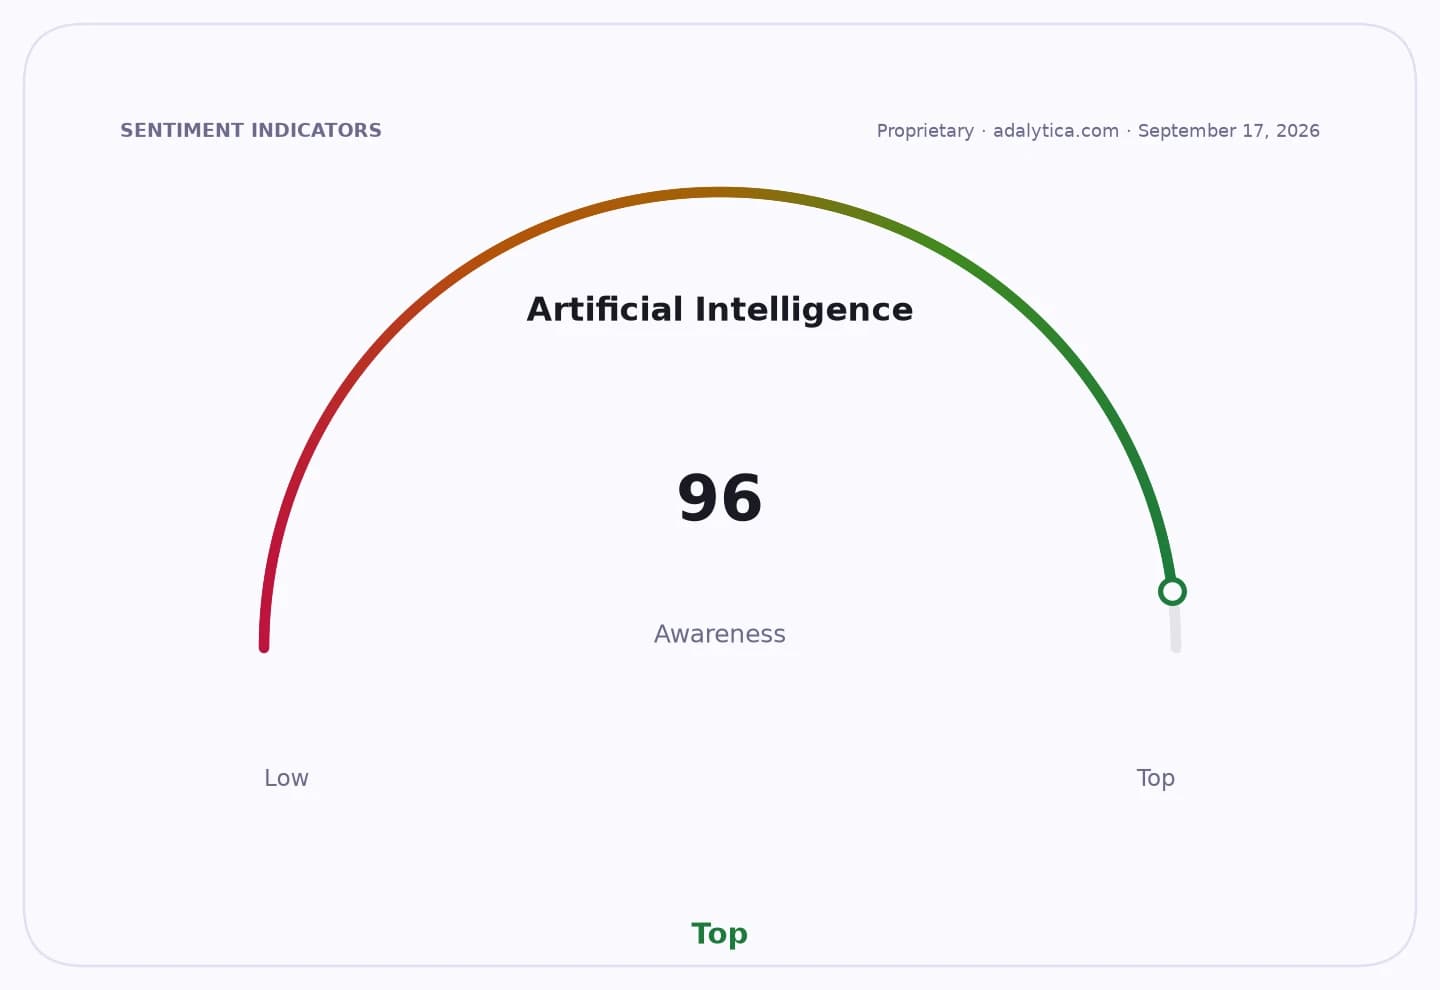
Sentiment IndicatorsⓘProprietary · adalytica.com · September 18, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That dynamic is favorable for companies with manufacturing scale and balance-sheet capacity. Hitachi’s American depositary shares have climbed to 35.55 from 27.66 in October, while the price action has stayed above the 50-day and 200-day moving averages, though the stock’s 14-day RSI at 59.7 suggests the recent advance has eased from overbought levels. Siemens’ U.S.-listed shares have also firmed to 36.68 from 29.65 in November, with trading now comfortably above both longer-term averages. Eaton, another major beneficiary of the electrification cycle, has held around $412.71 after a volatile run that took it as high as $434.71 in June.
For investors, the message is that the grid supply chain is becoming a secular capital-spending theme rather than a cyclical afterthought. Utilities are still dealing with backlogs, developers of data centers need faster interconnection, and manufacturers expanding U.S. capacity increasingly require local power infrastructure before they can bring projects online. That supports pricing power for the limited number of firms that can make large transformers and related systems, but it also raises the risk that execution, labor shortages and permitting delays will cap near-term margin gains.
The bull case is straightforward: years of underinvestment, electrification and AI-related power demand are forcing customers to lock in domestic capacity, and that should support orders well into the end of the decade. The bear case is that the buildout is capital intensive, supply chains remain tight and any slowdown in power demand growth could leave new plants underutilized once the backlog normalizes. For now, the market is treating U.S. facility expansion as evidence that the transformer shortage is not a passing problem but one of the defining industrial bottlenecks of 2030.
| Entity | Gains | Losses |
|---|---|---|
| Hitachi | ▲U.S. order visibility | ▼Capacity constraints |
| Siemens | ▲Local production foothold | ▼Import dependence |
| Eaton | ▲Higher grid spending | ▼Competitor catch-up |
| Utilities and data centers | ▲Faster equipment access | ▼Higher procurement costs |