Home Depot’s stock looks stuck until housing turnover recovers, and that makes mortgage rates the biggest catalyst for the shares. The home-improvement giant is still trading about 22% below 24/7 Wall St.’s $357.14 price target, leaving roughly 22% upside if deferred projects and transactions start to come back.
Home Depot Needs Lower Mortgage Rates for Upside
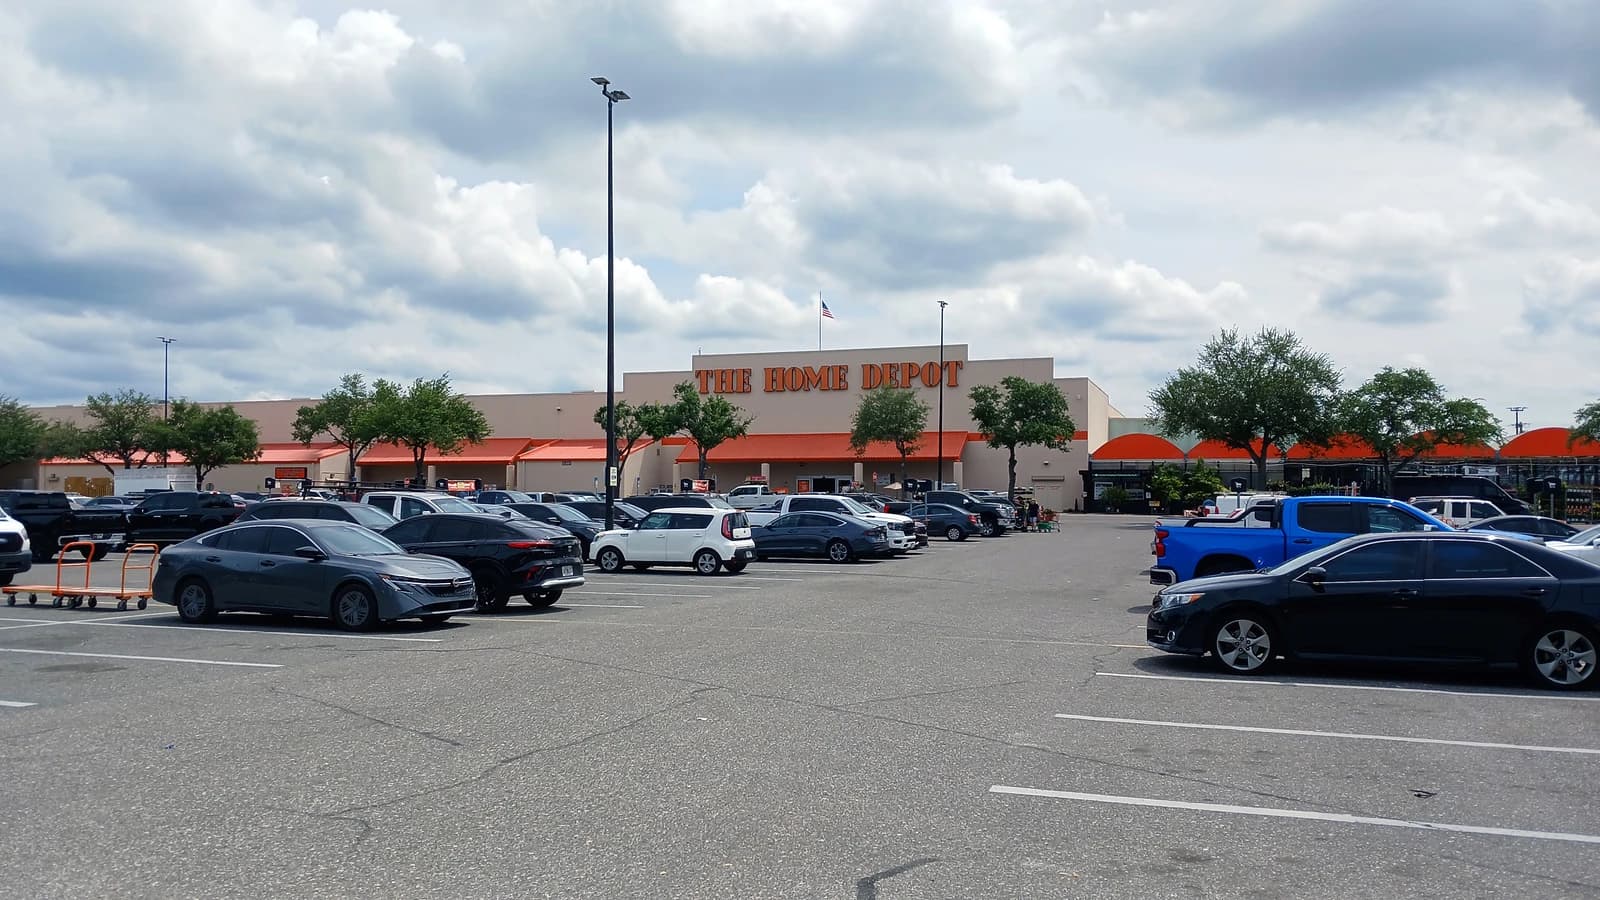
That matters because Home Depot’s latest results show the business is still holding up better than many peers even as the housing market stays frozen. Second-quarter revenue rose 5.7% to $47.86 billion, above estimates, and adjusted earnings of $4.92 a share topped expectations. Comparable sales increased 1.7%, accelerating to 2.3% in July, while management kept its full-year adjusted EPS outlook at flat to 4% growth.
The problem is not current demand so much as the lack of turnover in existing homes. Chief Financial Officer Richard McPhail said housing turnover has “never been lower as a percentage of the housing stock,” a headwind that limits big-ticket remodeling and postpones projects tied to moving, refinancing and home sales.
For investors, that makes Home Depot a levered play on a rebound in mortgage rates and transaction volumes rather than just a steady retail story. The stock is already down 5.7% over the past month and 13.5% year to date, even after a recent bounce, underscoring how sensitive shares are to the housing cycle.
The relative setup still favors Home Depot over some rivals. Lowe’s posted just 0.2% comparable sales growth in its latest quarter, while Floor & Decor fell 2.1%, highlighting Home Depot’s stronger same-store performance in a weak backdrop.
Technically, the stock has also repaired some of the damage from its selloff, with recent trading moving back above its 50-day moving average after severe oversold readings earlier in the year. But the next leg higher likely depends less on chart signals than on whether rates ease enough to revive home turnover.
If turnover climbs back toward the level McPhail cited as a historical inflection point, the bull case points to roughly $398. Until then, Home Depot remains a high-quality operator waiting for the housing market to thaw.
| Entity | Gains | Losses |
|---|---|---|
| Home Depot | ▲Higher sales from turnover rebound | ▼Slower remodel demand |
| Homeowners | ▲More home-sale and renovation activity | ▼Higher borrowing costs |
| Lowe’s | ▲Less if HD outperforms peers | ▼Share of weak DIY demand |
| Home Depot shareholders | ▲Upside if rates fall | ▼Stalled multiple expansion |