Humana has set the terms of its cash repurchase offers for selected debt securities, a move that points to an active liability-management strategy at a time when the insurer’s shares are trading near record highs and investors are scrutinizing how it deploys capital.
Humana sets terms for debt repurchase offer
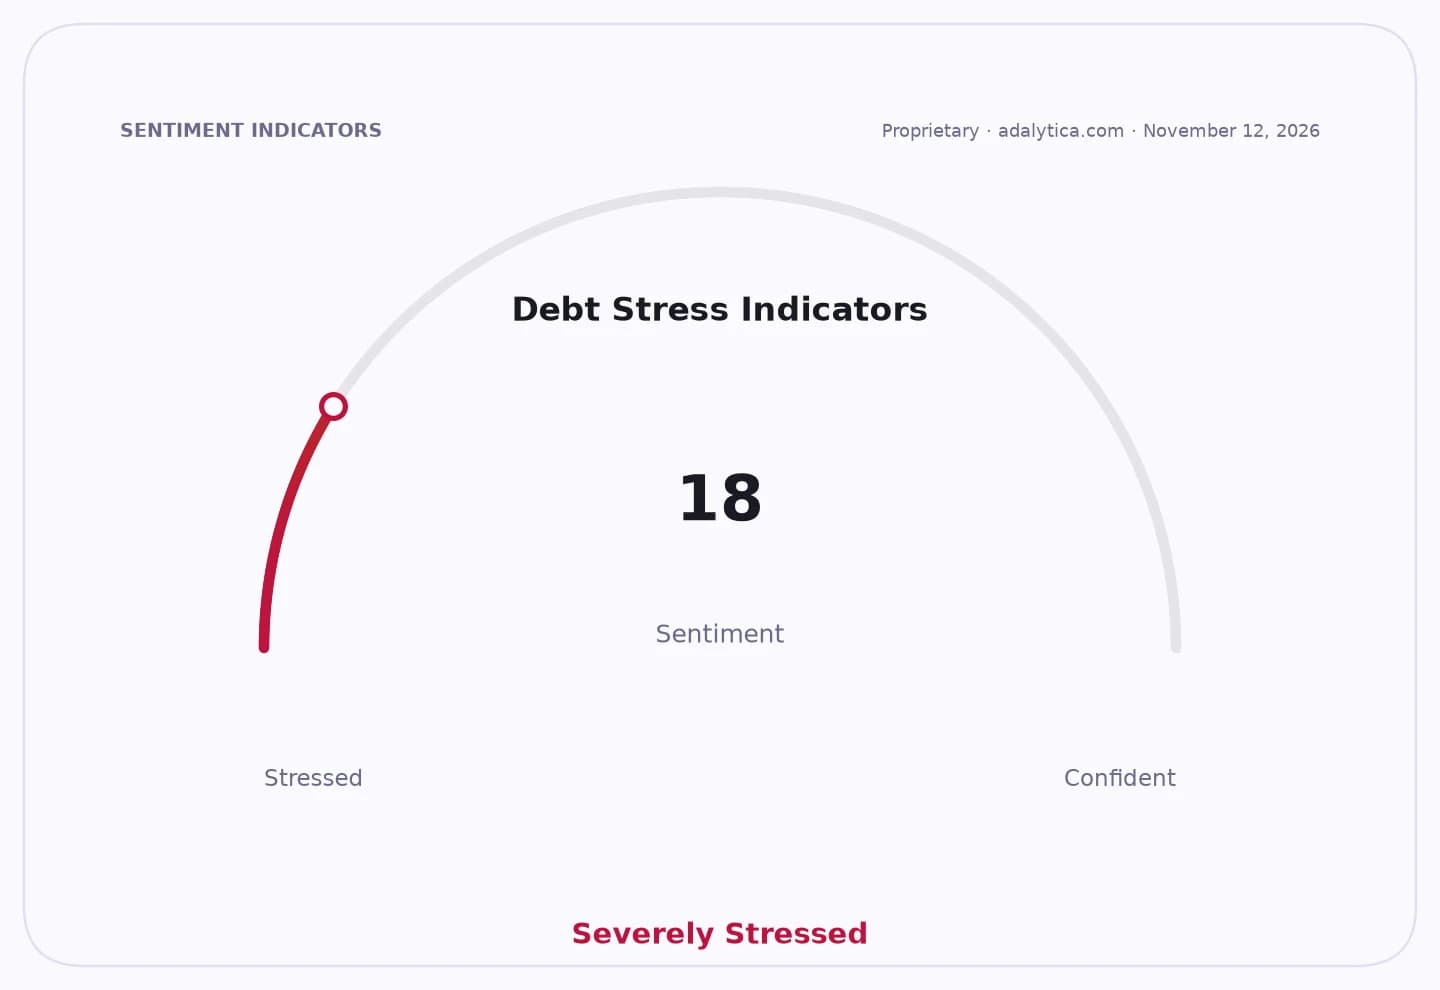
The offer matters because buying back debt can lower refinancing risk, reduce future interest expense and improve balance-sheet flexibility, especially for a managed-care company facing heavy operating demands and an uncertain credit backdrop. In a market where consumer debt is rising and lenders are tightening standards, companies with strong cash generation and access to liquidity are under pressure to be more deliberate about capital structure.
Humana disclosed the launch of the cash tender offer in a Nov. 9 filing, following a separate Nov. 6 earnings update. The company had also disclosed in its quarterly filing that it previously entered a Rule 10b5-1 repurchase plan tied to portions of its $750 million of 1.350% senior notes due February 2027 and $600 million of 3.950% senior notes due March 2027. That suggests the current transaction is part of a broader effort to manage near-term maturities rather than a one-off opportunistic buyback.
The timing is notable. Humana’s stock has climbed to 461.25, up sharply from 386.30 on Oct. 8 and 433.74 on Nov. 6, while trading above both its 50-day and 200-day moving averages. Momentum indicators are elevated, with RSI at 72.7, which typically indicates overbought conditions, but the price action also shows investor confidence in the company’s fundamentals and capital allocation.
For bondholders, the tender offer introduces a familiar trade-off: holders of the targeted notes may gain an exit at a defined price, while remaining creditors could benefit from a cleaner maturity schedule and potentially stronger credit metrics if Humana retires debt. For equity investors, the key question is whether the company is optimizing capital structure without overcommitting cash that could otherwise support operations, Medicare-related investment, or share repurchases.
The broader message is that large health insurers remain selective users of balance-sheet cash in a year when credit markets are watching leverage, refinancing and consumer stress more closely. If Humana follows through with a meaningful retirement of outstanding notes, it could modestly reduce financing costs and de-risk 2027 maturities. If the offer is small or priced aggressively, however, the market may read it as a limited capital return move rather than a material balance-sheet reset.
| Entity | Gains | Losses |
|---|---|---|
| Humana | ▲Lower refinancing risk | ▼Cash outflow |
| Tendered noteholders | ▲Exit at set price | ▼Lose coupon stream |
| Remaining bondholders | ▲Cleaner maturity profile | ▼Less cash on balance sheet |
| Equity holders | ▲Potentially stronger capital structure | ▼Less capital for other uses |