Italian equities extended their advance as banks and defense names drew buyers, with UniCredit’s move higher after the European Central Bank cleared its path to controlling Commerzbank giving the market the clearest signal that consolidation in European finance is still alive.
Italian Banks Rise After UniCredit Commerzbank Move
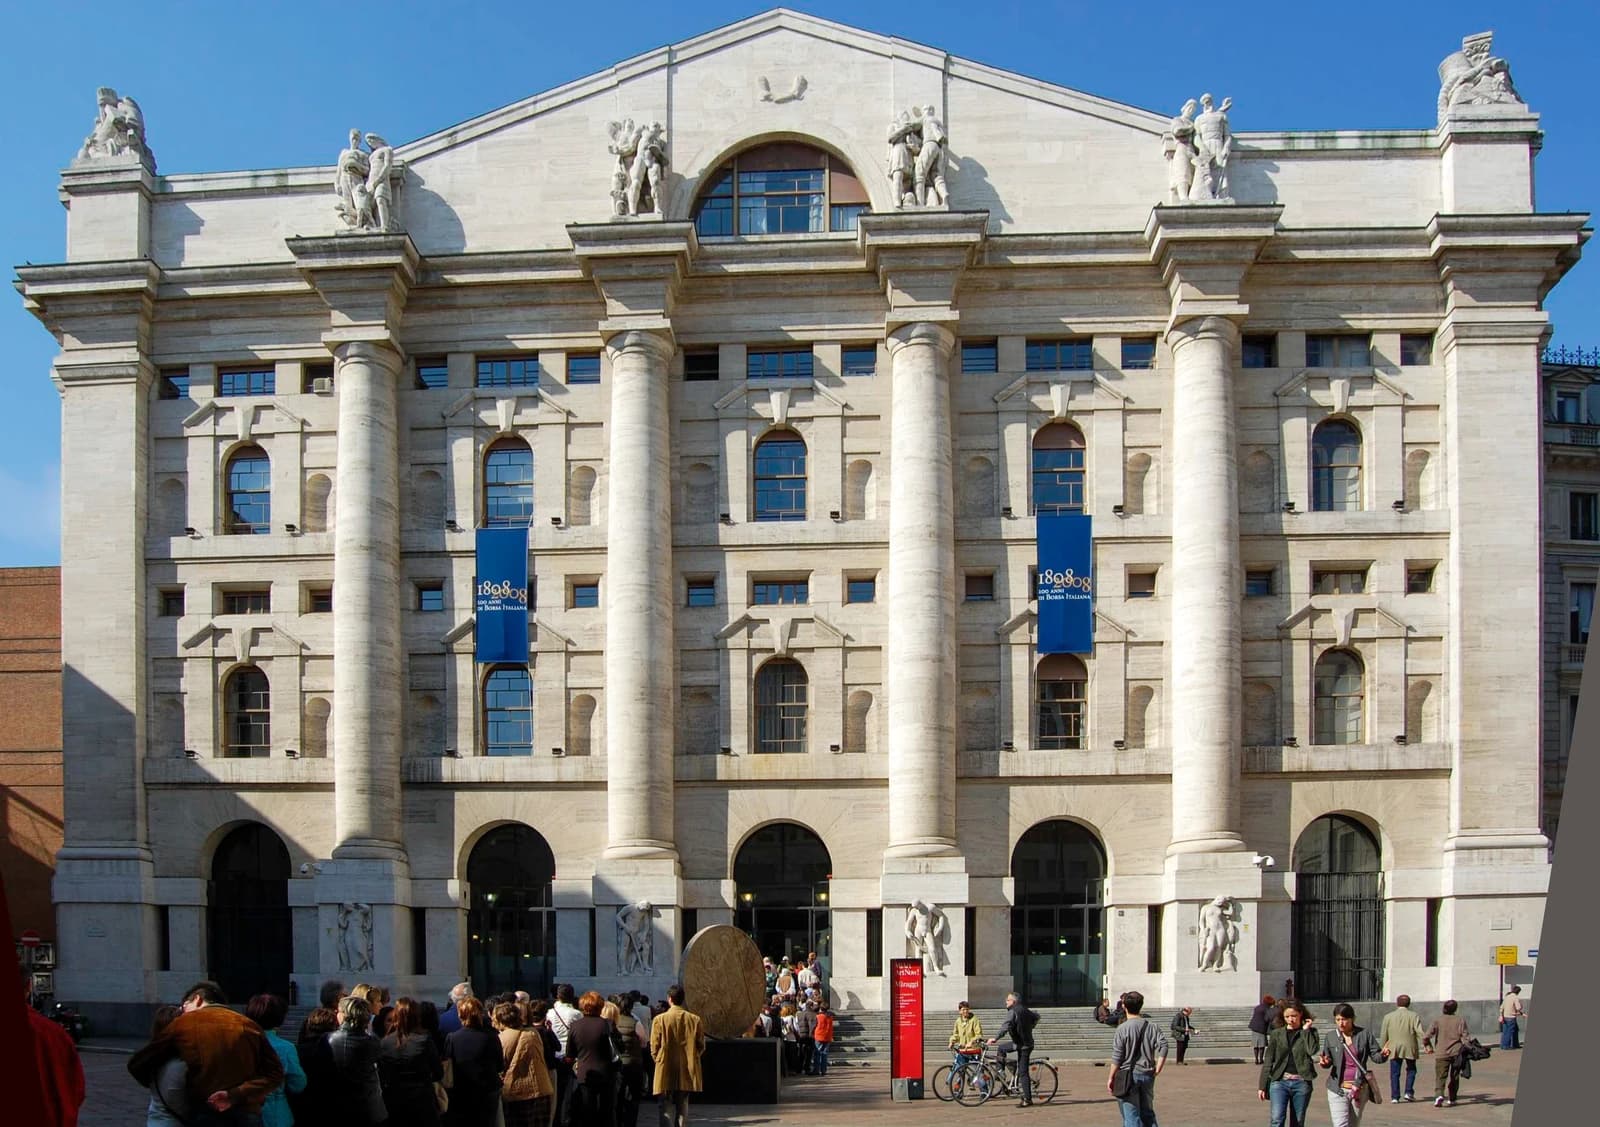
That matters because the Italian market is still trading as a leveraged play on rates, capital returns and cross-border banking power. A firmer bank bid helps anchor the FTSE MIB even as higher sovereign yields keep pressure on rate-sensitive assets, with the Btp-Bund spread at 107 basis points and the Italian 10-year yield at 4.47%. For investors, that combination says the market is willing to look through Italy’s financing costs as long as banks can keep generating capital and deploying it through dividends, buybacks and dealmaking.
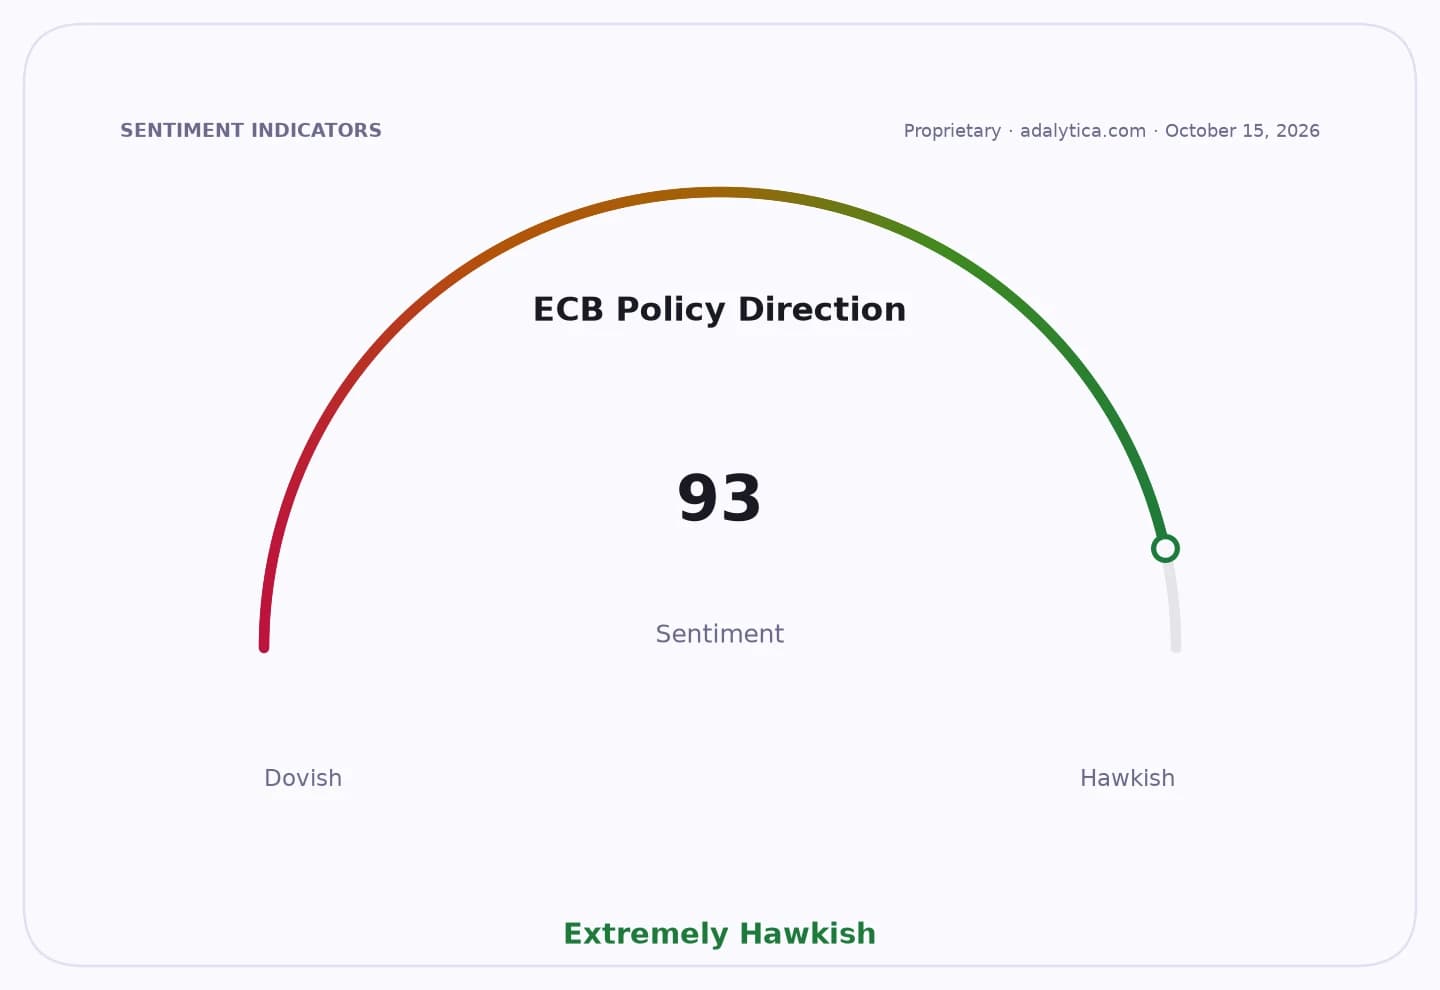
Sentiment IndicatorsⓘProprietary · adalytica.com · October 18, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
UniCredit rose about 1%, while Intesa Sanpaolo, Monte dei Paschi, Bper and Banco Bpm also traded higher. The move underscores how bank stocks remain the backbone of Milan’s rally, and why the sector is still where the fastest money is made when the macro backdrop stabilizes even modestly. A solid yield environment, if it does not become disorderly, supports net interest income and keeps lenders in the hunt for shareholder distributions.
The day’s strength was not limited to financials. Brunello Cucinelli climbed 2.5% after posting nine-month growth and lifting its 2026 estimates, a sign that premium consumer demand is still intact despite a more cautious European growth backdrop. That is important for the broader Milan tape because it shows investors are still rewarding companies with pricing power and visible earnings momentum, even as the market digests a less forgiving bond backdrop.
Defense names also attracted interest, with Fincantieri, Avio and Leonardo each up 2.5%. In a market where capital is increasingly rotating toward defense, infrastructure and strategic industrial capacity, that bid is another reminder that Europe’s security spending cycle is becoming an investable theme, not just a policy talking point.
On the other side of the ledger, STMicroelectronics slipped again, while Technoprobe and Eni were slightly weaker. STM’s underperformance stands out because it contrasts with the stronger bank-led market and highlights how cyclicals tied to semiconductors remain vulnerable when investors prefer cash-generative financials and defense-linked industrials.
The setup for Milan remains straightforward: if sovereign spreads stay contained and banks keep getting regulatory and strategic green lights, the market has room to keep outperforming. The trade here is not broad beta, but selective exposure to institutions with capital strength, deal optionality and the ability to turn a still-high-rate regime into shareholder returns.
| Entity | Gains | Losses |
|---|---|---|
| Italian banks | ▲Higher prices, deal optionality | ▼None material today |
| UniCredit | ▲ECB approval on Commerzbank control | ▼Integration scrutiny |
| Brunello Cucinelli | ▲Stronger sales outlook | ▼None material today |
| STMicroelectronics | ▲— | ▼Weak sector sentiment |