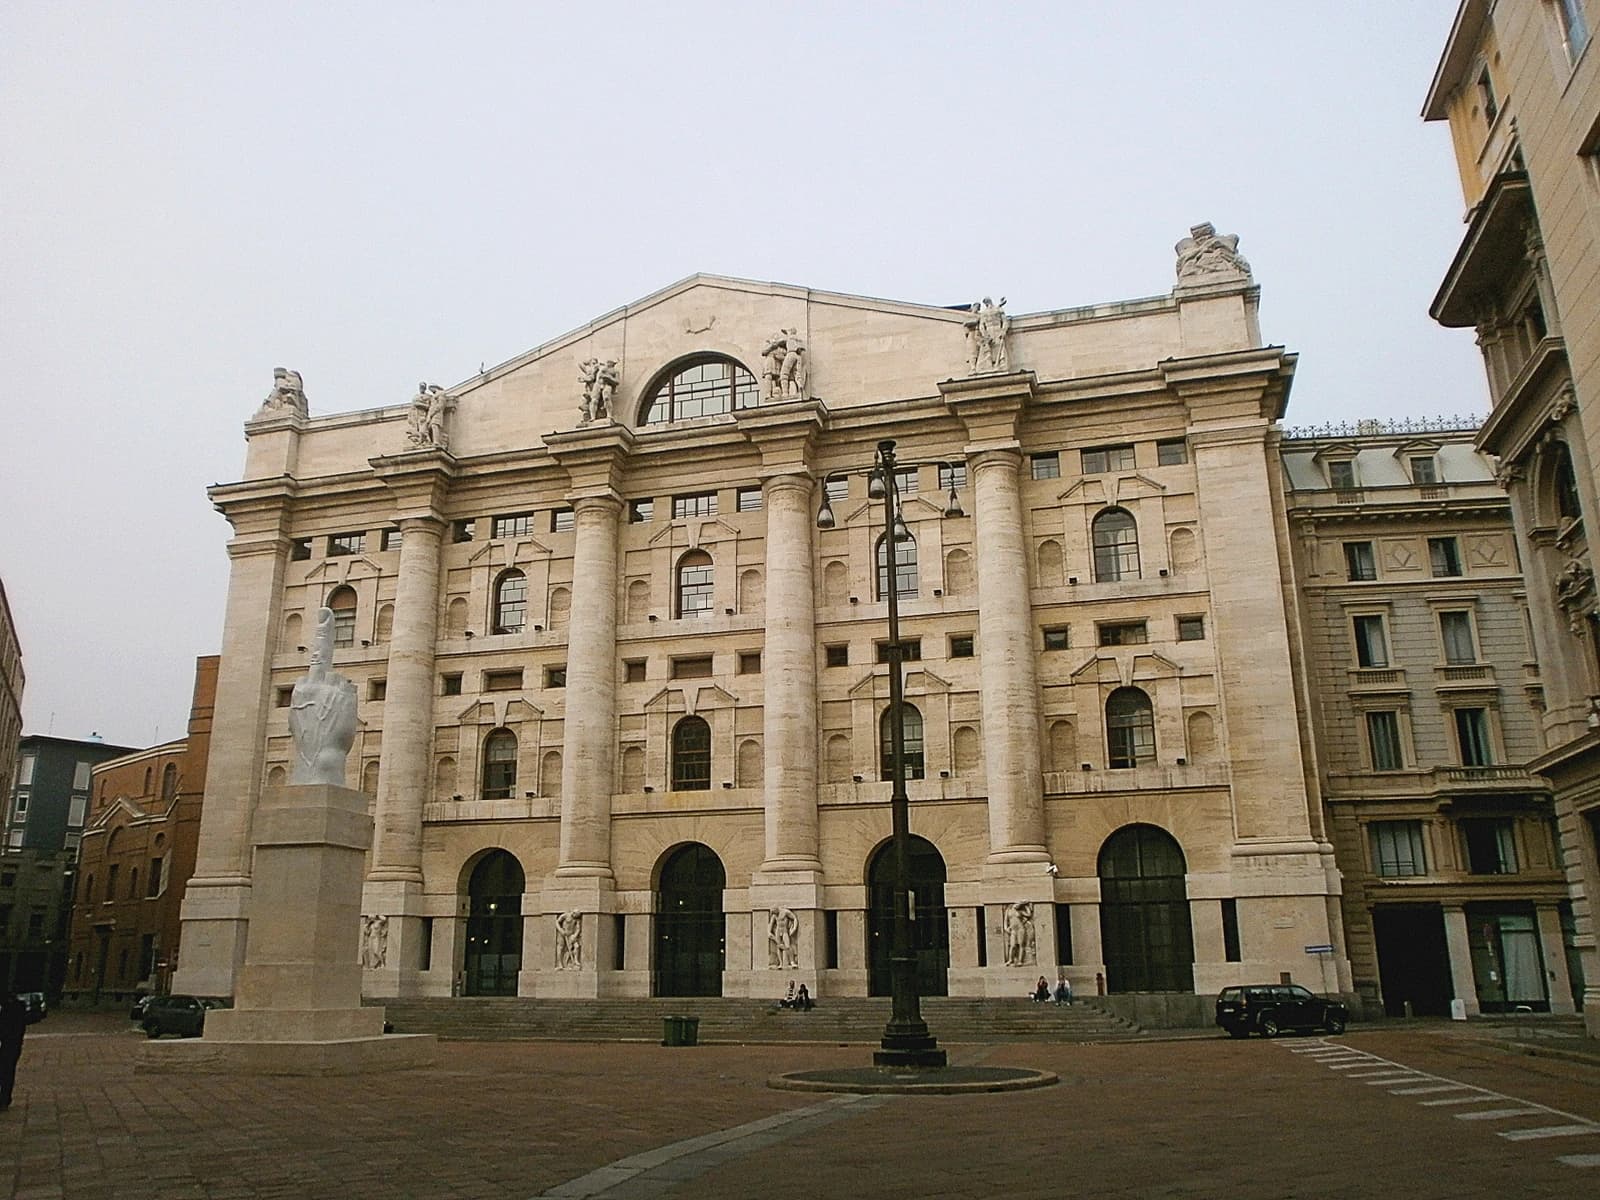
Italy’s productivity gap with Europe is being driven less by weak large companies than by the country’s persistent reliance on microbusinesses, according to data discussed at a Business Forum in Milan that recasts corporate growth as an economic necessity rather than a strategic choice.
Italy microbusinesses drag productivity, forum data says
That matters because raising the average size of Italian firms would mechanically lift output per worker, improve wage capacity and strengthen the industrial base at a time when companies face heavier demands from digitalization, sustainability, geopolitics and the race for talent. In other words, the issue is not that Italian firms cannot compete at scale — many already do — but that too much of the economy remains stuck in the smallest size bracket.
Sentiment Indicators
The data cited by Gea chairman Tito Zavanella show Italy averaging about 64,000 euros of value added per employee, below larger European peers and the EU mean. But the picture changes sharply by company size. Firms with more than 50 employees are highly productive, and Italian companies in the 10-to-49 employee range even outperform Germany. The drag comes from businesses with up to nine workers, where productivity trails benchmark economies.
That composition effect is economically important because microenterprises account for a disproportionate share of value added and employment in Italy compared with Germany. Zavanella argued that if Italy’s average firm size matched Germany’s, national productivity would rise by 17%, enough to move above France, Germany and the EU average. For policymakers, that implies the challenge is not simply to protect existing firms, but to create conditions for consolidation, investment and scaling.
For investors, the message is that Italy’s equity market and industrial economy may have more hidden quality than headline productivity figures suggest. The country’s larger industrial companies are not the problem; they are often globally competitive. The opportunity lies in identifying businesses able to expand through acquisitions, automation and export-led growth, while the risk sits with smaller domestic firms that may struggle to finance the transition.
The broader narrative is shifting from size as a byproduct of success to size as a prerequisite for survival. As costs rise and competitive pressures intensify, Italy’s next productivity sprint will likely depend on whether policy and capital can push more companies out of the micro category and into a scale where innovation, financing and talent attraction become self-reinforcing.
| Entity | Gains | Losses |
|---|---|---|
| Large Italian manufacturers | ▲Higher productivity profile | ▼Little, if growth is sustained |
| Microenterprises | ▲Access to scale benefits | ▼Continued weakness in output per worker |
| Investors in scalable industrials | ▲Better earnings potential | ▼Firms unable to adapt |
| Italian economy overall | ▲Higher productivity and wages | ▼Delay in structural reform |