Kenya’s tax authority has kept the benchmark rate for fringe benefits and deemed interest at 9% through the final quarter of 2026, a move that matters because it keeps the cost of staff loans and other non-cash perks firmly on employers’ radar.
Kenya keeps fringe benefits rate at 9% through 2026
For businesses, the key issue is not the headline rate itself but the compliance burden that comes with it. Under Kenya Revenue Authority rules, any employer lending staff, directors or related parties below the 9% benchmark faces a tax charge on the benefit. That tax is due by the 9th day of the following month, and a separate 15% withholding tax applies to deemed interest, payable within five working days of deduction.
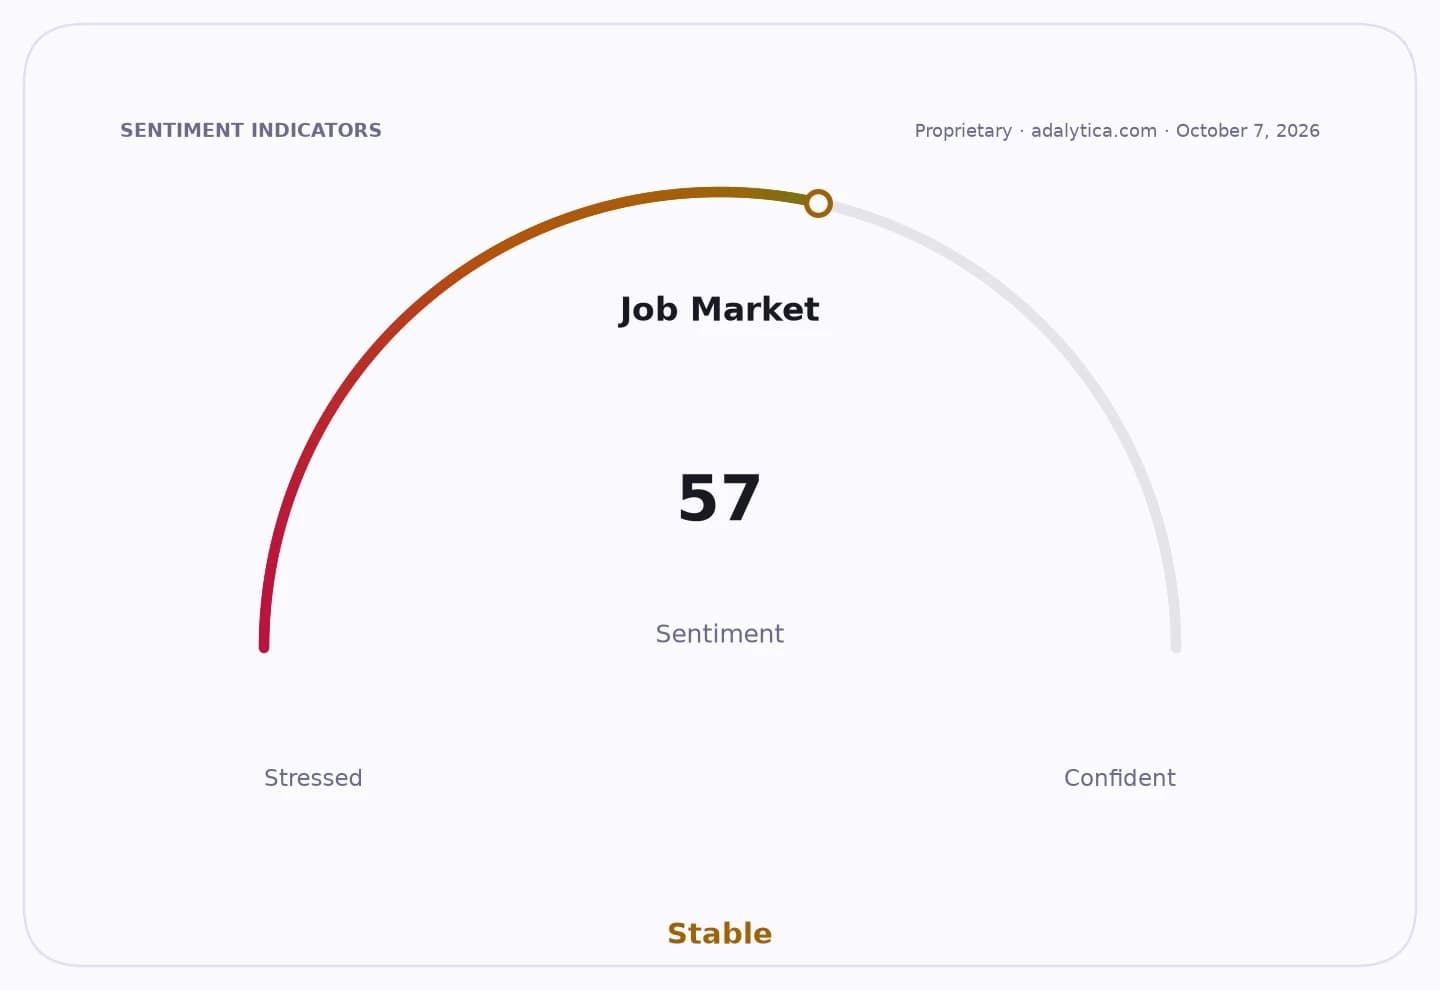
Sentiment Indicators
That makes this a cash-flow and payroll issue as much as a tax issue. In practical terms, companies that have used low-interest employee loans as a retention tool will need to review those arrangements quickly, especially if they have multiple borrowers or benefit-heavy compensation packages. The authority’s reminder also covers non-cash perks such as company cars and housing, which broadens the compliance net beyond loan programs.
For investors, the story is about margins, discipline and how companies structure pay. Any business with a meaningful employee-loan book or generous fringe benefits could see higher administrative costs and, in some cases, a direct hit to operating expenses if the tax is not managed efficiently. That is especially relevant in sectors where payroll incentives are used to attract and retain talent, because tax changes can quietly erode the economics of those programs.
The bigger narrative is that Kenya is keeping pressure on employers to formalize compensation and remit taxes promptly, even as governments elsewhere weigh tax relief to support growth. That can be a drag on firms that rely on flexible perks, but it also favors companies with strong compliance systems and conservative balance sheets. Over the long run, investors should watch which businesses can absorb tighter tax rules without letting employee costs spiral. For now, it is a reminder that tax policy can change the real cost of doing business as much as any wage increase.
| Entity | Gains | Losses |
|---|---|---|
| KRA | ▲Faster compliance revenue | ▼Less unpaid tax leakage |
| Employers | ▲Clarity on 2026 rules | ▼Higher tax and admin burden |
| Employees/directors with loans | ▲Continued access to financing perks | ▼Less value from low-rate loans |
| Investors in payroll-heavy firms | ▲Better visibility on costs | ▼Margin pressure if benefits are generous |