Kotak Mahindra Bank shares climbed more than 4% after the lender reported strong September-quarter business updates, with advances and deposits both growing at a pace that points to healthy credit demand and steady funding momentum.
Kotak Mahindra Bank shares rise on Q2 business update
The market’s reaction matters because for Indian banks, top-line loan growth and deposit mobilisation are the clearest near-term indicators of earnings durability. Kotak said net advances rose 24.7% year on year to Rs 5.77 lakh crore as of September 30, while total deposits increased 23.2% to Rs 6.51 lakh crore. That mix suggests the bank is still expanding its balance sheet without a visible funding strain, a combination that typically supports net interest income and market confidence.
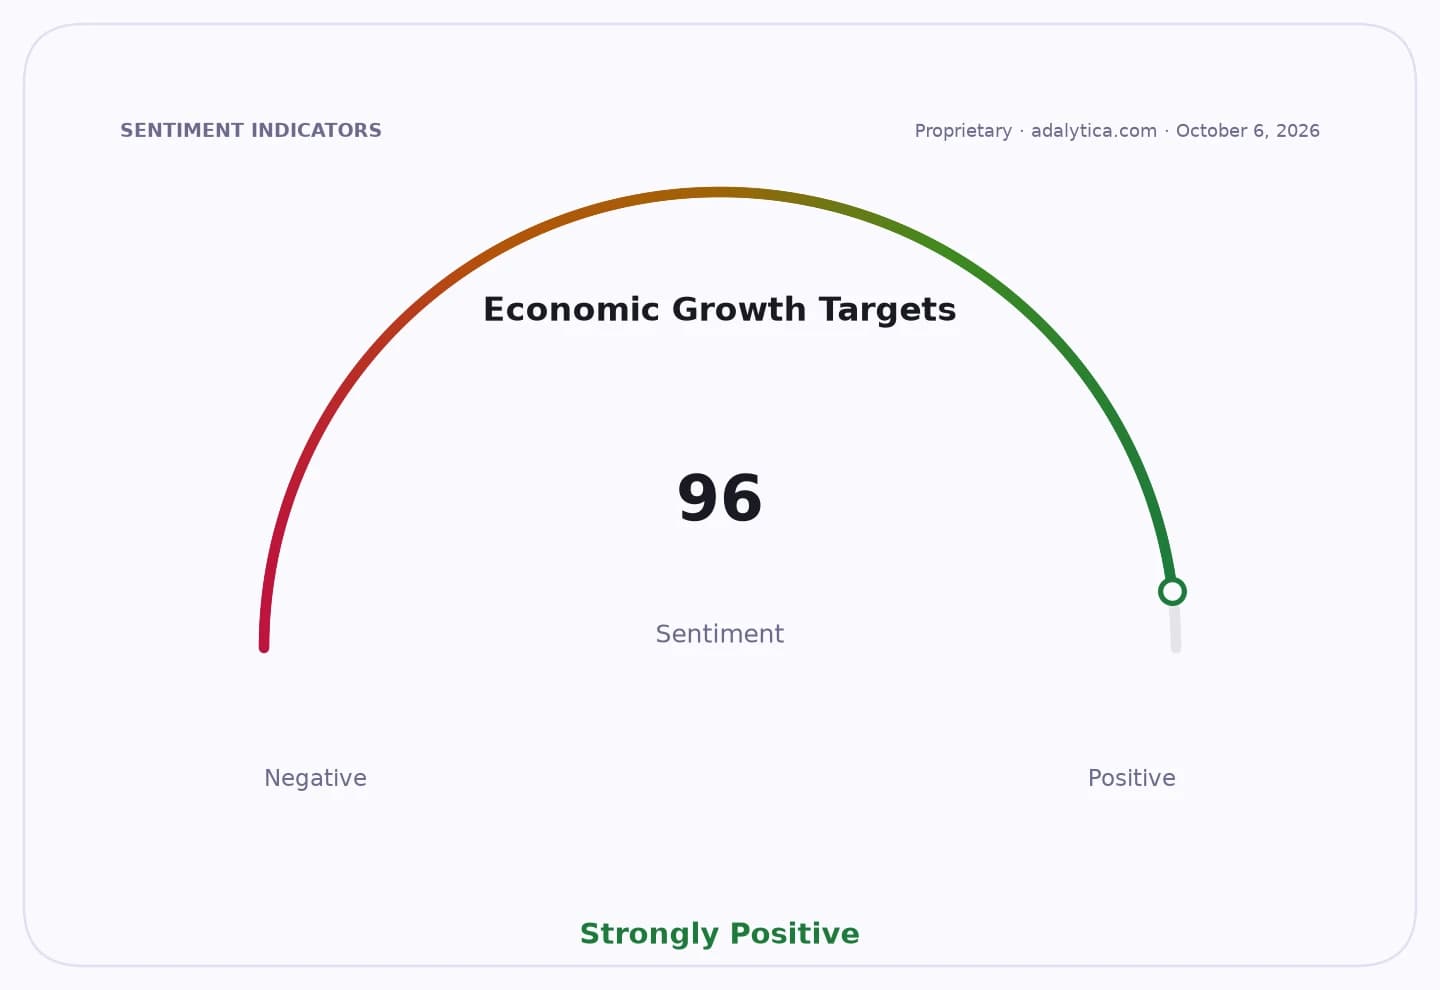
Sentiment IndicatorsⓘProprietary · adalytica.com · October 6, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The pace was also strong sequentially. Net advances rose 12.7% from Rs 5.12 lakh crore at the end of June, while average net advances were up 22.1% from a year earlier and 10.5% from the previous quarter. CASA deposits, a key low-cost funding source, increased 11.3% to Rs 2.49 lakh crore. In an environment where deposit competition across the banking system has often been intense, that is an important sign that Kotak is still able to attract and retain core liabilities.
The bank also disclosed $5.78 billion, or about Rs 55,344 crore, in FCNR(B) deposits under the Reserve Bank of India’s swap facility, with $1.68 billion of corresponding advances held by its international branches. While these flows can be more technical than retail deposits, they matter because they affect liquidity, foreign currency funding and the bank’s ability to support overseas lending without excessive cost.
For investors, the update strengthens the case that Kotak is benefiting from the broader Indian credit cycle while avoiding the deposit pressure that has weighed on some peers. The shares’ rally reflects optimism that faster loan growth can support earnings momentum, and that the lender’s franchise remains strong enough to sustain balance-sheet expansion. Goldman Sachs’ view on the stock will likely be read against that backdrop, with investors focused on whether the brokerage sees room for further upside after the post-update move.
There are still two sides to the story. The bull case is that Kotak is regaining growth momentum after a period in which the bank was watched closely for execution and regulatory overhangs. The bear case is that rapid asset growth can become harder to sustain if deposit competition intensifies or if margins come under pressure as funding costs remain elevated. What matters next is whether the September-quarter business update translates into cleaner earnings delivery and whether deposit growth keeps pace with loans into the year-end.
| Entity | Gains | Losses |
|---|---|---|
| Kotak Mahindra Bank | ▲Faster loan and deposit growth | ▼Scrutiny on margins and funding costs |
| Equity investors | ▲Re-rating on growth momentum | ▼Risk of profit-taking after rally |
| Competitor banks | ▲Benchmark pressure to match growth | ▼Relative share when Kotak outperforms |
| Depositors/funding markets | ▲Stronger franchise confidence | ▼Higher competition for deposits |