MEFIC REIT is buying time on two of its most important asset-growth plans while walking away from a third, in a move that underscores both the opportunity and the discipline facing Saudi real estate funds.
MEFIC REIT extends Jeddah and Mecca deal deadlines
The fund manager, Mefic Capital, said it has extended the completion deadline for property acquisitions in Jeddah and Mecca to Nov. 30, 2026, after both deals were amended this week. At the same time, it declined to renew a memorandum of understanding for a potential usufruct acquisition in Jazan, effectively ending that transaction for now because the parties did not reach final terms acceptable to the fund.
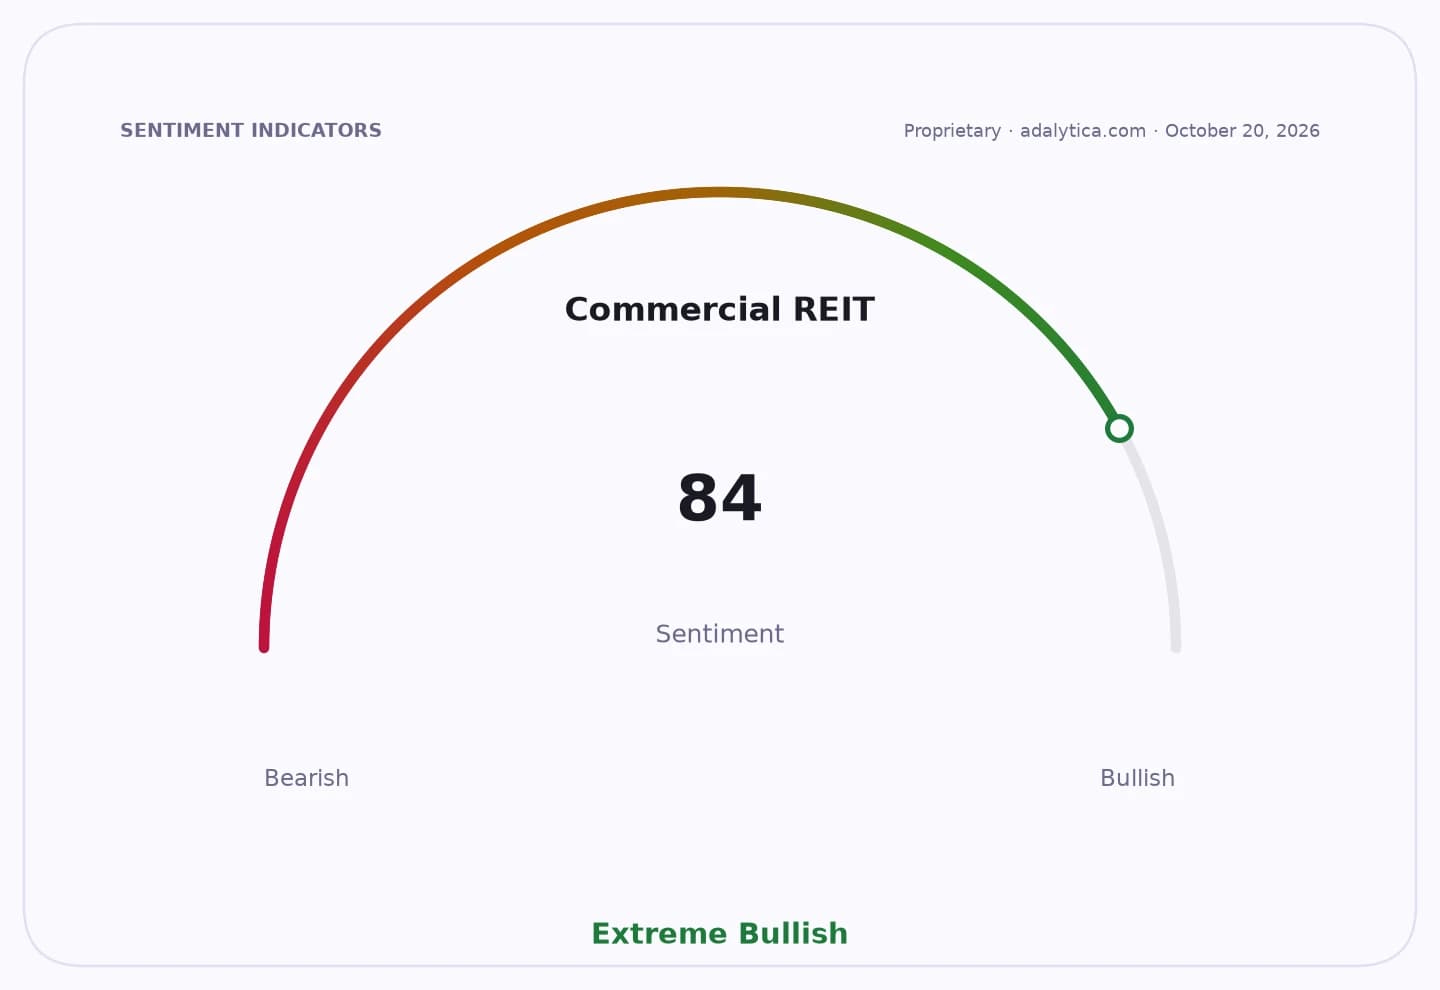
Sentiment Indicators
For investors, the key issue is not the paperwork itself but what it says about execution risk in a market where growth depends on completing asset deals that can lift net asset value and enlarge the income base. REITs are judged on their ability to turn announced acquisitions into cash-generating properties, and delays can push out expected yield accretion even when the underlying strategy remains intact.
MEFIC Capital said completing the acquisitions and increasing the fund’s total asset value should support overall performance and help meet its investment targets. That is the core bull case for REIT buyers in Saudi Arabia: scale, portfolio diversification and stronger recurring rental income. But the benefit only arrives if the manager secures the approvals, closes the transactions and integrates the assets into the portfolio.
The Jeddah and Mecca extensions suggest the manager still sees value in the assets and is willing to give the deals more runway, likely to satisfy regulatory or transfer requirements tied to ownership change. Mecca remains especially strategic given its exposure to pilgrimage-related demand, while Jeddah offers liquidity and urban rental depth. Those are the kinds of locations that can materially improve a REIT’s profile if bought on sensible terms.
The Jazan decision is just as important. By stepping away from the memorandum rather than forcing a weak transaction through, MEFIC is signaling capital discipline at a time when investors are rewarding managers that preserve returns instead of chasing growth for its own sake. In a market increasingly focused on quality of income, that kind of restraint matters.
The next catalyst is regulatory and shareholder approval. The fund said any capital increase or asset-value expansion still depends on sign-off from the Saudi Capital Market Authority, Saudi Exchange and unit holders. If those hurdles are cleared and the Jeddah and Mecca acquisitions close by the new deadline, the stock’s investment case shifts from a story of announced growth to one of realized accretion. If not, the market will likely keep discounting execution delays.
| Entity | Gains | Losses |
|---|---|---|
| MEFIC REIT | ▲More time to close deals | ▼Near-term growth visibility |
| Jeddah and Mecca assets | ▲Higher chance of acquisition | ▼Delay in transfer/monetization |
| Jazan opportunity | ▲Capital discipline | ▼Potential portfolio expansion |
| Existing unit holders | ▲Better odds of accretive assets | ▼Uncertainty over timing |