Mortgage gift letters are back in focus as elevated home prices and tight affordability keep more first-time buyers leaning on family cash to close, even as the broader housing market cools from its pandemic-era surge.
U.S. mortgage gift letters stay in focus

The need is clearest in the latest housing data: U.S. home sales are projected to run at an annualized 1.2785 million in September, barely changed from August’s 1.275 million, while the S&P CoreLogic Case-Shiller index shows home prices still up sharply from pre-pandemic levels. The combination leaves many buyers short on savings and pushes lenders to scrutinize gift letters more closely to confirm that down payment money is a true gift, not a hidden loan.
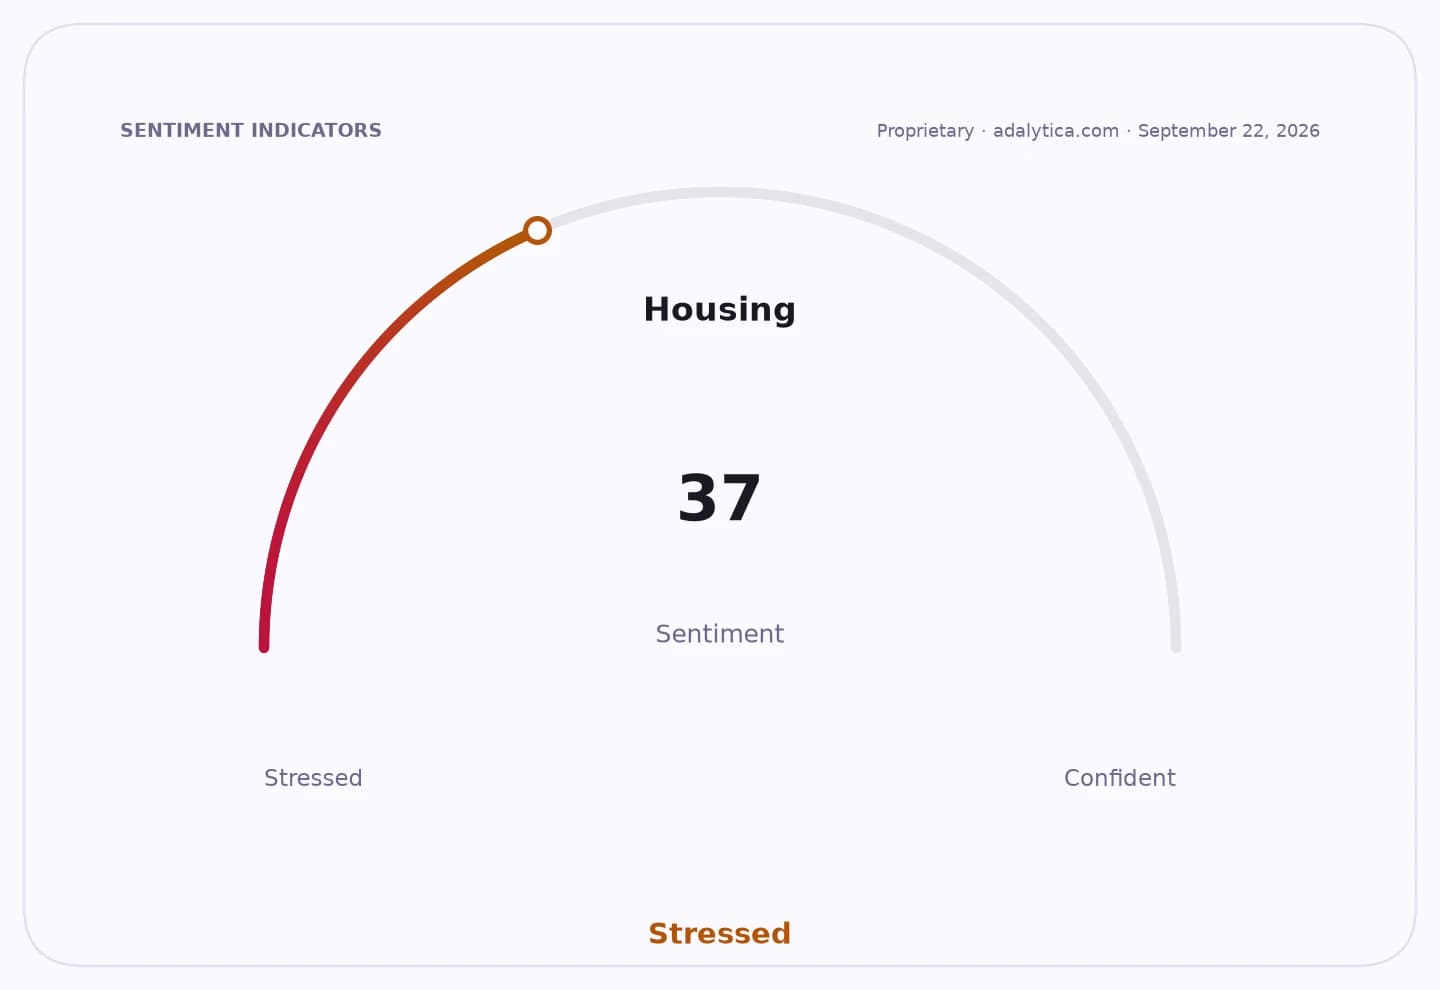
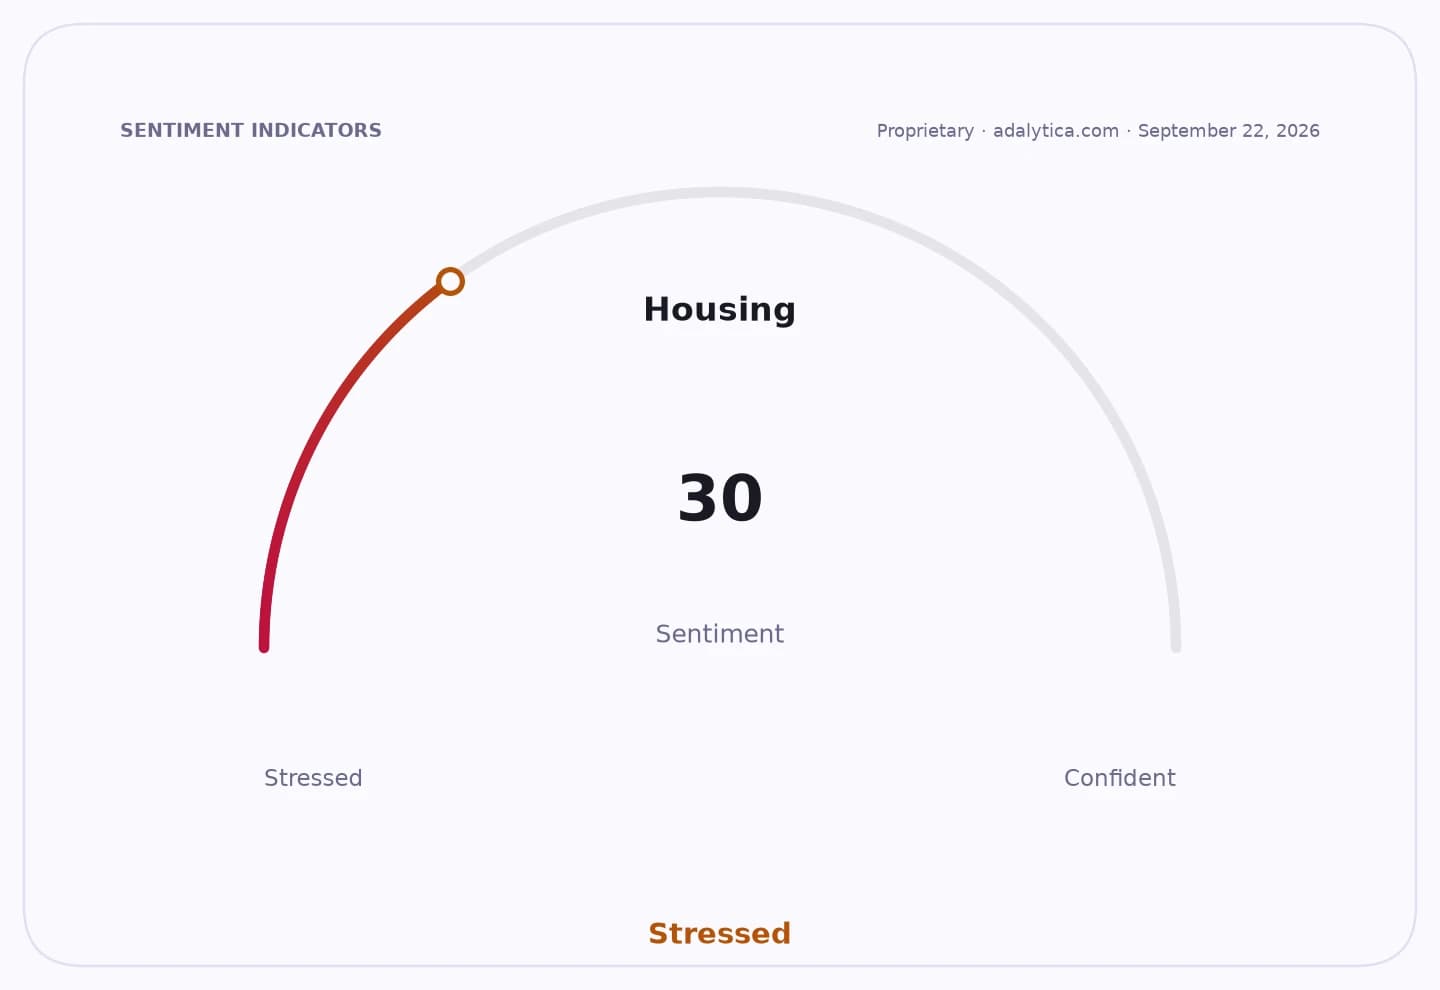
Sentiment IndicatorsⓘProprietary · adalytica.com · September 23, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That matters because gift funds can be the difference between getting approved and being priced out. For borrowers, properly documented family assistance can lower the upfront cash hurdle, while for lenders it reduces the risk that a buyer is stretching beyond their means with borrowed money that will later strain repayment.
The backdrop is a labor market that remains relatively stable, with the unemployment rate forecast to ease to 4.02% in September from 4.1% in August. That points to a housing market that is not being driven by distress, but by affordability pressure and scarce inventory, two forces that keep down payments a central issue for mortgage originators.
Publicly traded mortgage names such as Rocket Companies and UWM Holdings, along with landlord-focused REIT Invitation Homes, remain tied to that affordability dynamic. Rocket’s shares were at $12.15 on Sept. 23, below both its 50-day and 200-day moving averages, while UWM closed at $1.22 and Invitation Homes at $26.93, reflecting a market still sensitive to mortgage-volume and housing-demand trends.
Adalytica’s Housing and Rent Inflation Sentiment gauge was at “Extreme Fear” on Sept. 23, underscoring how stretched consumers still feel even after the latest housing run-up slowed. For investors, that means mortgage activity is likely to stay dependent on affordability workarounds such as family gifts, government-backed loan programs and rate relief, rather than a clean demand rebound.
The next catalyst is September housing and labor data, which will show whether easing price pressure and a softer mortgage-rate backdrop are enough to revive purchase demand — and how much more families will need to fill the down payment gap.
| Entity | Gains | Losses |
|---|---|---|
| Homebuyers using gift funds | ▲Easier path to approval | ▼Greater lender scrutiny |
| Mortgage lenders | ▲Cleaner documentation | ▼More compliance checks |
| Home sellers | ▲More qualified buyers | ▼Fewer all-cash bids |
| Rocket Companies / UWM Holdings | ▲Potential purchase-loan volume | ▼Margin pressure from thin affordability |