Oil prices cooled even as US bond yields jumped sharply, a combination that signals markets are shifting from geopolitics toward the possibility of tighter-for-longer monetary policy and a larger supply response from Saudi Arabia.
Oil Prices Fall as US 2-Year Yield Rises
That matters because the move in rates is now the bigger macro force. The US 2-year Treasury yield climbed 36 basis points to 4.7604%, the highest since mid-2024, after last week’s hawkish Federal Reserve rhetoric pushed traders to price in a 56% chance of another rate hike in October and almost a full additional increase before year-end. When front-end yields surge like that, the cost of capital rises quickly across equities, credit and commodities, and the market’s appetite for duration-sensitive assets weakens.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 24, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Oil’s retreat suggests investors are not treating Middle East risk as enough, on its own, to keep crude elevated. Prices eased as expectations grew that Saudi Arabia could increase supply, offsetting fears triggered by a Houthi attack on Riyadh. Commonwealth Bank of Australia said the closure of the East-West pipeline has materially tightened the market and cut its estimate of how long global oil and refined-product inventories can last to just five to 10 weeks, down from 15 to 20 weeks two weeks ago. That is a stark reminder that the market remains vulnerable to any disruption around the Strait of Hormuz or Bab el-Mandeb, even if near-term price action is softening.
For investors, the setup is more interesting than the headline suggests. Higher Treasury yields are pressuring long-duration assets, including gold, which slipped 0.2% to $4,370 an ounce, while oil’s volatility keeps energy equities and commodity-linked trades in play. The 2-year yield at 4.76% also reinforces the case for staying selective in rate-sensitive sectors and favoring businesses that can pass through higher financing costs or benefit from tighter supply chains and defense-driven geopolitical spending.
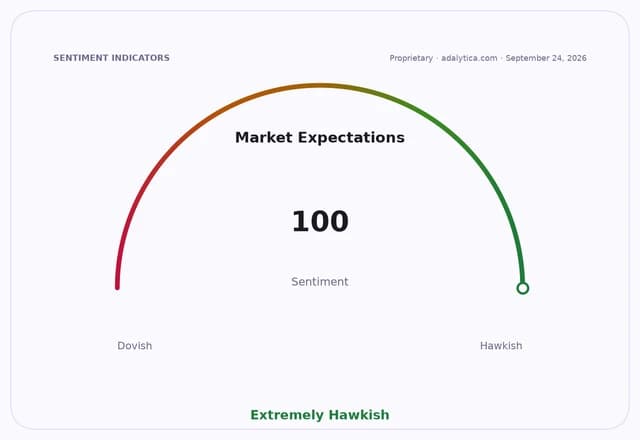
The broader narrative is that inflation and geopolitics are colliding again, but markets are increasingly pricing the Fed as the dominant swing factor. If yields keep rising while oil stays supported by supply risk, investors may be facing a late-cycle regime where cash flows and pricing power matter more than multiple expansion. I believe that argues for staying positioned in energy infrastructure, defense and cash-generative value names, while being cautious on rate-sensitive growth until bond markets settle.
| Entity | Gains | Losses |
|---|---|---|
| US Treasury bears | ▲Higher front-end yields | ▼Bond prices |
| Energy producers | ▲Tighter supply backdrop | ▼Oil consumers |
| Gold bulls | ▲Higher inflation fear | ▼Non-yielding bullion |
| Rate-sensitive growth stocks | ▲Selective capital rotation | ▼Higher discount rates |