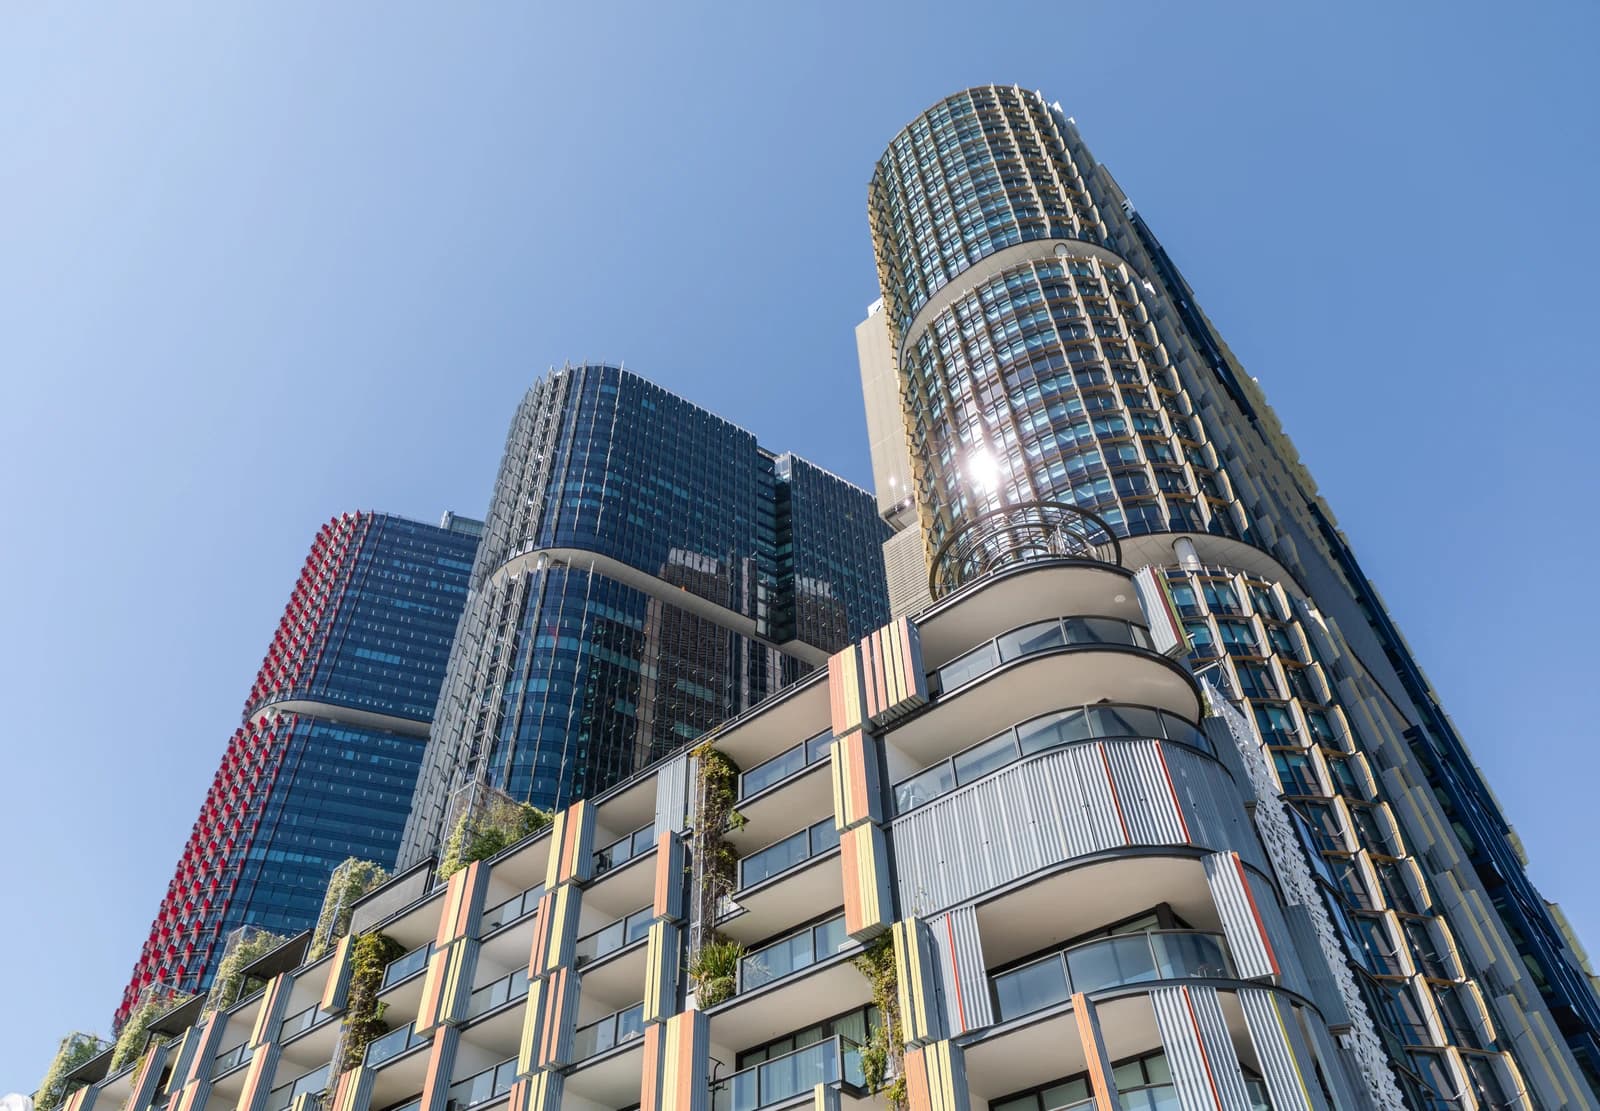
OUE REIT is deepening its bet on Sydney’s office market, agreeing to buy an additional roughly 50% stake in 180 George Street for A$864.0 million and lifting its holding in the tower to about 69.9% once the deal closes.
OUE REIT Buys More of 180 George Street
The transaction matters because it gives the Singapore-listed trust control of a landmark freehold asset in one of Australia’s most sought-after office precincts at a price that the manager says is 3.7% below the valuation implied by the 19.9% stake it bought in March. The manager also says the deal should be 3.2% accretive to distribution per unit on a pro forma basis, making it one of the clearer cash-flow drivers in OUE REIT’s ongoing portfolio reshaping.
Sentiment Indicators
Investors are likely to focus on the financing and leverage implications as much as the asset itself. The estimated total acquisition cost is A$539.3 million, to be funded with debt and proceeds from the divestment of Crowne Plaza Changi Airport, while aggregate leverage is expected to rise temporarily to 45.3% before potentially easing to about 42.8% if the trust issues up to S$150 million of perpetual securities.
180 George Street, also known as Salesforce Tower, is already fully occupied and carries a 5.2-year weighted average lease expiry by net lettable area, backed by tenants including Salesforce, TikTok and Jones Lang LaSalle. For OUE REIT, that mix offers durable rent visibility at a time when premium office demand in gateway cities is proving more resilient than the broader commercial property market.
The acquisition also extends OUE REIT’s geographic shift away from a Singapore-heavy portfolio. After completion, Australia’s share of assets is expected to rise to 17.6% from 5.7% on an enlarged portfolio basis, underscoring the trust’s move to recycle capital from a hotel divestment into a higher-quality office platform with more control over asset strategy.
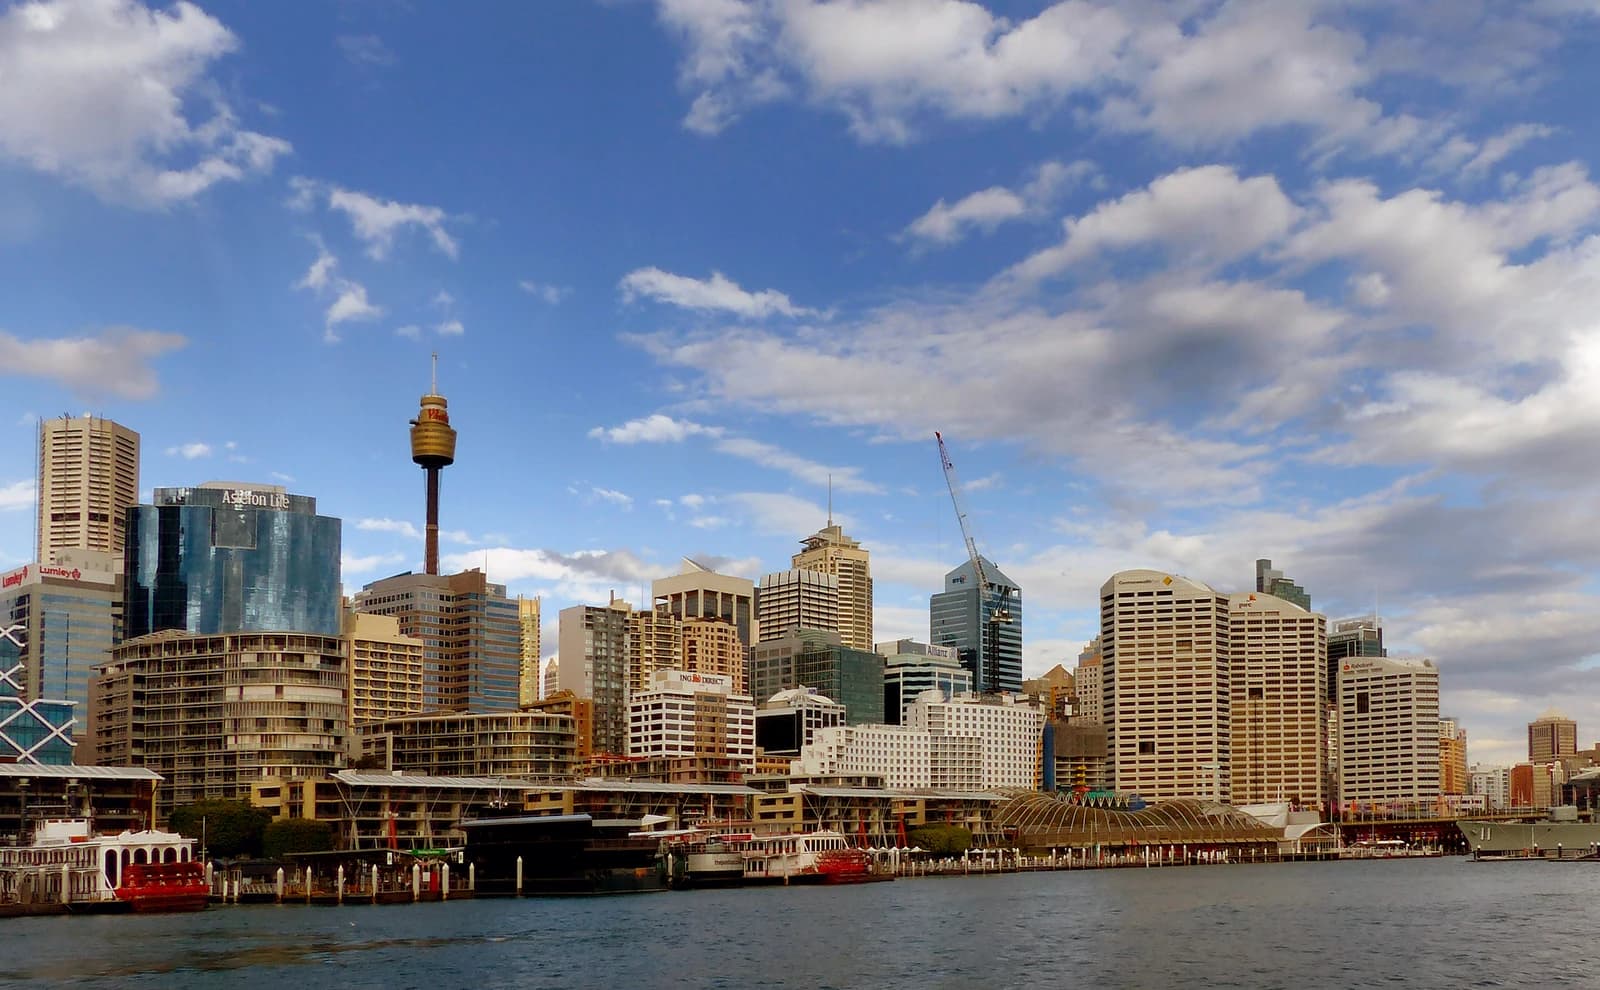
For the market, the deal is a test of whether Singapore REITs can still create value by buying dominant office assets offshore even as financing costs remain elevated. Sydney’s prime office market, strong tenant roster and the building’s sustainability credentials should help support the thesis, but the next focus will be execution: completion of the acquisition, the Crowne Plaza sale and whether OUE REIT can keep leverage in check while preserving distribution growth.
| Entity | Gains | Losses |
|---|---|---|
| OUE REIT | ▲Majority control of premium Sydney tower | ▼Higher leverage near term |
| Unitholders | ▲Potential DPU accretion | ▼Balance-sheet pressure |
| Sydney office landlords | ▲Validation of prime asset demand | ▼More competition for capital |
| Sellers of 180 George stake | ▲Sale at agreed premium asset value | ▼Reduced ownership upside |