Petronet LNG showed the kind of operating momentum investors like to see from a cash-generating energy utility: revenue surged almost 30% from the previous quarter, profit rose 9.1%, and the company backed the numbers with an interim dividend of ₹7 a share.
Petronet LNG revenue rises 30%, dividend declared
The bigger story is not just that earnings improved, but that the business is benefiting from much stronger volume throughput. In a sector where fixed infrastructure can turn higher utilization into outsized cash flow, Petronet’s top-line jump to ₹7,200 crore from ₹5,554 crore in the preceding quarter points to healthier demand across its LNG chain. For long-term investors, that matters because it suggests the company is not merely riding price swings; it is monetizing its terminals and logistics network more effectively.
Sentiment Indicators
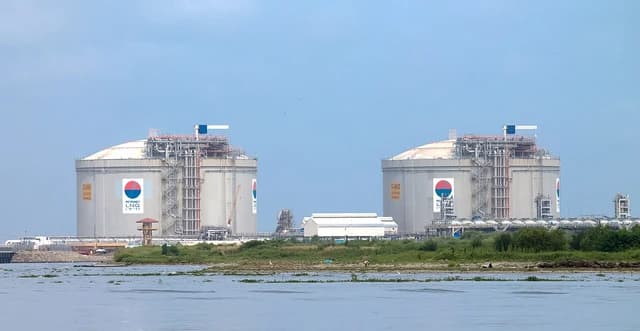
Still, the quarter was not a clean expansion story. EBITDA increased 8.6% to ₹1,663 crore, but the EBITDA margin narrowed to 23% from 28%, showing that revenue growth did not flow through at the same rate to operating profit. That kind of margin compression can happen when volume growth comes with different mix, costs or pricing dynamics, and it is the main reason the profit increase lagged the surge in sales. Even so, the absolute earnings base remains robust enough to support capital returns, as shown by the board’s interim dividend.
The market had already started to price in a better quarter. Petronet shares closed 3.96% higher at ₹300.95 on Monday before the results announcement, reflecting investor optimism that stronger throughput would show up in the numbers. For holders, the share move underscores a simple idea: when a steady infrastructure business improves utilization, earnings can compound quickly without needing a full-blown industry boom.
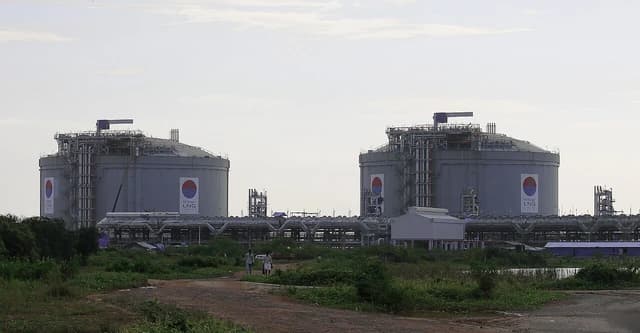
For investors looking beyond one quarter, Petronet remains a classic long-duration energy play. India’s LNG demand story is still tied to industrial growth, cleaner fuel adoption and the gradual build-out of gas infrastructure. That makes quarterly volatility worth watching, but not overreacting to. The key question over the next few years is whether Petronet can keep lifting volumes while defending margins enough to sustain dividend growth.
| Entity | Gains | Losses |
|---|---|---|
| Petronet LNG | ▲Higher revenue and dividend capacity | ▼Margin pressure from mixed costs |
| Shareholders | ▲Better cash returns and earnings momentum | ▼Less upside if margins keep narrowing |
| LNG users/customers | ▲Better access to infrastructure and supply | ▼Potentially tighter pricing if demand strengthens |
| Short-term traders | ▲Volatility around results | ▼Missed pre-results move if already positioned too late |