Portugal just got a meaningful vote of confidence from Fitch, and for investors the bigger message is not the headline upgrade itself but what it says about the country’s borrowing capacity, fiscal discipline and place in Europe’s lower-risk credit tier.
Portugal rating upgraded to A+ by Fitch

Fitch raised Portugal’s long-term sovereign rating to A+ from A and shifted the outlook to stable, citing stronger public finances, a projected decline in the debt burden and budget balances that it said are considerably better than those of peers. In plain English, Portugal is looking less like a chronic comeback story and more like a country that has earned a steadier credit profile.
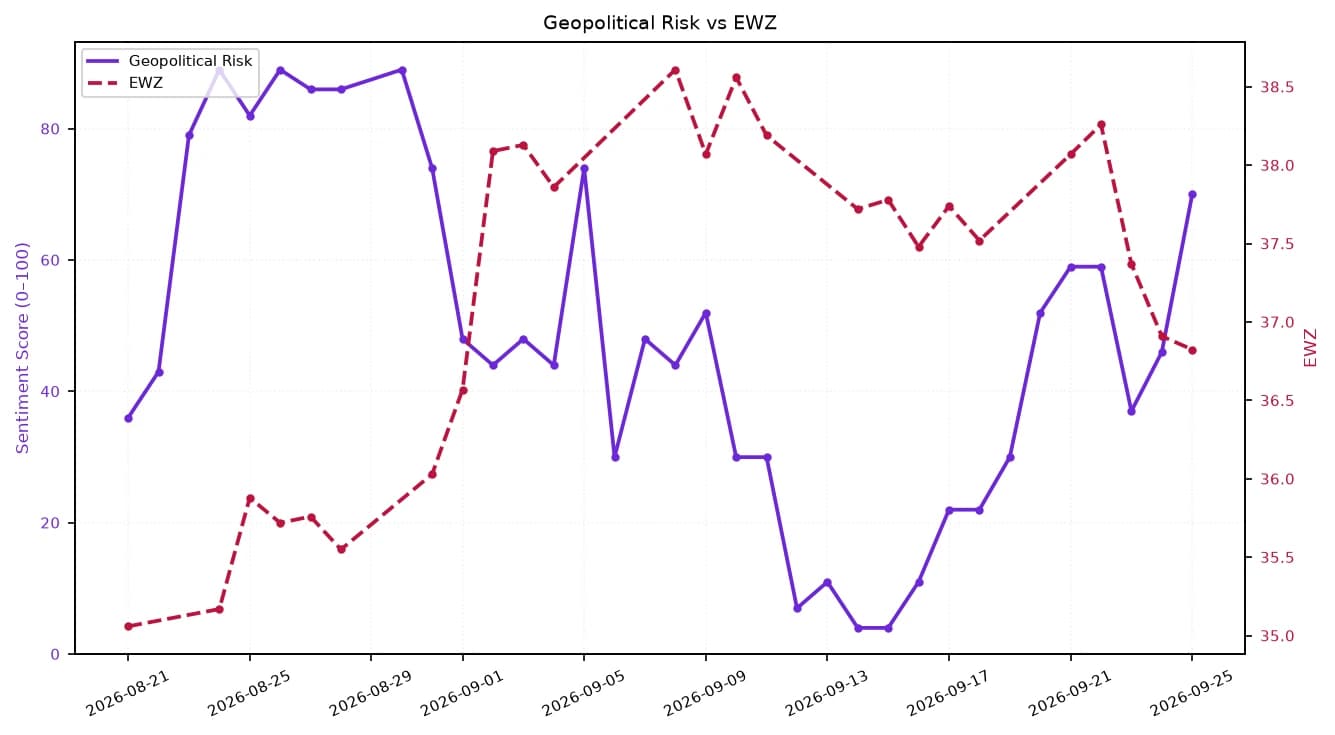
Sentiment IndicatorsⓘProprietary · adalytica.com · September 5, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse

That matters economically because sovereign ratings still affect the price governments pay to borrow, how broad a pool of institutions can own their debt and how much room a state has to respond if growth slows. A better rating can help keep funding costs contained over time, especially when markets are already sensitive to debt sustainability and fiscal credibility across Europe.
It also matters to investors because Portugal is moving deeper into the investment-grade mainstream. Fitch is now aligned with S&P at A+, while Moody’s remains lower at A3. The move does not transform Portugal overnight, but it reinforces a long-running improvement in the country’s balance sheet and reduces the odds that borrowing costs drift higher simply because lenders demand a larger risk premium.
The upgrade is also a reminder that the market reward for discipline can compound. Portugal has spent years cutting debt ratios and supporting growth, and Fitch said the government’s commitment to fiscal prudence remains a key support. That is the kind of backdrop long-term bond investors like to see, because it suggests less policy noise and more resilience if the cycle weakens.
For equity investors with exposure to Portugal through the EWP ETF, the news is supportive rather than explosive. The fund’s recent trading shows it has been holding above its 50-day and 200-day moving averages, a sign of improving trend strength, but sovereign upgrades are rarely a one-day catalyst for stocks. Over a multi-year horizon, though, a stronger sovereign profile can help underpin lower financing costs, steadier domestic demand and a better investment climate.
There is still a distinction to make: Portugal is not Germany, and it is not risk-free. Growth still matters, as do external shocks, European policy shifts and the path of rates. But the direction of travel is clearly favorable, and ratings agencies usually do not hand out upgrades unless the underlying fiscal story has become more durable.
The next checkpoints will be DBRS on Nov. 13 and Moody’s on Nov. 20. If those reviews echo Fitch’s confidence, Portugal’s credit comeback will look even more entrenched, and that should keep the country on the watchlist for investors who want steady, compounding improvements rather than headline-grabbing surprises.
| Entity | Gains | Losses |
|---|---|---|
| Portugal government | ▲Lower funding costs | ▼Less pressure from creditors |
| Bondholders | ▲Stronger credit profile | ▼Less upside from spread tightening |
| Portuguese economy | ▲Better investor confidence | ▼None material |
| Rating skeptics | ▲Less support for bearish thesis | ▼Upgraded by peers |