Rivian’s shares are sliding again as investors question whether the company can execute the production ramp for its mass-market electric vehicle without more strain on margins and cash.
Rivian Shares Fall on Mass-Market EV Ramp Concerns

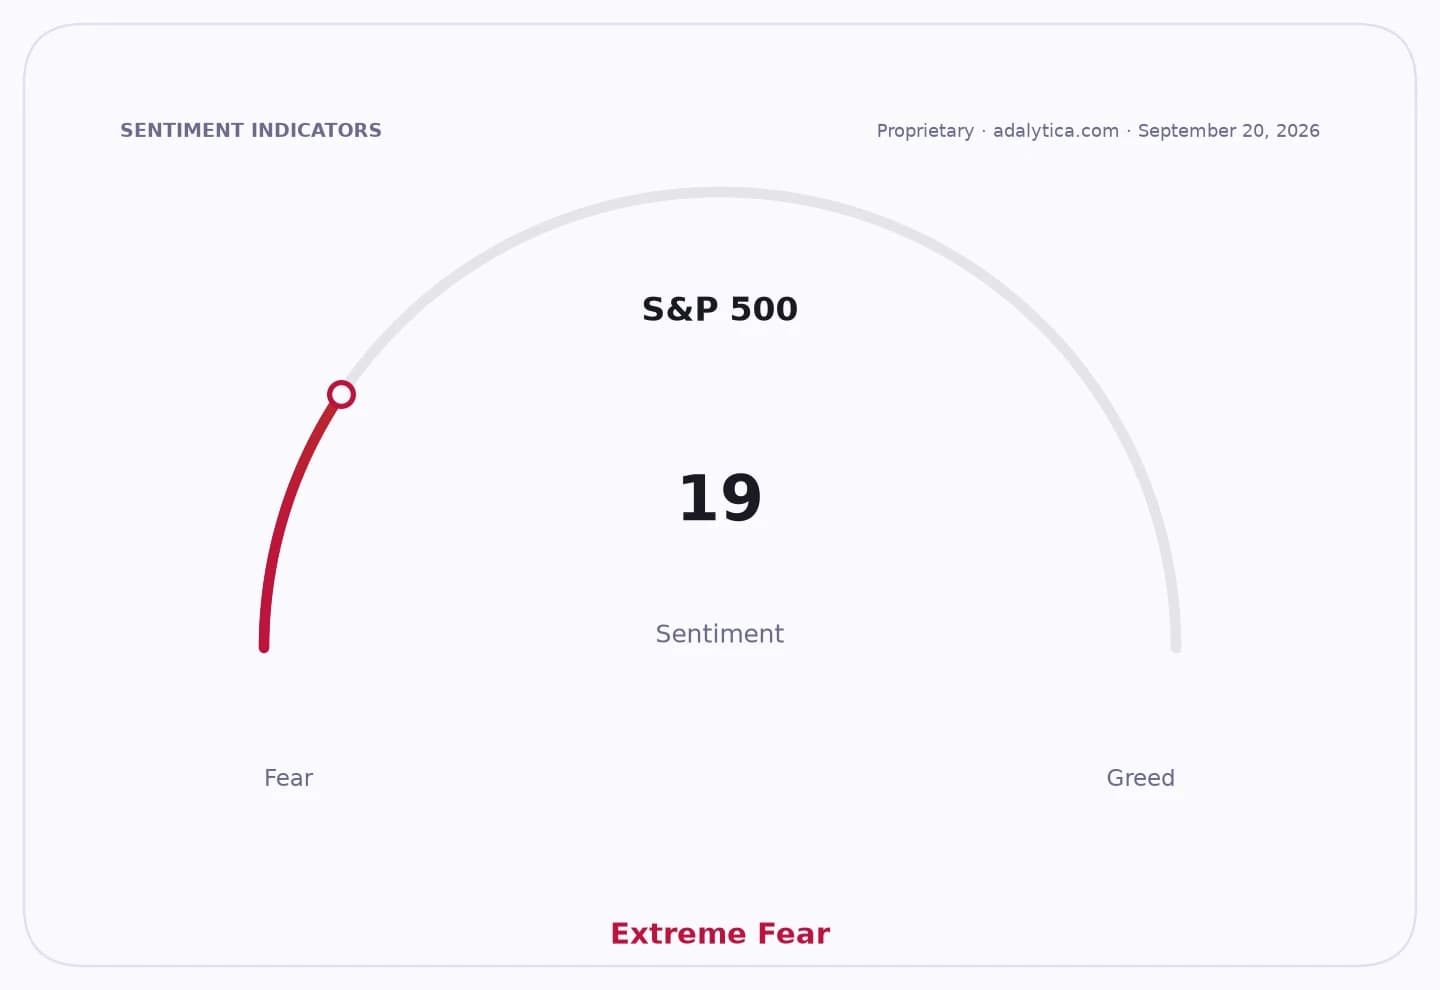
The stock closed at $15.97 on Sept. 17, down from a recent peak above $22 in December, and remains roughly flat to slightly below both its 50-day and 200-day moving averages, a sign the market is still waiting for proof that the next phase of growth can translate into durable earnings power. Trading has also turned more cautious overall, with the S&P 500 shown in Adalytica’s trade signals sitting in a “Fear” reading, while Rivian’s own price action has lost momentum after a sharp mid-year rebound.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 17, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For Rivian, the issue is less whether demand exists for EVs and more whether it can scale a lower-priced model fast enough to compete with larger manufacturers that already have broader factories, supplier leverage and deeper balance sheets. That is the central investor debate: a successful ramp could widen Rivian’s addressable market and improve volume economics, but a slow launch or misstep would likely force higher spending on manufacturing, marketing and working capital just when the company needs discipline.
The concern is familiar for capital-intensive EV makers. Rivian’s filings have repeatedly warned that it may need higher promotional spending to sustain demand and that failure to scale efficiently could hurt raw-material availability, costs and production. Those risks matter because the company is still being valued more on execution than on current profitability. If the mass-market program lands, Rivian could move closer to the kind of unit-cost structure investors have long expected from the sector’s winners. If it slips, the business may remain stuck in a cycle of heavy investment and thin margins.
The selloff also reflects a broader market reassessment of EV growth stories. Tesla’s shares have outperformed Rivian’s over the period in question, underlining how investors continue to favor scale and manufacturing maturity over concept alone. General Motors, meanwhile, has been reshaping its own EV capacity, a reminder that legacy automakers can dial investment up or down more easily if demand softens. That leaves Rivian exposed to a tougher comparison set: it must prove not just that it can build vehicles, but that it can build them profitably.
For investors, the next catalyst is straightforward: confirmation that the mass-market EV is moving from promise to production without a sharp deterioration in margins, deliveries or cash burn. Until then, Rivian’s stock is likely to trade as a bet on execution rather than a clean growth story.
| Entity | Gains | Losses |
|---|---|---|
| Rivian bulls | ▲Lower-price EV success | ▼Ramp delays |
| Rivian shorts | ▲Execution doubts | ▼Strong launch |
| Tesla, GM | ▲Scale advantage | ▼Rivian market-share gains |
| Consumers | ▲More EV choice | ▼Fewer affordable options |