Romania’s finance ministry has opened a new retail government bond window that offers households tax-free returns as high as 7.5%, underscoring Bucharest’s reliance on domestic savers to help fund the state at a time when global borrowing costs remain elevated.
Romania opens Tezaur retail bond sale at 7.5%
The Tezaur programme’s November-December session runs from Nov. 9 to Dec. 4, according to Finance Minister Order No. 1528/2026 published in the Official Gazette. The bonds come in one-, three- and five-year maturities with annual coupons of 6.5%, 7% and 7.5%, and are issued in dematerialised form with a face value of 1 leu. Individual investors can buy through the treasury, post offices and the ghiseul.ro platform, with the online channel allowing subscriptions up to 200,000 lei per issuance code.
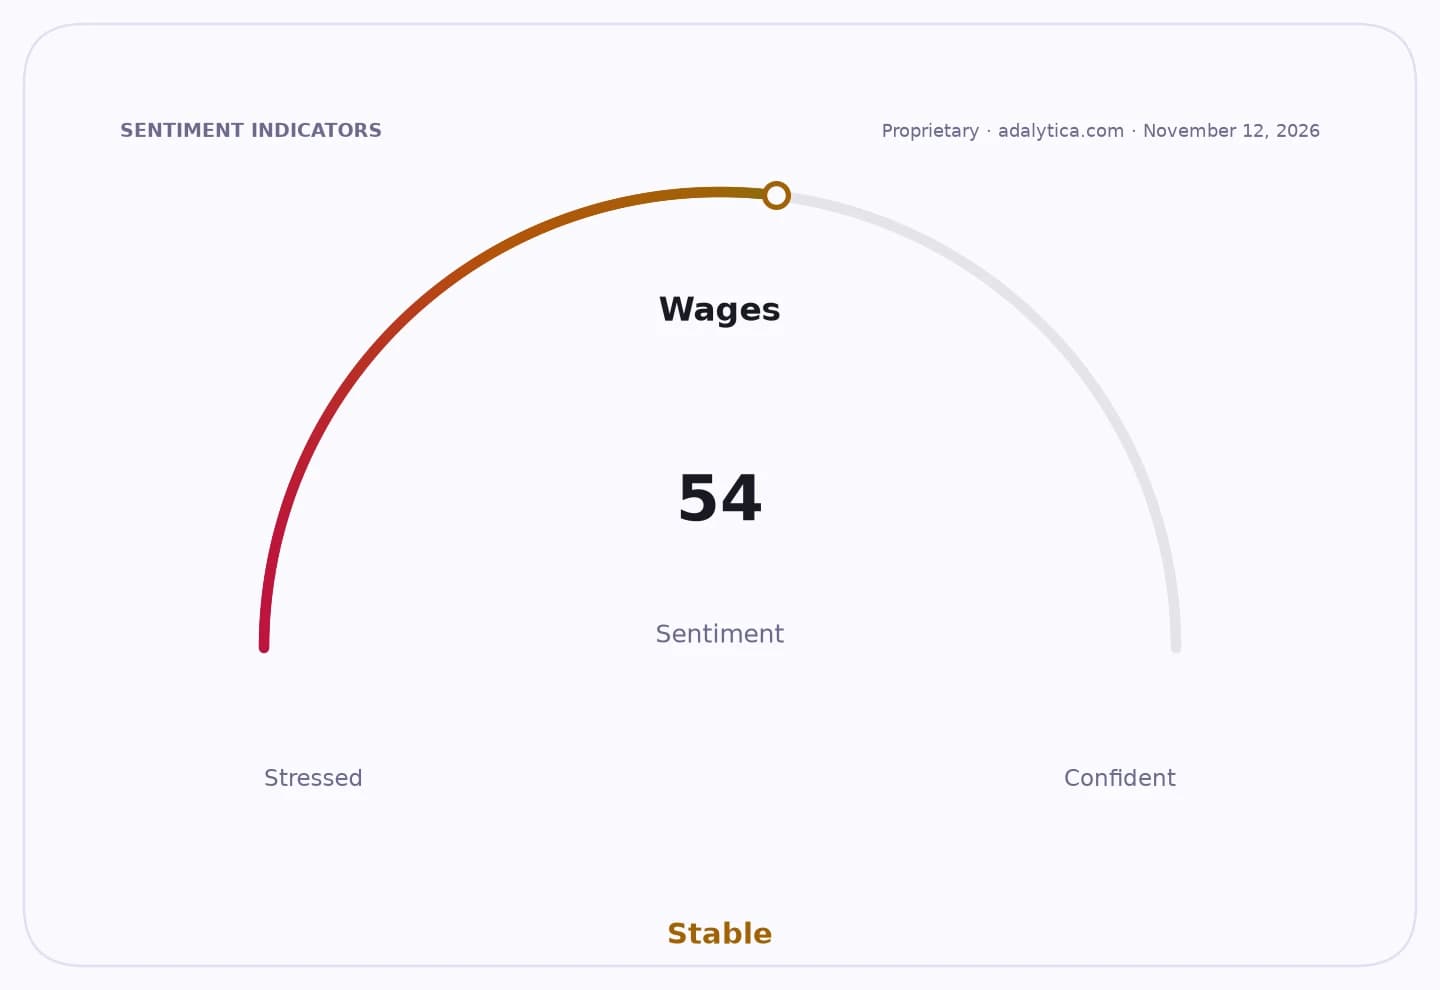
Sentiment Indicators
The pitch is straightforward: the state is offering retail investors a yield premium and tax exemption to lock in longer-term funding without relying entirely on wholesale markets. That matters for Romania because household demand can broaden the investor base, reduce refinancing pressure and give the government a lower-volatility source of financing than tapping bond markets alone. In a higher-rate environment, the tax-free feature materially improves the after-tax appeal of the paper for local savers.
For investors, the offering is also a window into the sovereign’s funding strategy and risk pricing. A 7.5% tax-free five-year coupon signals that Bucharest still has to pay up for medium-term money, reflecting both domestic inflation dynamics and the broader interest-rate backdrop. US benchmarks remain far above the ultra-low-rate era, with the 10-year Treasury around 4.8% and the Fed funds rate near 3.9%, while Romania’s retail offer is designed to compete directly with deposits and other low-risk savings products.
The structure also has market implications beyond household portfolios. Strong retail take-up can ease pressure on the government’s funding calendar and support confidence in the sovereign curve, while weak uptake would suggest investors are demanding even more compensation for duration and fiscal risk. For banks and other local fixed-income issuers, the programme can also influence pricing by setting a visible benchmark for tax-advantaged savings.
The key question now is whether Romanian households will keep channeling cash into state paper as inflation, deposit rates and alternative investment options evolve. If demand proves robust, the Finance Ministry gains a cheap and politically palatable funding source. If not, the state may need to lean harder on institutional markets, where borrowing costs tend to move faster and higher.
| Entity | Gains | Losses |
|---|---|---|
| Romanian government | ▲Cheaper domestic funding | ▼Greater reliance on markets if demand is weak |
| Retail savers | ▲Tax-free fixed income | ▼Limited liquidity and duration risk |
| Local banks | ▲Less immediate deposit outflow pressure | ▼Competition for household savings |
| Institutional bond investors | ▲Clear sovereign pricing reference | ▼Potentially reduced supply premium |