A Saudi research house has kept its “increase positions” call on Saudi Aramco and its target price at 29.6 riyals, arguing that the stock still offers room to rerate as oil prices stay elevated and earnings are set to rebound sharply into 2026.
Saudi Aramco target raised to 29.6 riyals
That matters because Aramco remains the anchor of Saudi equity income and one of the clearest ways investors express a view on geopolitics, crude supply and Gulf cash generation. If the oil backdrop holds, the market is still underpricing the combination of resilient output, stronger refining margins and a dividend stream that looks hard to ignore.
Sentiment Indicators
Aljazira Capital said Aramco is trading at 12.9 times expected earnings for 2026, with a dividend yield of 5.2%, while forecasting revenue growth of 24.3% to 2.078 trillion riyals and net profit growth of 40.2% to 488 billion riyals next year. Its model assumes average crude prices of about $91 a barrel and hydrocarbon output of 11.2 million barrels of oil equivalent a day, including 8 million barrels a day of crude.
The call lands at a moment when the oil market is still being shaped by geopolitical risk. WTI has climbed and retreated sharply this year, but the key point for Aramco investors is that the company’s cash flow sensitivity remains high when crude trades near or above the low-$90s. Adalytica’s oil trade signal snapshot still shows neutral sentiment, but fear in awareness remains elevated, underscoring how quickly supply-risk headlines can reprice the market.
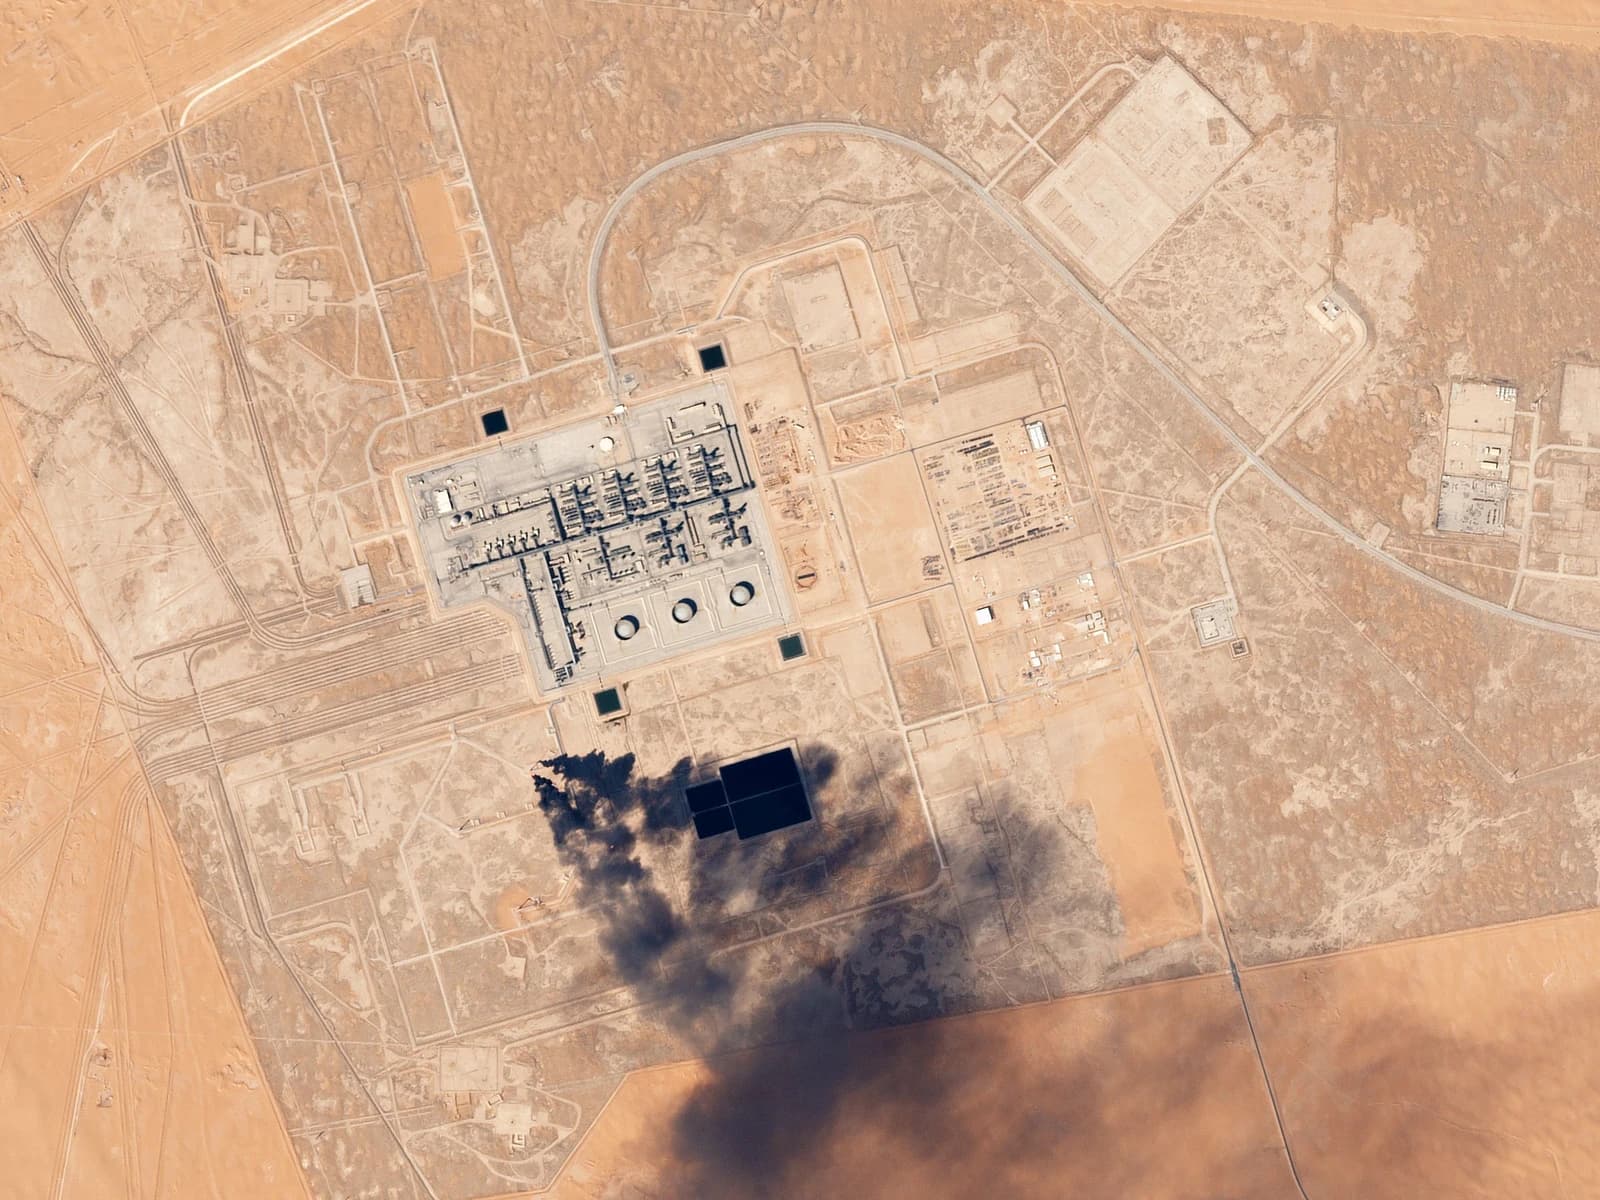
The research note also pointed to Aramco’s ability to shift exports from the eastern coast to the western side, a reminder that the company has operational flexibility even as regional tensions persist. That flexibility matters economically because it helps protect volumes, supports export continuity and reduces the odds that short-term disruption turns into a longer-lasting earnings shock.
For the latest quarter, Aramco reported net income attributable to shareholders of 137.4 billion riyals, up 41.3% from a year earlier, helped by a one-off 25.9 billion-riyal gain on the sale of a stake in a subsidiary. Adjusted net profit was 118.4 billion riyals, slightly below the previous quarter as higher selling and administrative costs squeezed the adjusted operating margin even though revenue rose 1% quarter on quarter to 526.8 billion riyals.
The revenue mix still points to the core investment case: upstream volumes and prices do the heavy lifting, while refining margins can soften the blow when crude weakens. Operating profit rose 3.8% from the prior quarter to 226.3 billion riyals, even as adjusted operating profit slipped 6.7%, showing how sensitive the stock remains to commodity pricing and cost discipline.
Technically, Aramco shares have recovered to 26.16 riyals, above both the 50-day moving average and the 200-day moving average, which suggests the market has begun to acknowledge the earnings setup. But the stock still trades below the 29.6-riyal target, leaving a meaningful gap if crude stays firm and the 2026 numbers prove achievable.
The broader investment takeaway is straightforward: Aramco is not a slow-moving utility-style income play so much as a leveraged claim on oil, Middle East stability and Saudi dividend capacity. For investors willing to own energy through the next geopolitical swing, this remains one of the cleaner asymmetric setups in the large-cap market.
| Entity | Gains | Losses |
|---|---|---|
| Aramco shareholders | ▲Higher earnings and rerating potential | ▼Volatility from oil and geopolitics |
| Saudi equity income investors | ▲5.2% dividend yield support | ▼Lower upside if crude softens |
| Oil bulls | ▲Benefit from $91 Brent-style assumptions | ▼Lose if supply risk eases |
| Downstream consumers | ▲— | ▼Higher fuel and input costs |