Singapore’s biggest lenders are under pressure from a tougher rate backdrop that is complicating the outlook for earnings and prompting investors to trim exposure to the sector.
Singapore banks face pressure from higher yields
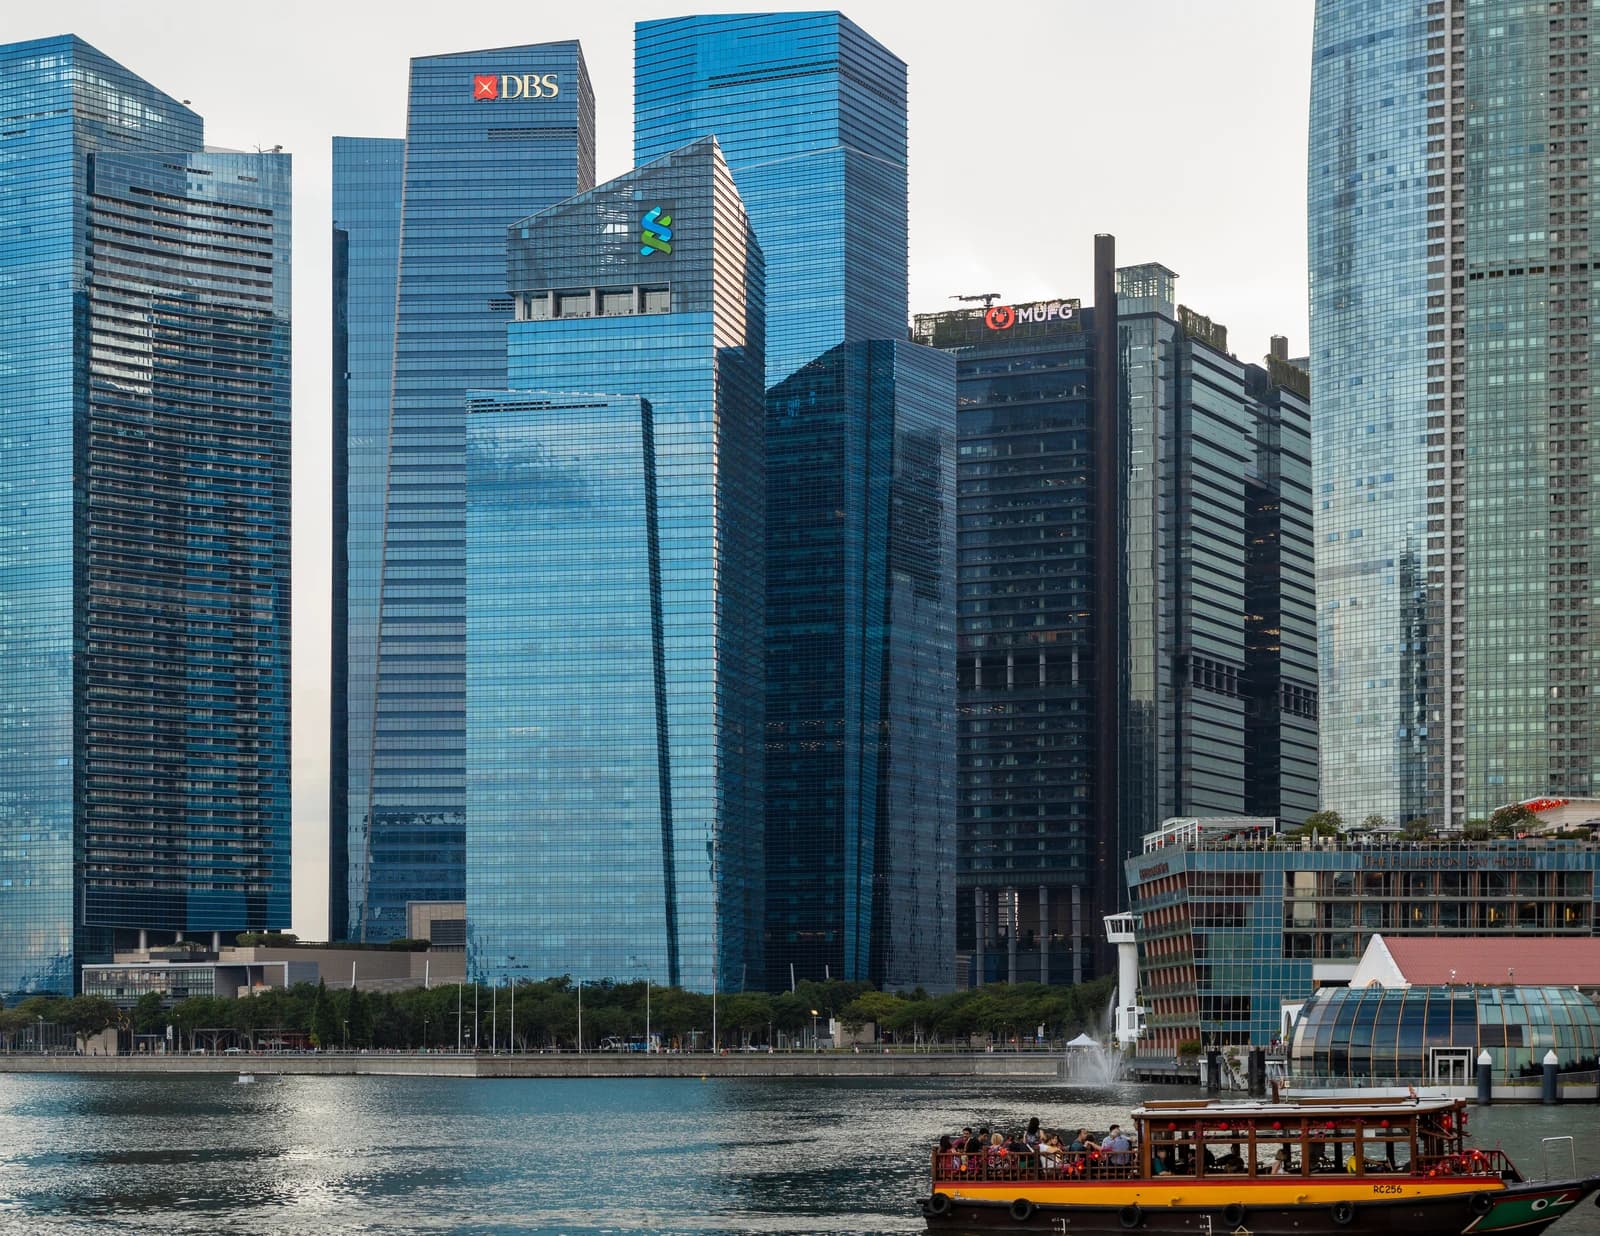
OCBC, DBS and UOB have reported third-quarter results against a slide in their shares, reflecting concern that higher bond yields and uncertainty over the path of interest rates will erode the profit tailwind banks have enjoyed from the post-pandemic rate cycle. For a sector that has been a mainstay of Singapore equities and a reliable source of dividend income, the market is now discounting less room for earnings upgrades and a more fragile net-interest-margin outlook.
Sentiment Indicators
The stakes are economic as well as market-driven. Singapore banks are closely tied to domestic credit demand, regional trade finance and wealth management flows, so any squeeze in profitability can feed through to lending appetite, capital allocation and shareholder returns. Higher sovereign yields can also pressure bond portfolios and mark-to-market valuations, while a less predictable rate path makes it harder for lenders to manage deposit costs and loan pricing.
That uncertainty has been amplified by the shift in global fixed-income markets. The US 10-year Treasury yield has climbed to around 4.95% in the latest data, while the US policy rate remains near 3.9%, leaving investors with fewer clues on when or how quickly easing may come. The yield curve between two- and 10-year Treasuries has flattened to about 24 basis points, a sign that markets expect slower growth and eventually lower rates, even as long-term borrowing costs stay elevated.
For Singapore banks, that combination is awkward. If yields remain high, funding costs may stay sticky and bond losses can cap earnings momentum. If rates start to fall, net interest income may weaken faster than expected. In both cases, the easy gains from a rising-rate environment diminish. That leaves investors focusing more heavily on fee income, asset quality and capital returns rather than simply on headline profit growth.
There is also a valuation angle. Bank shares often act as proxies for rate expectations, and the recent weakness suggests investors are questioning whether current dividend yields are enough compensation for the macro uncertainty. UOB’s trading pattern underscores the pressure: the stock has fallen back from above 68 Singapore dollars in October to about 58.7 by Nov. 12, while its 50-day moving average has rolled over and the RSI has dropped into deeply oversold territory, conventional technical signals that point to heavy selling momentum.
The bull case is that Singapore banks remain among the region’s strongest franchises, with solid capital buffers, disciplined lending and resilient fee businesses. The bear case is that earnings have likely peaked for this phase of the cycle, and the market is starting to price in that reality before it is fully visible in results. The key question for the next few quarters is whether bond yields stabilize enough to support margins, or whether a more volatile rate environment forces another reset in earnings expectations.