September’s best-selling motorcycles above 500 cubic centimeters show a market in the middle of a structural shift: trail bikes have become the dominant format, China is supplying much of the volume, and BMW has forced its GS family back into the center of the premium segment.
Spain September motorcycle sales shift to trail bikes
That matters because the mix change is not just a style preference. It points to where unit growth, pricing power and dealer inventory are moving in Europe’s large-displacement market. Trail bikes now occupy nine of the 10 top slots in Spain for September 2026, leaving naked bikes with only one place in the ranking and reinforcing a long decline in roadster demand.
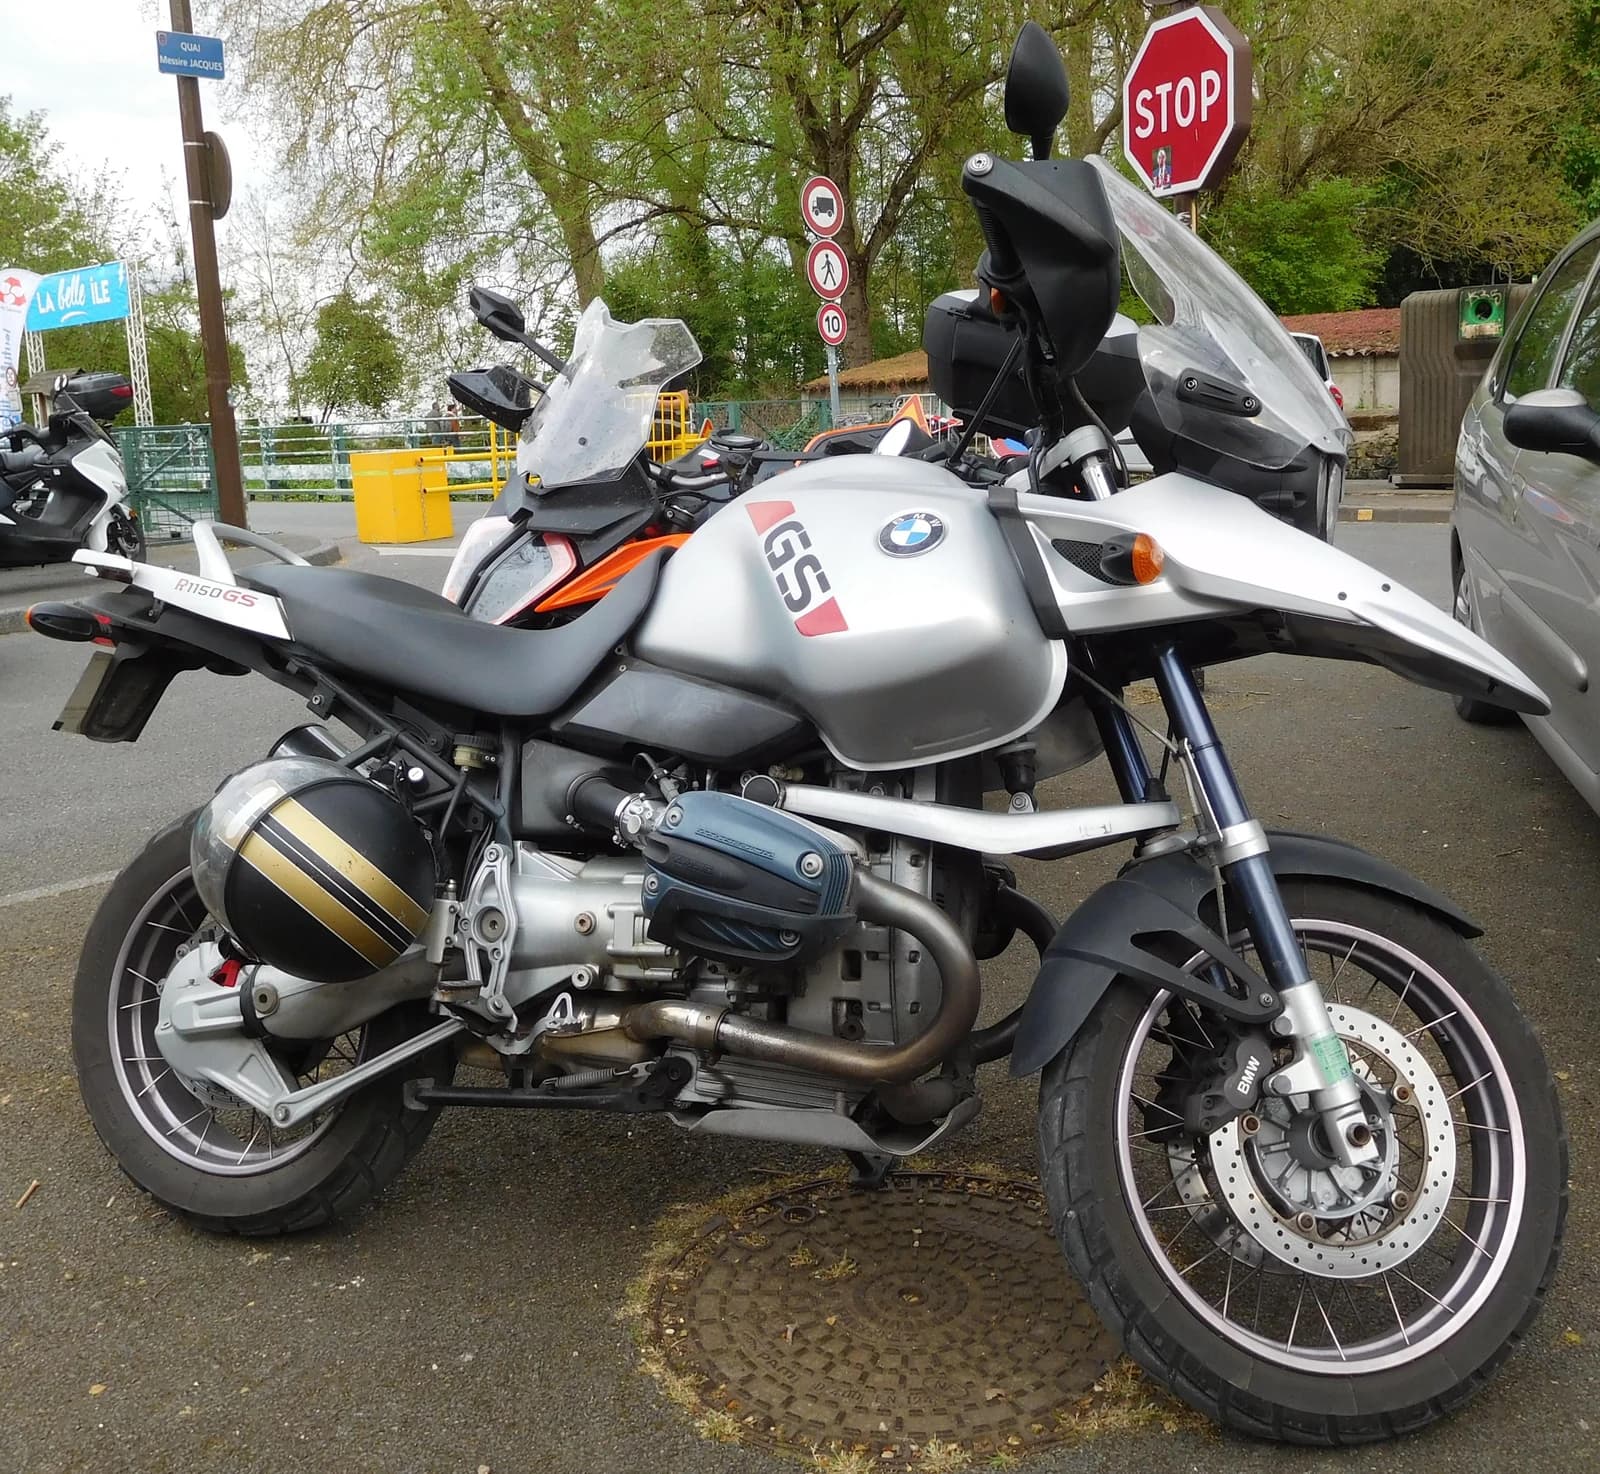
At the top of the list, Voge’s DS 800 Rally led with 405 units, followed by the DSX 900 with 322. BMW’s R 1300 GS came in third with 271 units, a notable return to the podium for a model that has long defined the adventure category. The ranking also placed the R 1300 GS Adventure sixth with 199 units and the F 800 GS eighth with 182, giving BMW three GS-branded models in the top 10 for what appears to be the first time in a long while.
For investors, that combination is more important than any single model ranking. It suggests the premium adventure-bike segment remains resilient even as lower-priced Chinese brands gain share. BMW is still defending one of its most valuable franchises, while challengers such as Voge and Kove are widening the competitive field with lighter, lower-cost alternatives that appeal to riders trading up from commuter or mid-displacement bikes.
The numbers also underline how the market has changed. The traditional Japanese and European mix is being diluted by Chinese manufacturers that are now present across much of the sales table. Yet the story is not simply one of Chinese dominance. The September list still shows a fragmented market, with four Chinese entries, three German models and three Japanese models among the 10 best sellers. In other words, China is setting the pace on volume, but established brands still hold meaningful positions in the most profitable part of the segment.
BMW’s strong showing may also reflect more than underlying demand. The Spanish report suggested dealer promotions in Catalonia may have inflated registrations for the R 1300 GS, and that October will help determine whether the jump was driven by incentives or by genuine model strength. Another possibility is anticipation around a possible 2027 GS update, which could be pulling forward purchases. Either way, the September print is a reminder that BMW’s GS range retains exceptional pull with buyers.
For Honda, the picture is mixed. The CB500X was the only Japanese model in the top 10 to come in below the larger-displacement heavyweight trail bikes, which reinforces the idea that the market is increasingly rewarding higher-capacity adventure machines rather than midrange all-rounders. On the share-price side, Honda Motor’s U.S.-listed shares have been trading below both the 50-day and 200-day moving averages, even as the motorcycle business remains one of the company’s steadier global profit engines.
BMW is not publicly listed in the same way in the provided data, but its motorcycle performance matters for sentiment around premium two-wheelers and for broader competitive positioning in Europe. The return of the R 1300 GS to the podium is a sign that the GS brand still has pricing power and brand loyalty, even in a market where Chinese rivals are taking more shelf space.
The key question for the next month is whether September was an incentive-driven spike or the start of a new phase in adventure-bike demand. If BMW’s GS line can hold this level without heavy discounting, it would validate the premium end of the market. If it fades in October, the more lasting story may be the acceleration of Chinese share gains in Europe’s large-capacity motorcycle segment.
| Entity | Gains | Losses |
|---|---|---|
| BMW GS family | ▲Podium return; three models in top 10 | ▼Risk of promo-led demand |
| Chinese brands (Voge, Kove) | ▲Volume leadership; wider share | ▼Pressure on premium expansion |
| Japanese makers (Yamaha, Honda) | ▲Select model resilience | ▼Loss of ground in top ranks |
| Dealers / buyers | ▲More choice and discounts | ▼Margins and resale values |