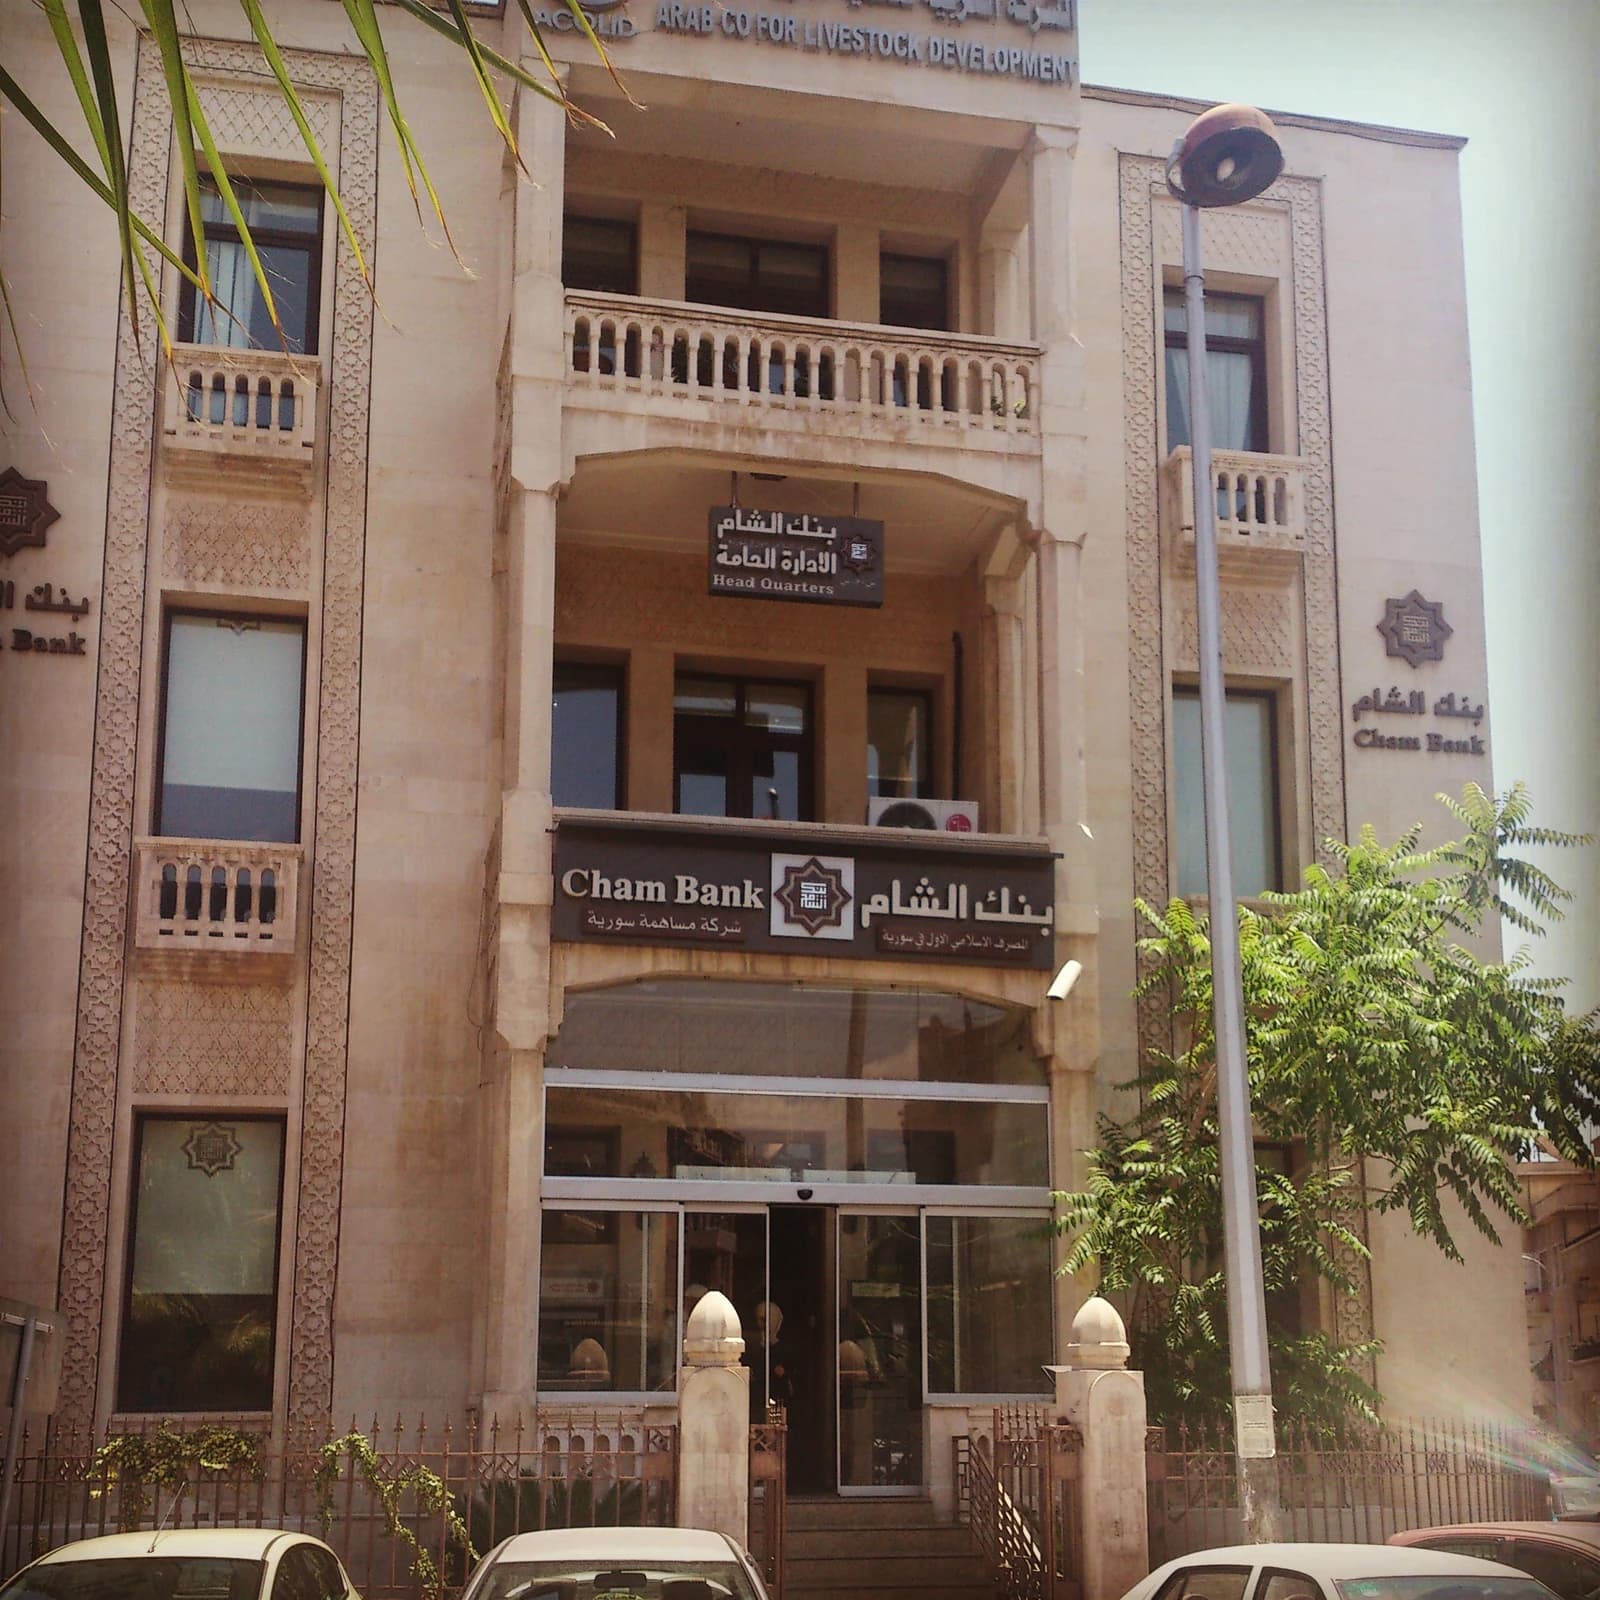
The Central Bank of Syria has moved to rein in bank commissions and fees, a step that could improve transparency for customers but also squeeze a banking sector still trying to rebuild activity after years of economic stress.
Syria central bank restricts bank fees and commissions
The new 11-article القرار requires lenders to publish written pricing policies, explain how charges are calculated and show the cost components behind the final price. It also bars banks from levying unjustified fees, including charges on current accounts that create a debit balance without a genuine service or contractual basis.
Sentiment Indicators
That matters because bank fees are often a material source of non-interest income in fragile banking systems, especially when loan growth is weak and deposit bases remain under pressure. By forcing banks to tie fees to actual costs and services, the regulator is trying to reduce opaque pricing practices that can discourage formal banking use and erode confidence in the system.
The rules also arrive as Damascus is trying to encourage a broader recovery in credit activity. More lending can support companies, households and state-linked economic flows, but it only works if customers believe the banking system is being run on predictable and fair terms. Fee caps or fee discipline can help bring more salary, payroll and current-account activity into banks, even if they also limit revenue for lenders accustomed to charging for routine services.
The central bank said the rules apply to licensed banks under its supervision, while leaving electronic payment charges to separate regulation. It also prohibited repeated fee changes without objective justification and blocked banks from charging for services that are bundled into the core product, a measure aimed at stopping re-labelling of costs as “account management” or periodic subscription fees.
For investors, the immediate effect is likely to be mixed. The policy could be margin-negative for banks that rely heavily on commissions, but it may also reduce conduct risk and improve the quality of customer relationships over time. The clearest beneficiaries are depositors and retail clients, who gain more price clarity and fewer arbitrary charges. The biggest losers are banks that have used fee structures to offset weak lending income.
In a market where trust is as important as balance-sheet repair, the new framework suggests Syria’s central bank is prioritizing formalization and consumer protection alongside credit expansion. The key test now is whether banks comply in practice — and whether tighter fee controls are matched by a broader revival in lending and transaction volumes.
| Entity | Gains | Losses |
|---|---|---|
| Bank customers | ▲Lower opaque charges | ▼Fewer unjustified fees |
| Syrian Central Bank | ▲Stronger oversight | ▼Less pricing flexibility for banks |
| Commercial banks | ▲Better trust over time | ▼Reduced commission income |
| Lending activity | ▲More formal usage | ▼Banks reliant on fee revenue |