US stocks were set to open modestly lower on Wednesday as a rebound in oil prices and a pause in the chip sector’s recent advance took some of the air out of a market that had been leaning on risk appetite and falling energy costs for support.
US Stocks Set to Open Lower as Oil Rebounds
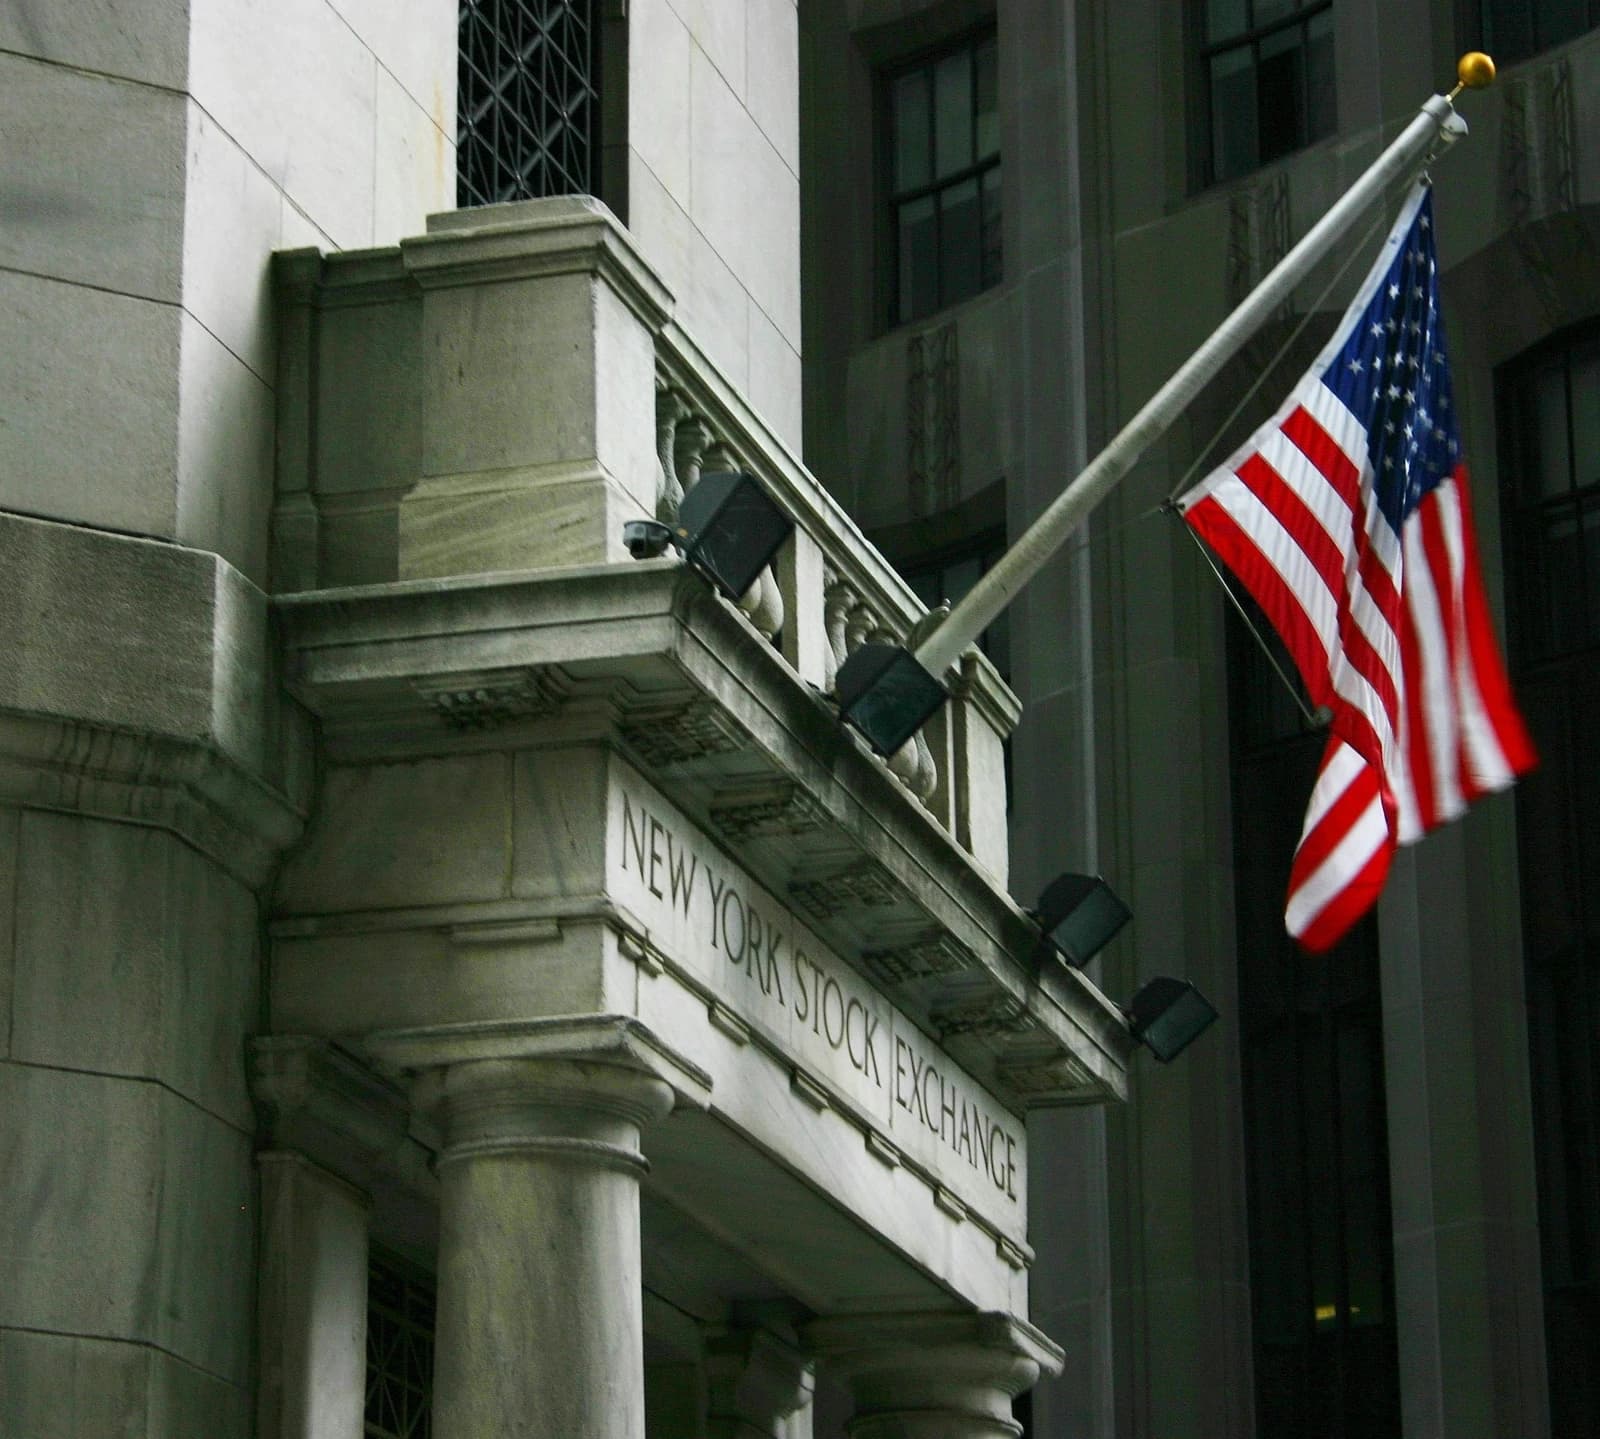
An hour before the opening bell, IG had the Dow Jones Industrial Average down 0.3% at 51,708 and the Nasdaq 100 slightly weaker at 30,656. The move comes after the Nasdaq touched a record on Tuesday, leaving investors reluctant to add exposure ahead of a cluster of geopolitical and policy-sensitive events that could reshape energy and technology sentiment.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 28, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The most immediate market driver is crude. Brent and WTI halted several days of declines and ticked higher again, removing a tailwind for equities that had benefited from easing inflation fears and lower input-cost expectations. Even a modest rise in oil can matter for a market priced around the assumption that price pressures are cooling: it supports the energy complex, but it also revives concern that transportation, industrial and consumer margins could be squeezed if the move extends.
That dynamic is visible in sector trading. The S&P 500 energy sector ETF, XLE, has been supported by the broader oil rebound, while the wider market remains near highs. By contrast, stocks that had benefited most from the recent easing in crude and from renewed enthusiasm around artificial intelligence were under a bit of pressure. Chip stocks eased premarket, with Nvidia down about 0.5%, suggesting the semiconductor group may interrupt a six-session winning streak as investors trim exposure after a sharp run-up.
The pause in semiconductors matters because the sector has been one of the main engines behind the market’s leadership this year. A weaker chip complex can weigh on the Nasdaq and on the megacap technology cohort that has carried much of the S&P 500’s gains. Microsoft was an exception, rising 0.8% premarket after Stifel upgraded the stock to buy, saying it sees mid- to high-single-digit revenue growth persisting. The call adds to a backdrop in which negative broker recommendations are becoming less common for the software giant.
Outside the large-cap tech names, some of the biggest moves were in more speculative corners of the market. IonQ jumped 12% after saying it had developed what it described as the industry’s first decoder for real-time quantum error correction running on a standard commercial processor. Worthington Enterprises rose 17% after beating quarterly profit and revenue forecasts, helped by acquisitions and a tariff refund. Those gains underscore how stock picking remains more important than ever in a market where the broad indices are close to record territory but leadership is still concentrated.
Investors are also watching geopolitics and trade. The market is waiting for clues from the UN General Assembly in New York, where hopes have risen of some progress between Washington and Tehran, though no concrete outcome has emerged. A separate focus is the expected arrival of Chinese President Xi Jinping for talks with Donald Trump, with AI safety also likely to feature in the discussions. Any shift in sanctions risk, energy supply expectations or US-China technology policy could quickly feed back into oil, semiconductors and the broader equity market.
For investors, the near-term question is whether this is just a modest consolidation after record highs or the start of a broader reset in risk appetite. With crude firming again, semiconductors pausing and the S&P 500 sitting near peak levels, the market is vulnerable to any disappointment from geopolitics or earnings-sensitive guidance. A sustained move higher in oil would favor energy shares and value sectors, but it would also complicate the inflation and rates outlook that has supported the rally in US equities.
| Entity | Gains | Losses |
|---|---|---|
| Energy stocks / XLE | ▲Higher crude prices | ▼Deflation-sensitive sectors |
| Chipmakers / Nasdaq 100 | ▲Recent AI demand trend | ▼Profit-taking after rally |
| Microsoft | ▲Analyst upgrade support | ▼Broad tech rotation risk |
| Oil importers / consumers | ▲Lower fuel relief ends | ▼Higher input and transport costs |