Abu Dhabi’s property market has taken a structural step toward deeper mortgage financing, with Aldar Properties and Abu Dhabi Commercial Bank completing the emirate’s first off-plan home loan under the new Adrec framework.
Abu Dhabi first off-plan home loan under Adrec
The deal matters because off-plan sales have long been funded largely in cash or through staged developer payments, limiting the pool of buyers able to enter the market and tying demand more closely to liquidity conditions than to household credit. A functioning off-plan mortgage channel broadens access, supports transaction volumes and gives lenders a new product line at a time when higher global rates have made housing finance more selective across many markets.
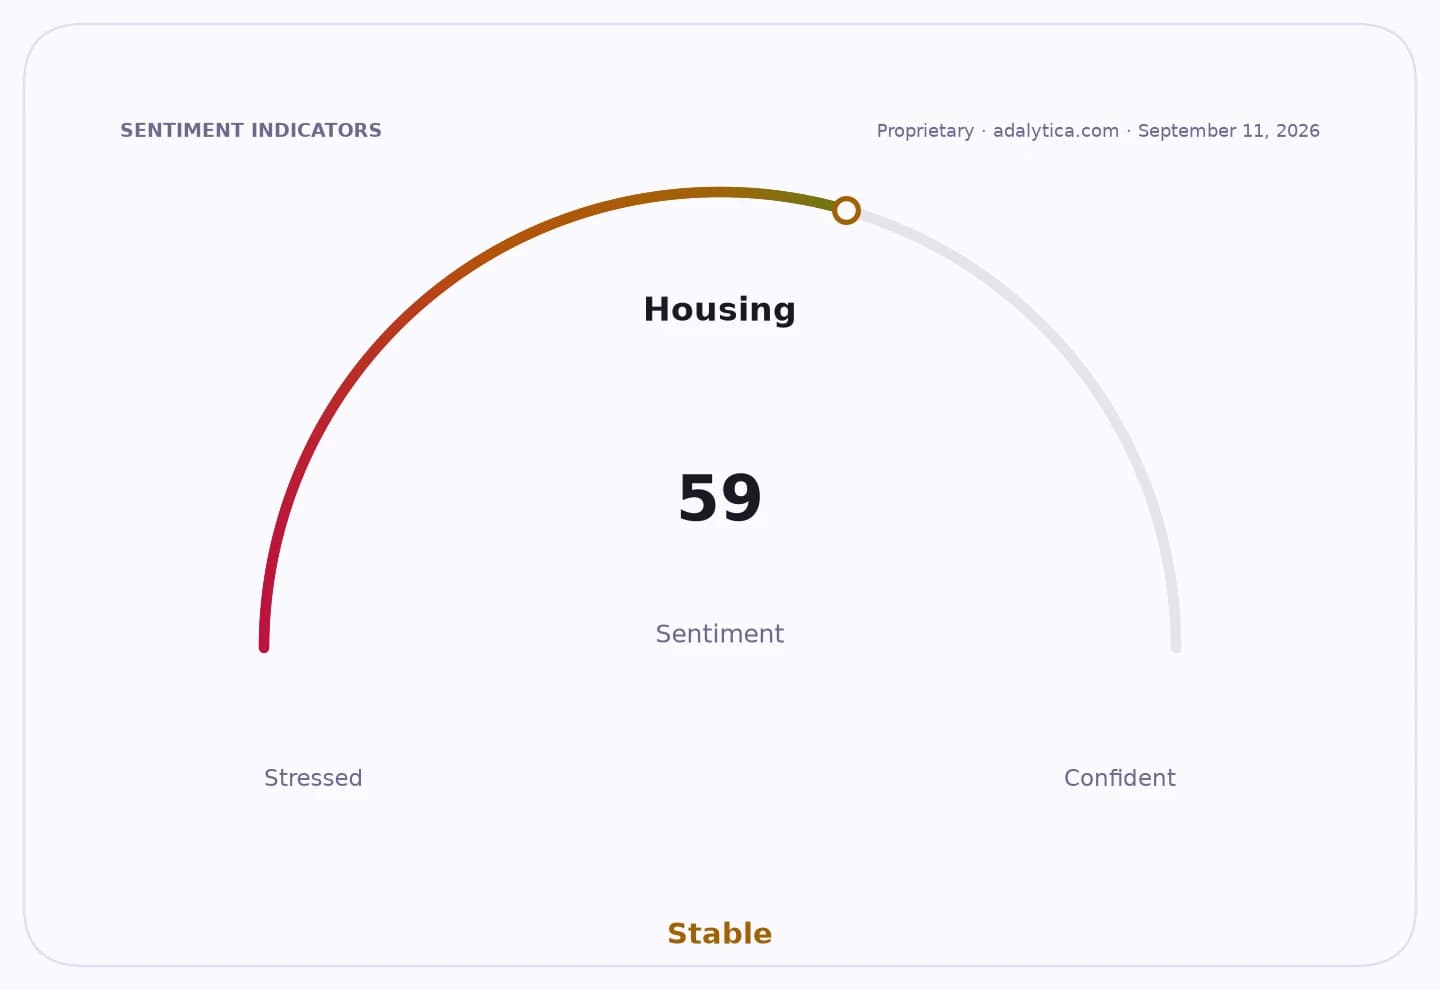
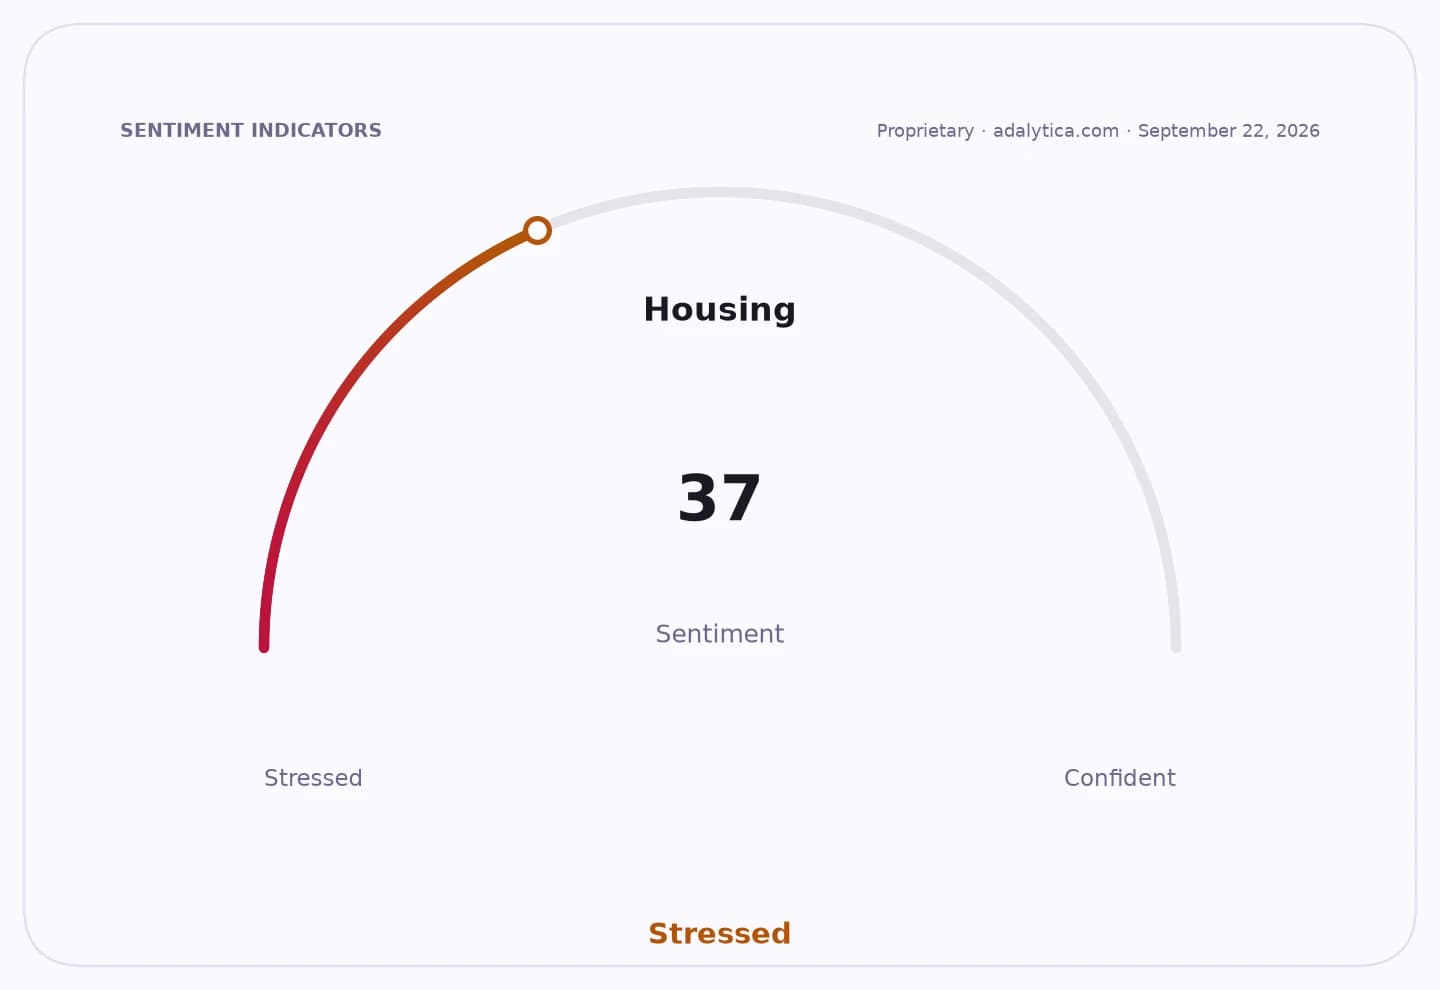
Sentiment IndicatorsⓘProprietary · adalytica.com · September 4, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For Abu Dhabi, the move also signals a more mature real-estate financing ecosystem. The emirate has been trying to deepen its property market, attract end-users rather than only speculative buyers and make ownership more affordable as housing demand rises. Allowing mortgages on units still under construction can improve affordability by lowering the upfront cash burden, while also helping developers lock in demand earlier in the project cycle.
For Aldar, the transaction reinforces its position as the dominant listed developer in the capital and could support sales velocity on future launches. For ADCB, it opens the door to a mortgage segment that can generate recurring interest income and cross-sell opportunities, though underwriting off-plan assets carries execution and completion risk that is typically higher than for completed homes.
The backdrop is a global housing market still being shaped by elevated borrowing costs. U.S. Treasury yields remain near 4.8% on the 10-year and about 4.4% on the 2-year, underscoring how restrictive financing conditions remain internationally even as local markets pursue growth. In that setting, Abu Dhabi’s willingness to formalize off-plan lending looks less like a tactical deal and more like policy-supported infrastructure for the housing market.
Investor attention will now turn to how quickly the framework is adopted beyond this first transaction, whether other banks follow ADCB, and whether the new channel materially boosts Aldar’s pre-sales and conversion rates. If the product gains traction, it could become an important support for development activity and bank lending in the capital; if not, the market will remain dependent on cash buyers and large down payments.
| Entity | Gains | Losses |
|---|---|---|
| Aldar Properties | ▲Faster off-plan sales | ▼Reliance on cash buyers |
| ADCB | ▲New mortgage income stream | ▼Higher underwriting risk |
| Homebuyers | ▲Lower upfront cash burden | ▼Higher leverage exposure |
| Cash-funded buyers | ▲Less price advantage | ▼Tighter competition |