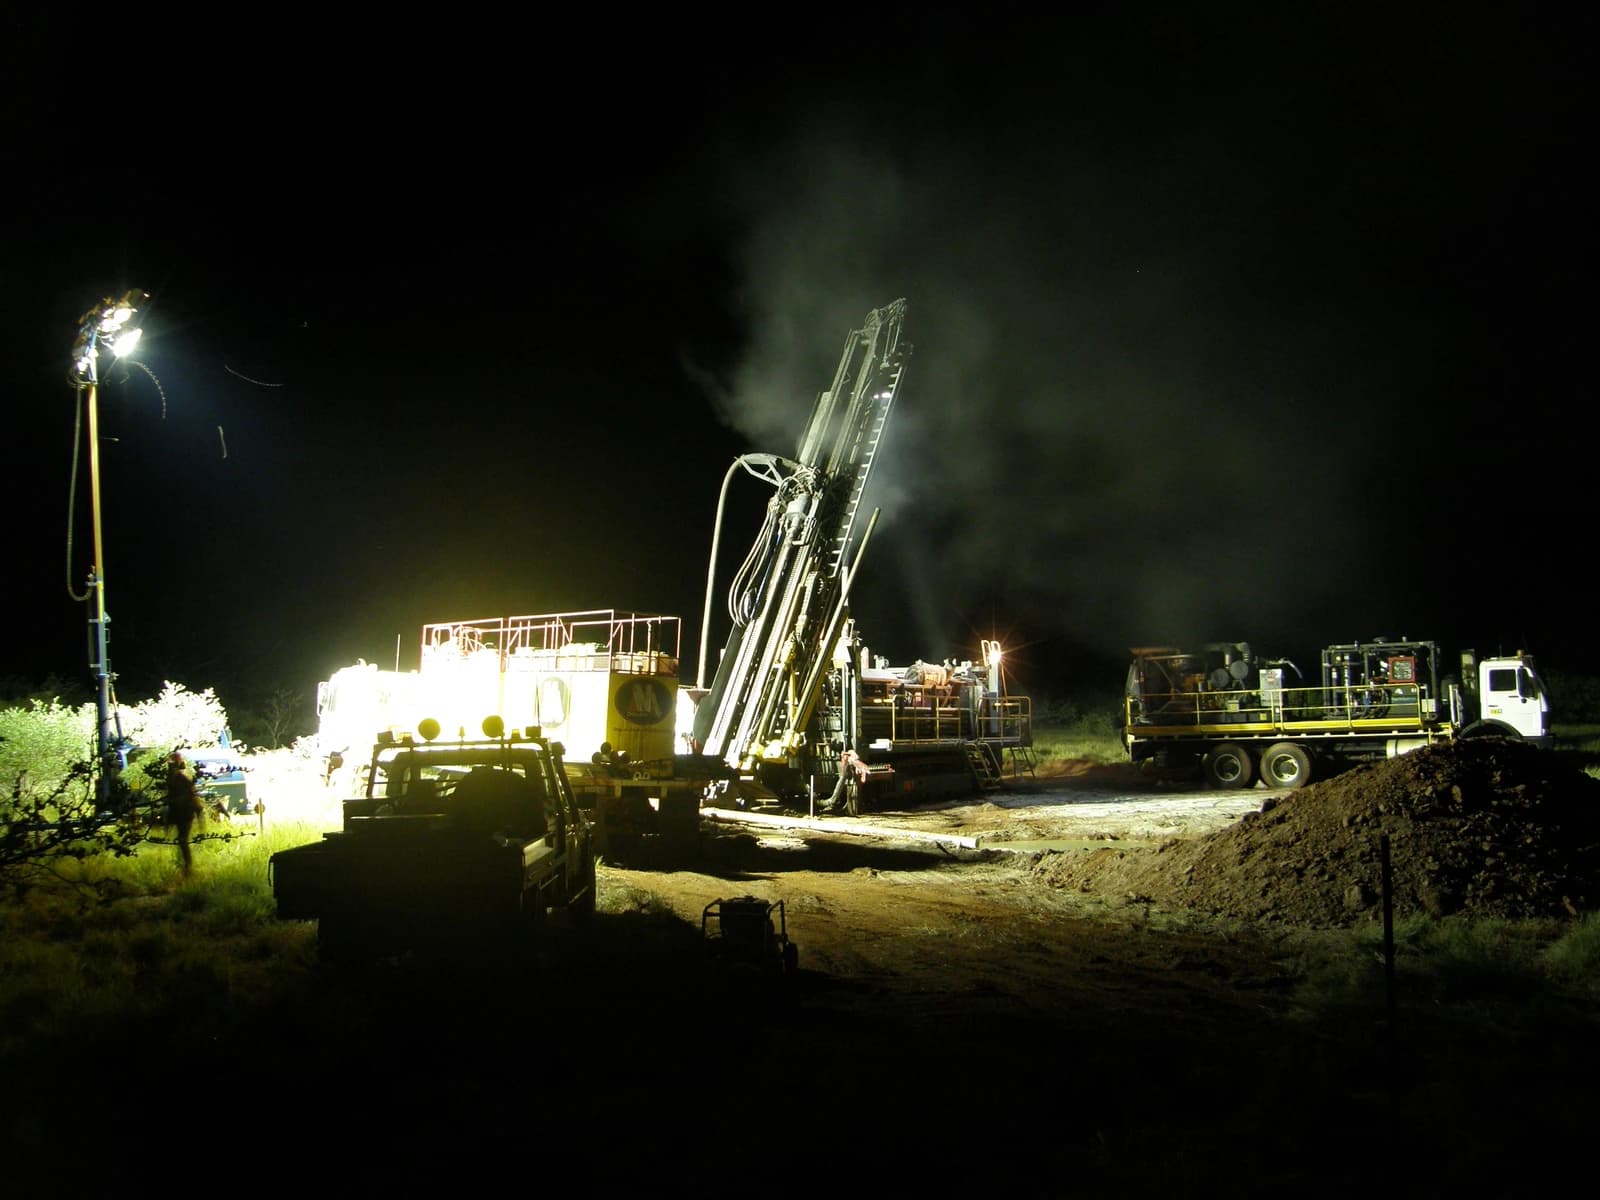
Alien Metals shares jumped after the miner bought itself more time on debt and said renewed interest in iron ore could help it unlock value from its Pilbara portfolio.
Alien Metals Extends Debt as Iron Ore Interest Rises
That matters because the company is still trying to turn assets into cash, and in small-cap miners, financing flexibility is often the difference between a project staying alive and being forced into a distressed sale. Alien said it extended repayment on its convertible loan with Bennelong Resource Capital from Dec. 31 to Sept. 30, while also increasing available drawdown under tranches 2 and 3 to A$1 million. Investors usually like that kind of breathing room when a company is still searching for the best path for its assets.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 10, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
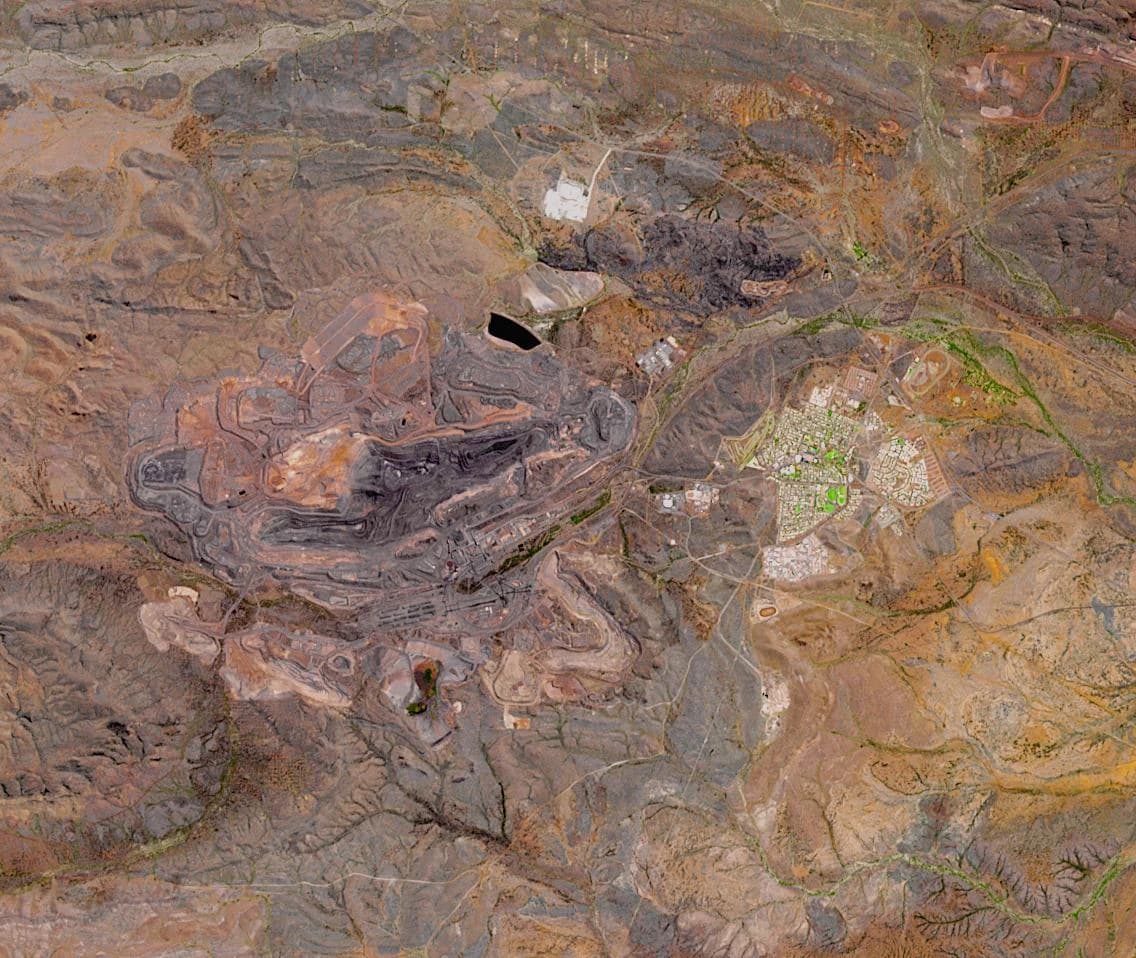
The stock rose 23% in London to 0.080 pence, though it remains down 50% over the past year. That rebound looks less like a full rerating than a market response to two things at once: a lighter near-term funding overhang and a better backdrop for iron ore. Alien said it is reviewing the commercial route for its Pilbara iron ore interests, including low-cost technical work, joint ventures, strategic partnerships and possible asset sales. It also pointed to a “renewed interest” in those projects as direct-shipping ore prices have climbed to around $100 a tonne.
For investors, the key question is whether that pricing is enough to attract a partner or buyer. Iron ore is still a cyclical business, and smaller developers often need a strong commodity backdrop to monetize deposits without taking on too much dilution or debt. A firmer price environment can revive talks around farm-ins, development partnerships and outright divestments, especially for explorers that lack the balance sheet to build mines on their own.
Alien’s update also hints at optionality beyond iron ore. Its Munni Munni platinum group metals and copper project in Western Australia contains a historical resource of about 2.2 million ounces of platinum group metals and gold, though it has not yet been declared under the JORC 2012 code and is expected later this quarter. In silver, partner West Coast Silver is still drilling and studying future development routes at Elizabeth Hill. For long-term investors, that means Alien is still very much a story about asset monetization rather than production growth.
The bigger narrative here is simple: when commodity prices improve, capital gets more willing. For a cash-strapped junior miner, that can open the door to survival, restructuring and maybe even a meaningful exit. If iron ore stays firm and Alien can use the next few months to secure a partner or sale, the recent share move may prove justified. For now, it’s one to watch closely rather than chase blindly.
| Entity | Gains | Losses |
|---|---|---|
| Alien Metals | ▲More funding flexibility | ▼Ongoing dilution risk |
| Bennelong Resource Capital | ▲Extended loan exposure | ▼Slower repayment |
| Potential JV/buyout partners | ▲Lower-entry asset options | ▼Commodity price risk |
| Existing shareholders | ▲Higher chance of asset monetization | ▼Volatility if talks stall |