Amazon investors are getting a blunt reminder that the stock’s next leg higher may depend less on retail and more on whether AI and cloud spending can keep compounding into 2027.
Amazon target raised to $500 by Morgan Stanley
Morgan Stanley raised its price target on Amazon to $500 by the end of 2027, a level that implies the shares could almost double from current prices. The call matters because it reframes Amazon as a long-duration earnings story rather than a near-term consumer trade, with Wall Street betting that AI-powered shopping tools and continued growth at Amazon Web Services can sustain profit expansion even after a volatile run in the shares.
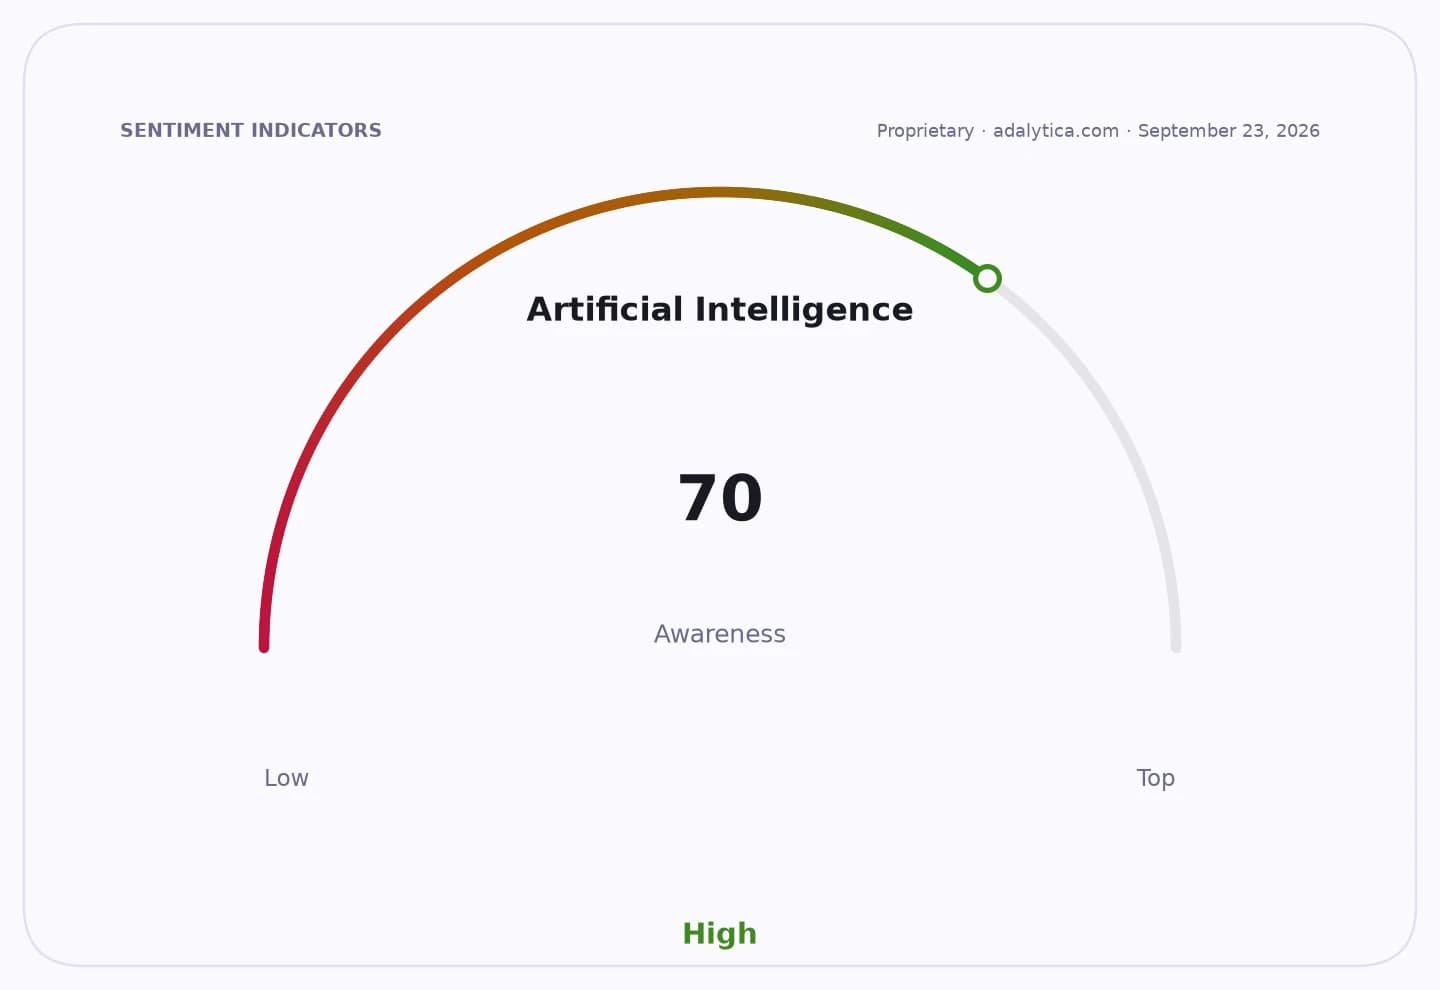
Sentiment IndicatorsⓘProprietary · adalytica.com · September 5, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The argument also lands at a useful moment for investors. Amazon stock closed at $258.51 on Friday, leaving it above both its 50-day moving average of $253.95 and its 200-day moving average of $239.12, but still well below the kind of momentum peak that tends to draw broad ownership. Technical indicators are mixed rather than euphoric: the 14-day RSI at 47.2 points to a neutral setup, while MACD remains positive but has narrowed, suggesting the recent advance has paused rather than broken out.
That balance helps explain why Cramer’s message, and Morgan Stanley’s target, matter now. Amazon is no longer being valued simply as a retail platform with optional cloud upside. At roughly 20 times earnings, the stock is being treated as a GARP name — growth at a reasonable price — where the burden is on management to prove that AI can lift shopping conversion, advertising and logistics efficiency while AWS keeps growing into a more mature cloud market. If that happens, the multiple can hold or widen. If it does not, the valuation has less room to absorb disappointment than in earlier years.
The bull case is straightforward. Amazon has two engines that can still scale: retail infrastructure that can be monetized more efficiently with AI, and AWS, which remains one of the industry’s central beneficiaries of enterprise cloud and AI demand. If AI improves product discovery, personalization and merchant tools, it can deepen customer engagement across the marketplace while supporting higher-margin revenue streams. For AWS, the key question is whether AI workloads and broader cloud migration offset the rising capital intensity of the business.
The bear case is equally clear. Amazon is expensive enough that investors will demand evidence, not just optionality. Cloud competition remains intense, consumer spending is uneven, and the company’s ongoing investment cycle can pressure free cash flow in the short run. After the stock’s large swings over the past year, including periods when it traded far above and below its moving averages, the market is signaling that execution matters more than narrative.
For investors, the takeaway is that Amazon’s valuation now hinges on the pace of monetization in AI and AWS rather than on the usual e-commerce cycle. Morgan Stanley’s $500 target is not just an upgrade; it is a statement that Amazon’s mix of scale, data and infrastructure could still justify a much higher earnings multiple if management converts AI investment into tangible operating leverage.
The next catalysts will be AWS growth trends, signs of AI adoption across the shopping platform and whether Amazon can keep margins expanding without sacrificing growth. If those pieces line up, the case for a substantially higher share price strengthens. If they stall, the stock may continue to trade more like a large-cap compounder than a breakout growth name.
| Entity | Gains | Losses |
|---|---|---|
| Amazon bulls | ▲Higher upside target | ▼Need execution to justify it |
| Amazon bears | ▲Risk of valuation reset | ▼Upgraded growth narrative |
| AWS | ▲AI demand tailwind | ▼Cloud competition pressure |
| Retail rivals | ▲Harder to match scale | ▼Amazon’s efficiency gains |