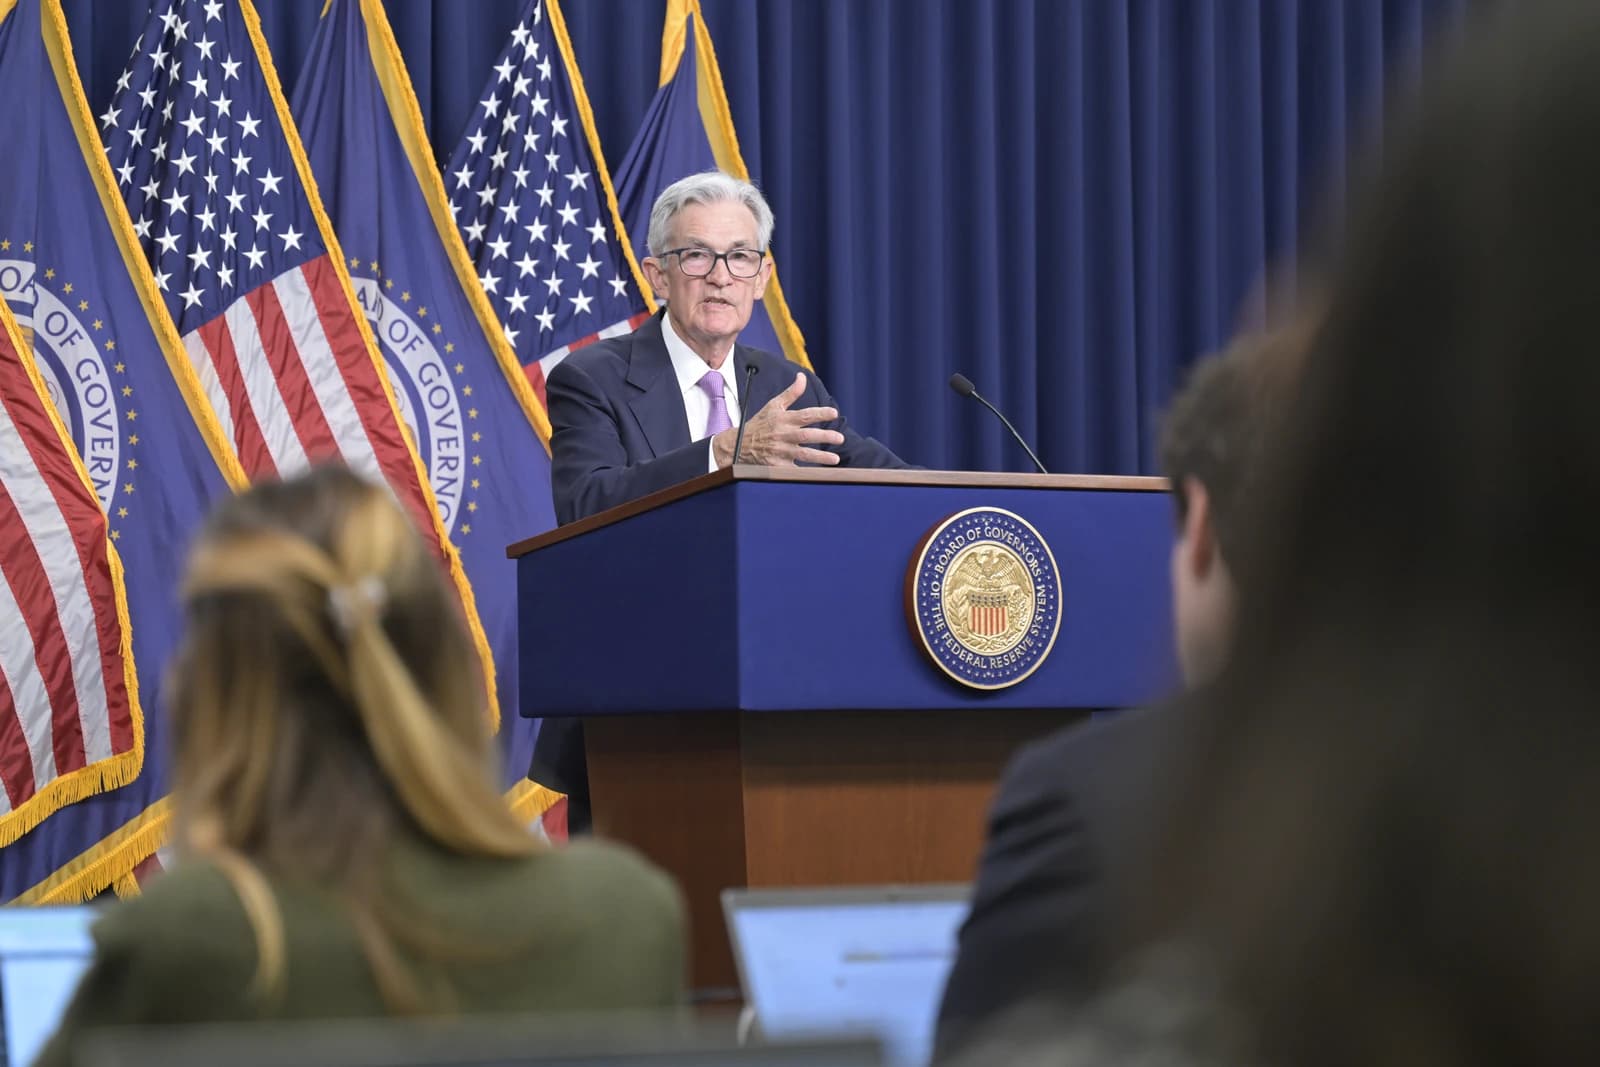
Argentina may get a reprieve in global financing conditions after a sharp slowdown in US hiring dented bets on another Federal Reserve rate increase, easing some of the pressure that has been pushing emerging-market assets lower.
Argentina Bonds May Benefit From Softer Fed Outlook
The US economy added just 29,000 jobs in September, far below the roughly 80,000 the market had expected, while the unemployment rate ticked up to 4.2%. The weaker labor reading undercuts the case for a further hike at the Fed’s next meeting and helped shift attention away from a tightening cycle that had driven the 10-year Treasury yield toward 5.2%.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 4, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That matters directly for Argentina, where sovereign bonds have been under strain and the country risk premium has climbed to 600 basis points. Higher US yields typically pull capital toward safer dollar assets and force investors to demand a bigger return to hold riskier debt, making it harder for countries like Argentina to refinance obligations or regain market access.
The Argentine sovereign curve has been especially vulnerable in recent weeks as Treasury yields rose and investors marked up the cost of carrying emerging-market exposure. If the Fed pauses, or even sounds less hawkish, US yields could ease and reduce the discount applied to Argentine bonds, giving local assets room to recover.
Hawkish vs Dovish Sentiment — 30-day sentimentadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
The move would not solve Argentina’s domestic problems, but it could improve the external backdrop at a critical moment. Lower US borrowing costs would also be supportive for broader emerging markets, including funds such as the iShares MSCI Emerging Markets ETF, while pressuring the dollar and potentially reviving demand for higher-yielding debt.
Even so, the Fed is not boxed in yet. Inflation in the US remains above 3%, core prices are still above the central bank’s 2% goal and policymakers have kept the door open to another move before year-end if price pressures persist.
For now, traders are focusing on whether weak payrolls mark the start of a softer US labor trend or just a temporary pause. A less aggressive Fed would be a near-term tailwind for Argentina’s bonds, but sustained relief will depend on whether inflation cools enough to keep US rates from staying elevated for long.
| Entity | Gains | Losses |
|---|---|---|
| Argentina sovereign bonds | ▲Lower yield pressure | ▼Higher risk premia |
| Emerging-market debt | ▲Better capital flows | ▼Safer US Treasuries |
| Fed doves / pause bettors | ▲Stronger case for caution | ▼Hike expectations |
| US Treasury yields | ▲Potential easing | ▼Continued hawkish pricing |