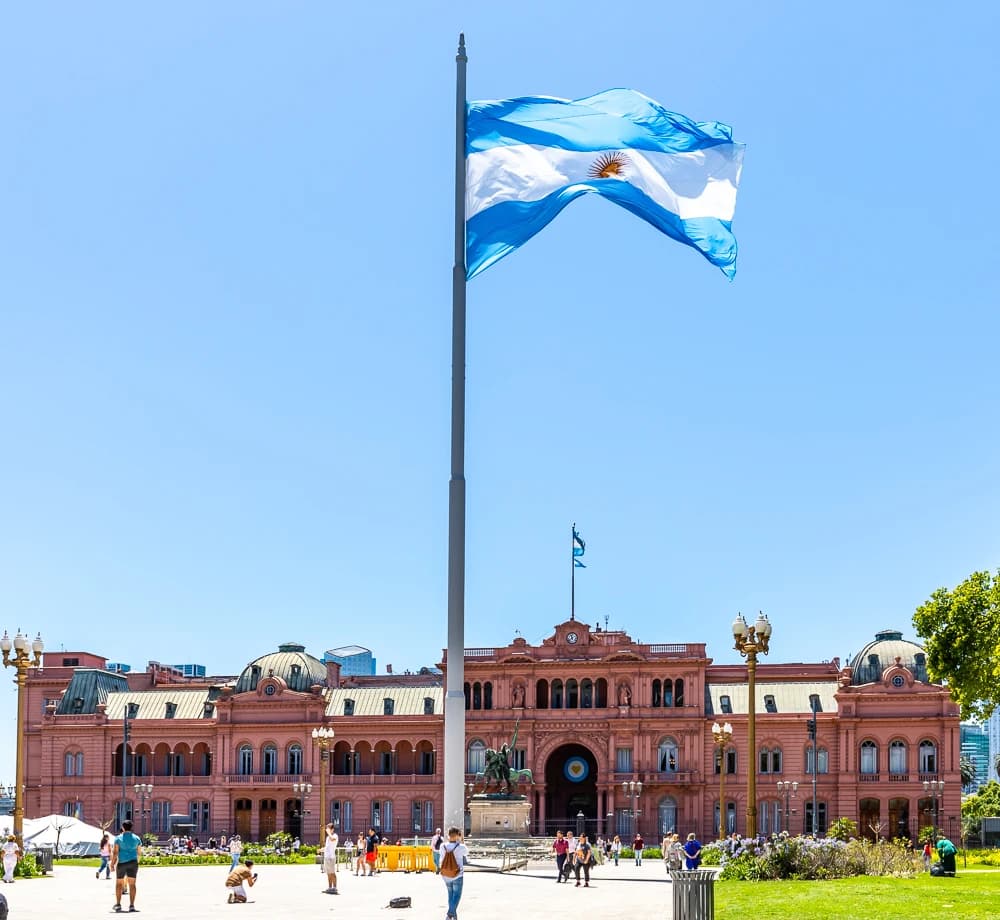
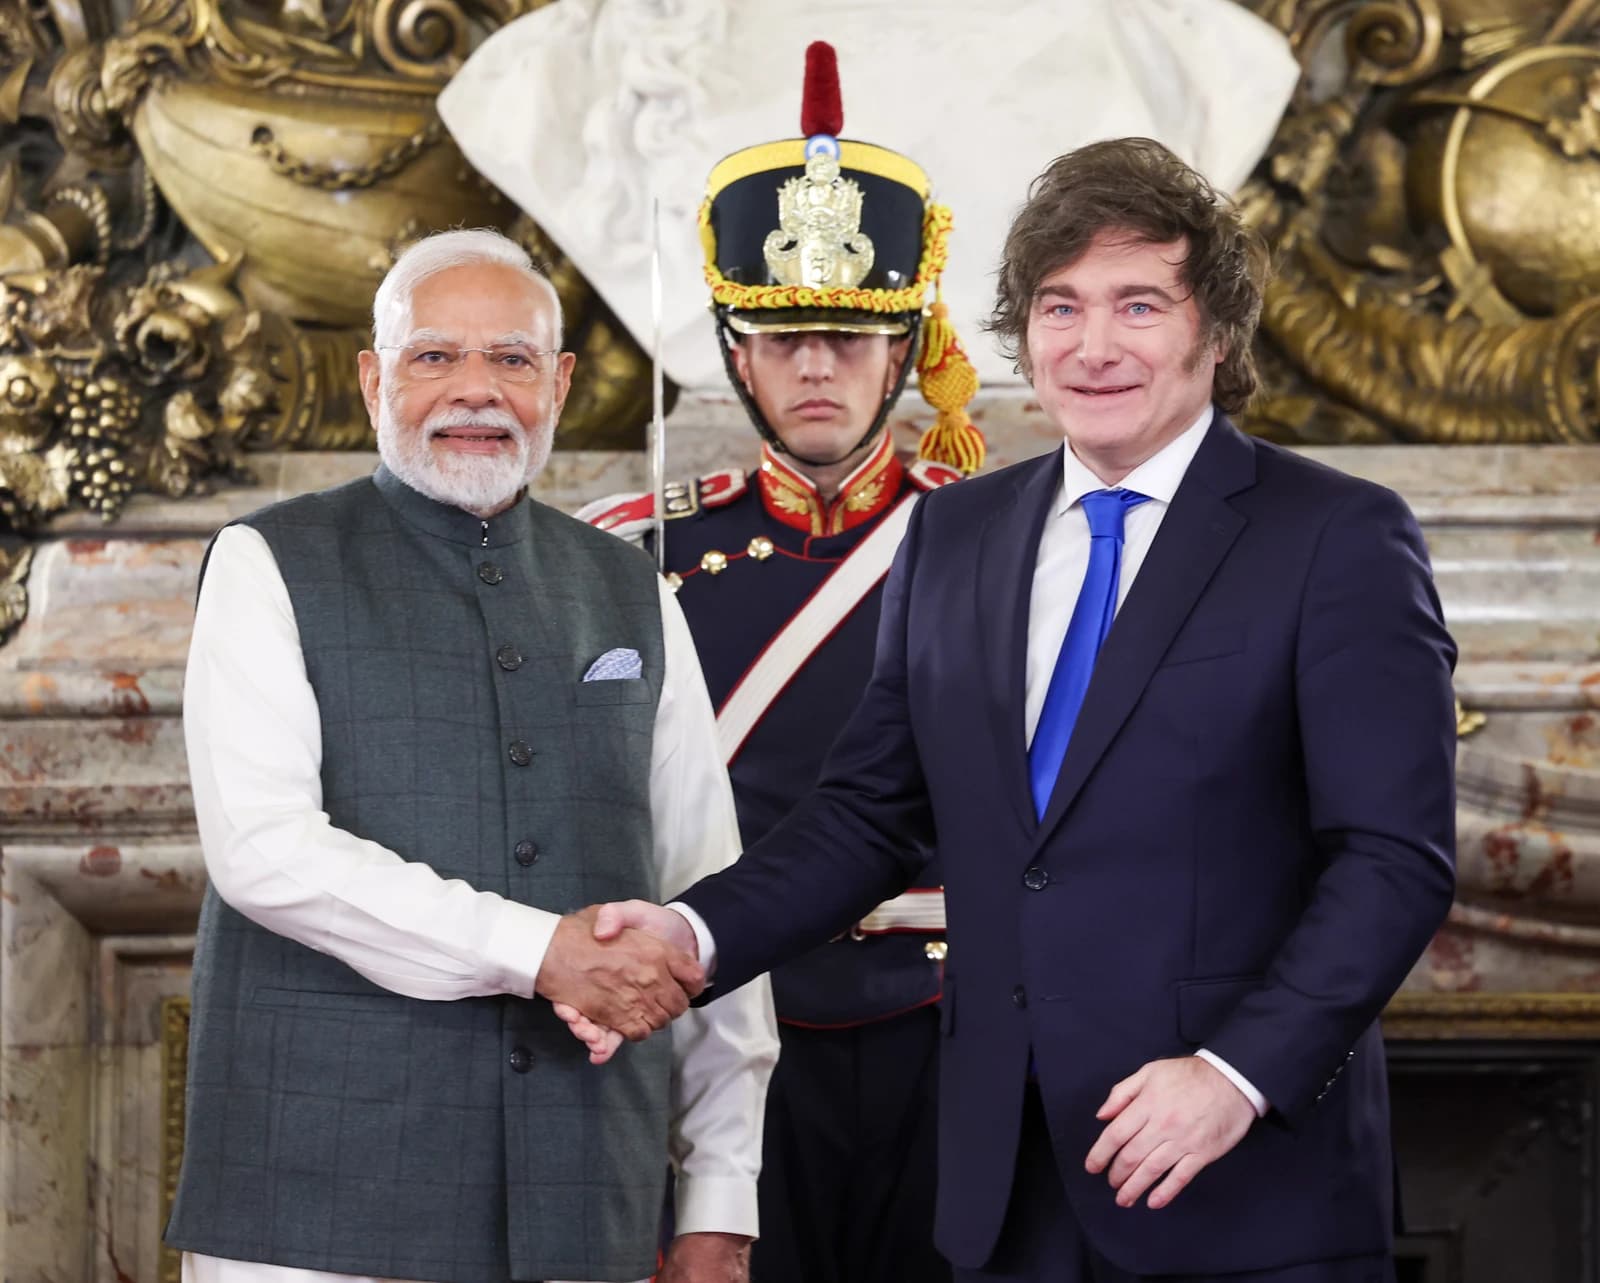
Argentina’s President Javier Milei is leaning on a fast-improving energy and trade balance to argue that the country will have enough hard currency to weather external shocks without another balance-of-payments crisis.
Argentina Energy Surplus Could Lift Peso
That is economically important because Argentina’s chronic shortage of dollars has long been the binding constraint on growth, inflation and market confidence. If the country really is moving from dollar scarcity to dollar surplus, it would reduce pressure on the peso, ease import bottlenecks and give policymakers more room to manage reserve accumulation without choking activity.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 28, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Speaking in New York after his address to the United Nations, Milei said Argentina’s trade balance will rise to about $25 billion this year, helped by a swing in the energy account from a $5 billion deficit to a surplus of $10 billion or more. His message was that a shock that once would have drained foreign exchange — such as a spike in oil prices — could now be partly offset by stronger export flows from the real economy.
The claim matters because it goes to the heart of Milei’s macro strategy: use energy exports, mining and other real-economy inflows to rebuild external strength rather than rely on financial engineering. Economy Minister Luis Caputo reinforced that view, saying investment opportunities are building in energy, critical minerals, food and human capital, and that some sizeable projects have not yet been announced.
For investors, the implication is two-sided. A larger current-account and trade surplus would be constructive for sovereign credit, local-currency assets and energy producers such as YPF, which have already benefited from the country’s hydrocarbons turnaround. The peso also tends to react to the supply of dollars, and the recent move in the currency shows how quickly the market can price in better external liquidity. ARS=X has pushed higher in recent sessions, while YPF has held near recent gains despite broader volatility.
But the bullish case still depends on execution. Argentina’s recent economic data remain fragile, and lenders such as J.P. Morgan have cut growth forecasts and warned of technical recession as a stronger peso weighs on activity. If dollar inflows rise faster than domestic demand, the central bank may face the familiar trade-off between defending the currency, sterilizing liquidity and preserving growth. That tension — abundance of dollars, but still a weak economy — is the narrative investors should watch.
For now, Milei is trying to reframe Argentina’s external position from vulnerability to strength. If the energy surplus and export pipeline are real, it would mark one of the most important shifts in the country’s macro story in years. If they disappoint, the old shortage of dollars will return quickly.
| Entity | Gains | Losses |
|---|---|---|
| Argentina’s government | ▲More external funding | ▼Pressure to prove delivery |
| Energy exporters such as YPF | ▲Higher dollar revenue | ▼Domestic tariff and policy risk |
| Peso and reserve holders | ▲Better FX support | ▼Less upside if sterilization tightens liquidity |
| Importers and consumers | ▲Easier access to dollars | ▼Inflation if policy missteps persist |