Argentina’s peso funds tied to inflation-linked debt have been the best performers this year, underscoring how persistent price pressure is still driving investors toward instruments that protect real returns.
Argentina peso funds lead returns on inflation-linked debt
The standout has been Consultatio One Ahorro B, managed by One618, which returned about 31% in pesos through late August, according to an IEB report. Among money market funds, Ciclo Nova Ahorro Plus rose 19%, while Galileo Ahorro B led peso fixed-income funds with nearly 25%. Dollar-linked MAF Renta Fija Cobertura B gained 15%, but lagged the inflation-linked cohort.
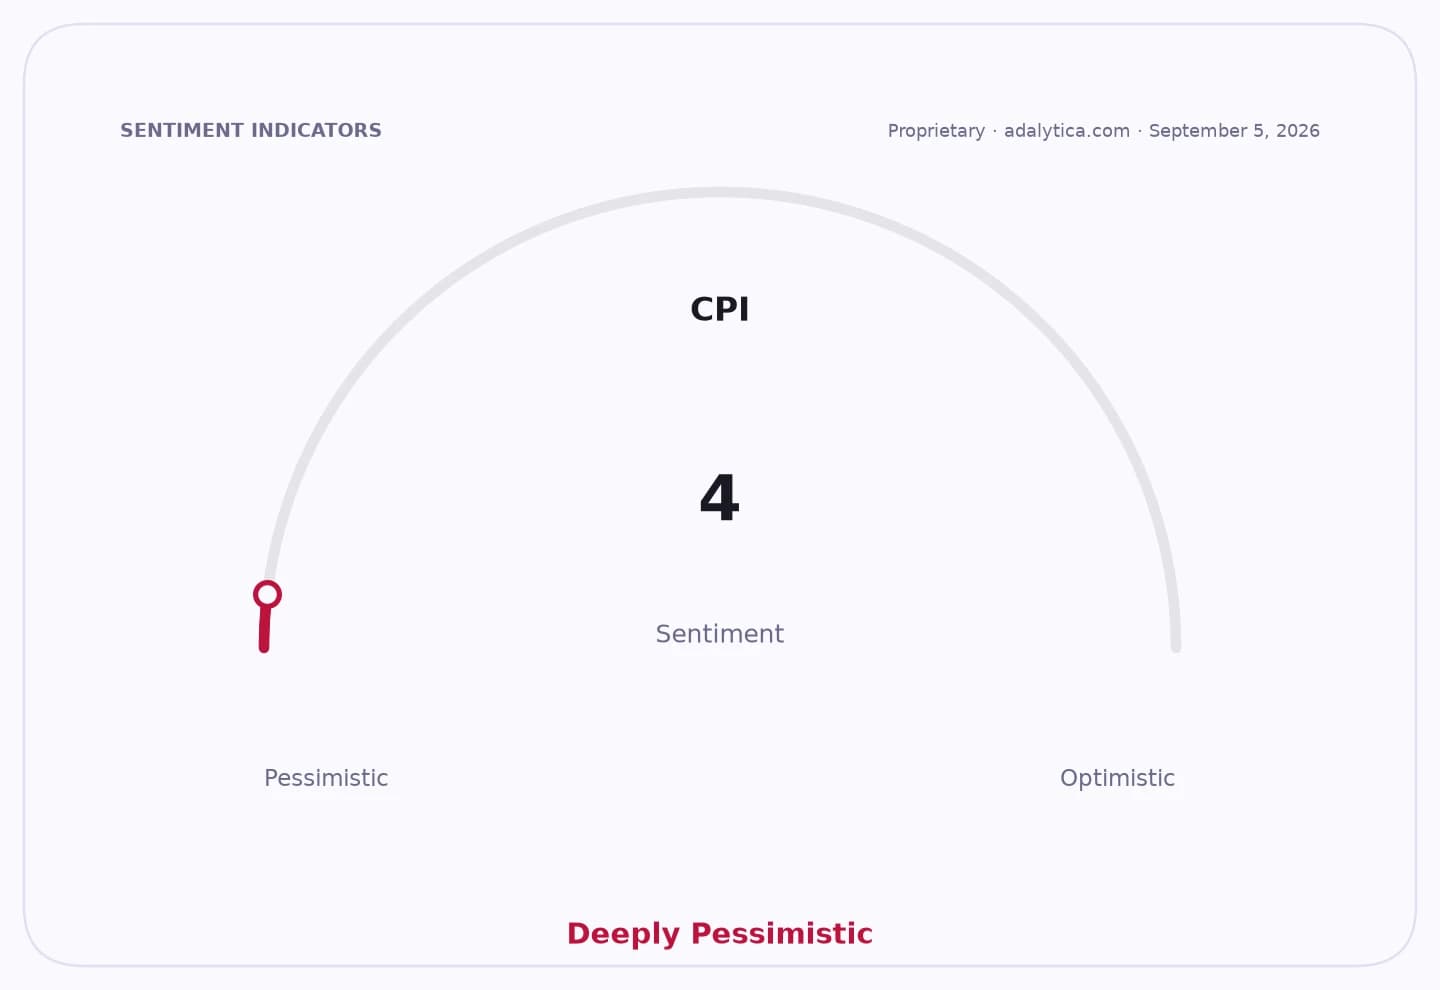
Sentiment IndicatorsⓘProprietary · adalytica.com · September 5, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That outperformance matters because it shows the Argentine fund industry is still being shaped less by risk appetite than by the need to preserve purchasing power. Portfolio Personal Inversiones’ Valentina Heredia said the rise of CER funds reflects both net inflows and the returns generated by the assets they hold. In a market where inflation remains elevated, funds indexed to consumer prices can deliver the rare combination of liquidity and real yield, making them a natural parking place for institutional and retail cash.
The scale of that rotation is becoming material for the broader industry. Tobias Sanchez, portfolio manager at Cocos Capital, said peso-only funds now manage about 70 trillion pesos, or just over 62% of the industry, and have attracted nearly 12 trillion pesos in net subscriptions this year. Money market products still dominate, with roughly 75% of peso fund assets and 7.1 trillion pesos in inflows so far this year, but the better returns have been in longer-duration peso strategies. CER funds are up 26.5% this year, discretionary peso funds 21.4% and T+1 funds 20.2%, compared with 19.3% inflation and roughly 10% returns in dollar funds.
For investors, the message is straightforward: inflation hedges remain the main source of alpha in local fixed income, and fund flows are rewarding managers who can position early in the duration and index-linked segments. The bull case is that if inflation moderates without a sharp dislocation in rates, CER assets can continue to offer attractive real returns. The bear case is that any policy mistake, FX shock or renewed acceleration in prices could lift volatility and punish funds that have stretched for duration.
The next test is whether the recent dominance of CER products persists as inflation expectations and monetary policy evolve. If price pressures remain sticky, peso funds linked to inflation should keep drawing assets; if disinflation gains traction, money market funds may regain the lead as investors prioritise capital preservation over yield pickup.
| Entity | Gains | Losses |
|---|---|---|
| CER funds | ▲Real-return demand | ▼Dollar funds |
| One618 / Consultatio One Ahorro B | ▲Top peso-fund returns | ▼Lower-yield peers |
| Money market funds | ▲Liquidity inflows | ▼Longer-duration caution |
| Investors hedging inflation | ▲Purchasing-power protection | ▼Unhedged peso savers |