A disclosed apartment in Arinje with 14.4 million drams of income against a 22.5 million-dram mortgage obligation is drawing attention because it highlights the gap between reported earnings and debt load — a ratio that investors, lenders and voters alike are increasingly sensitive to in a higher-rate, higher-scrutiny environment.
Armenian Mortgage Disclosure Raises Leverage Concerns
The significance is less about the apartment itself than what the numbers imply about leverage and repayment capacity. A mortgage burden that exceeds annual income points to stretched household finances, especially if the debt is the kind that requires steady cash flow rather than asset gains to service. In an economy where credit growth and property values have helped support consumption, disclosures like this also raise broader questions about how resilient borrowers are if financing conditions tighten.
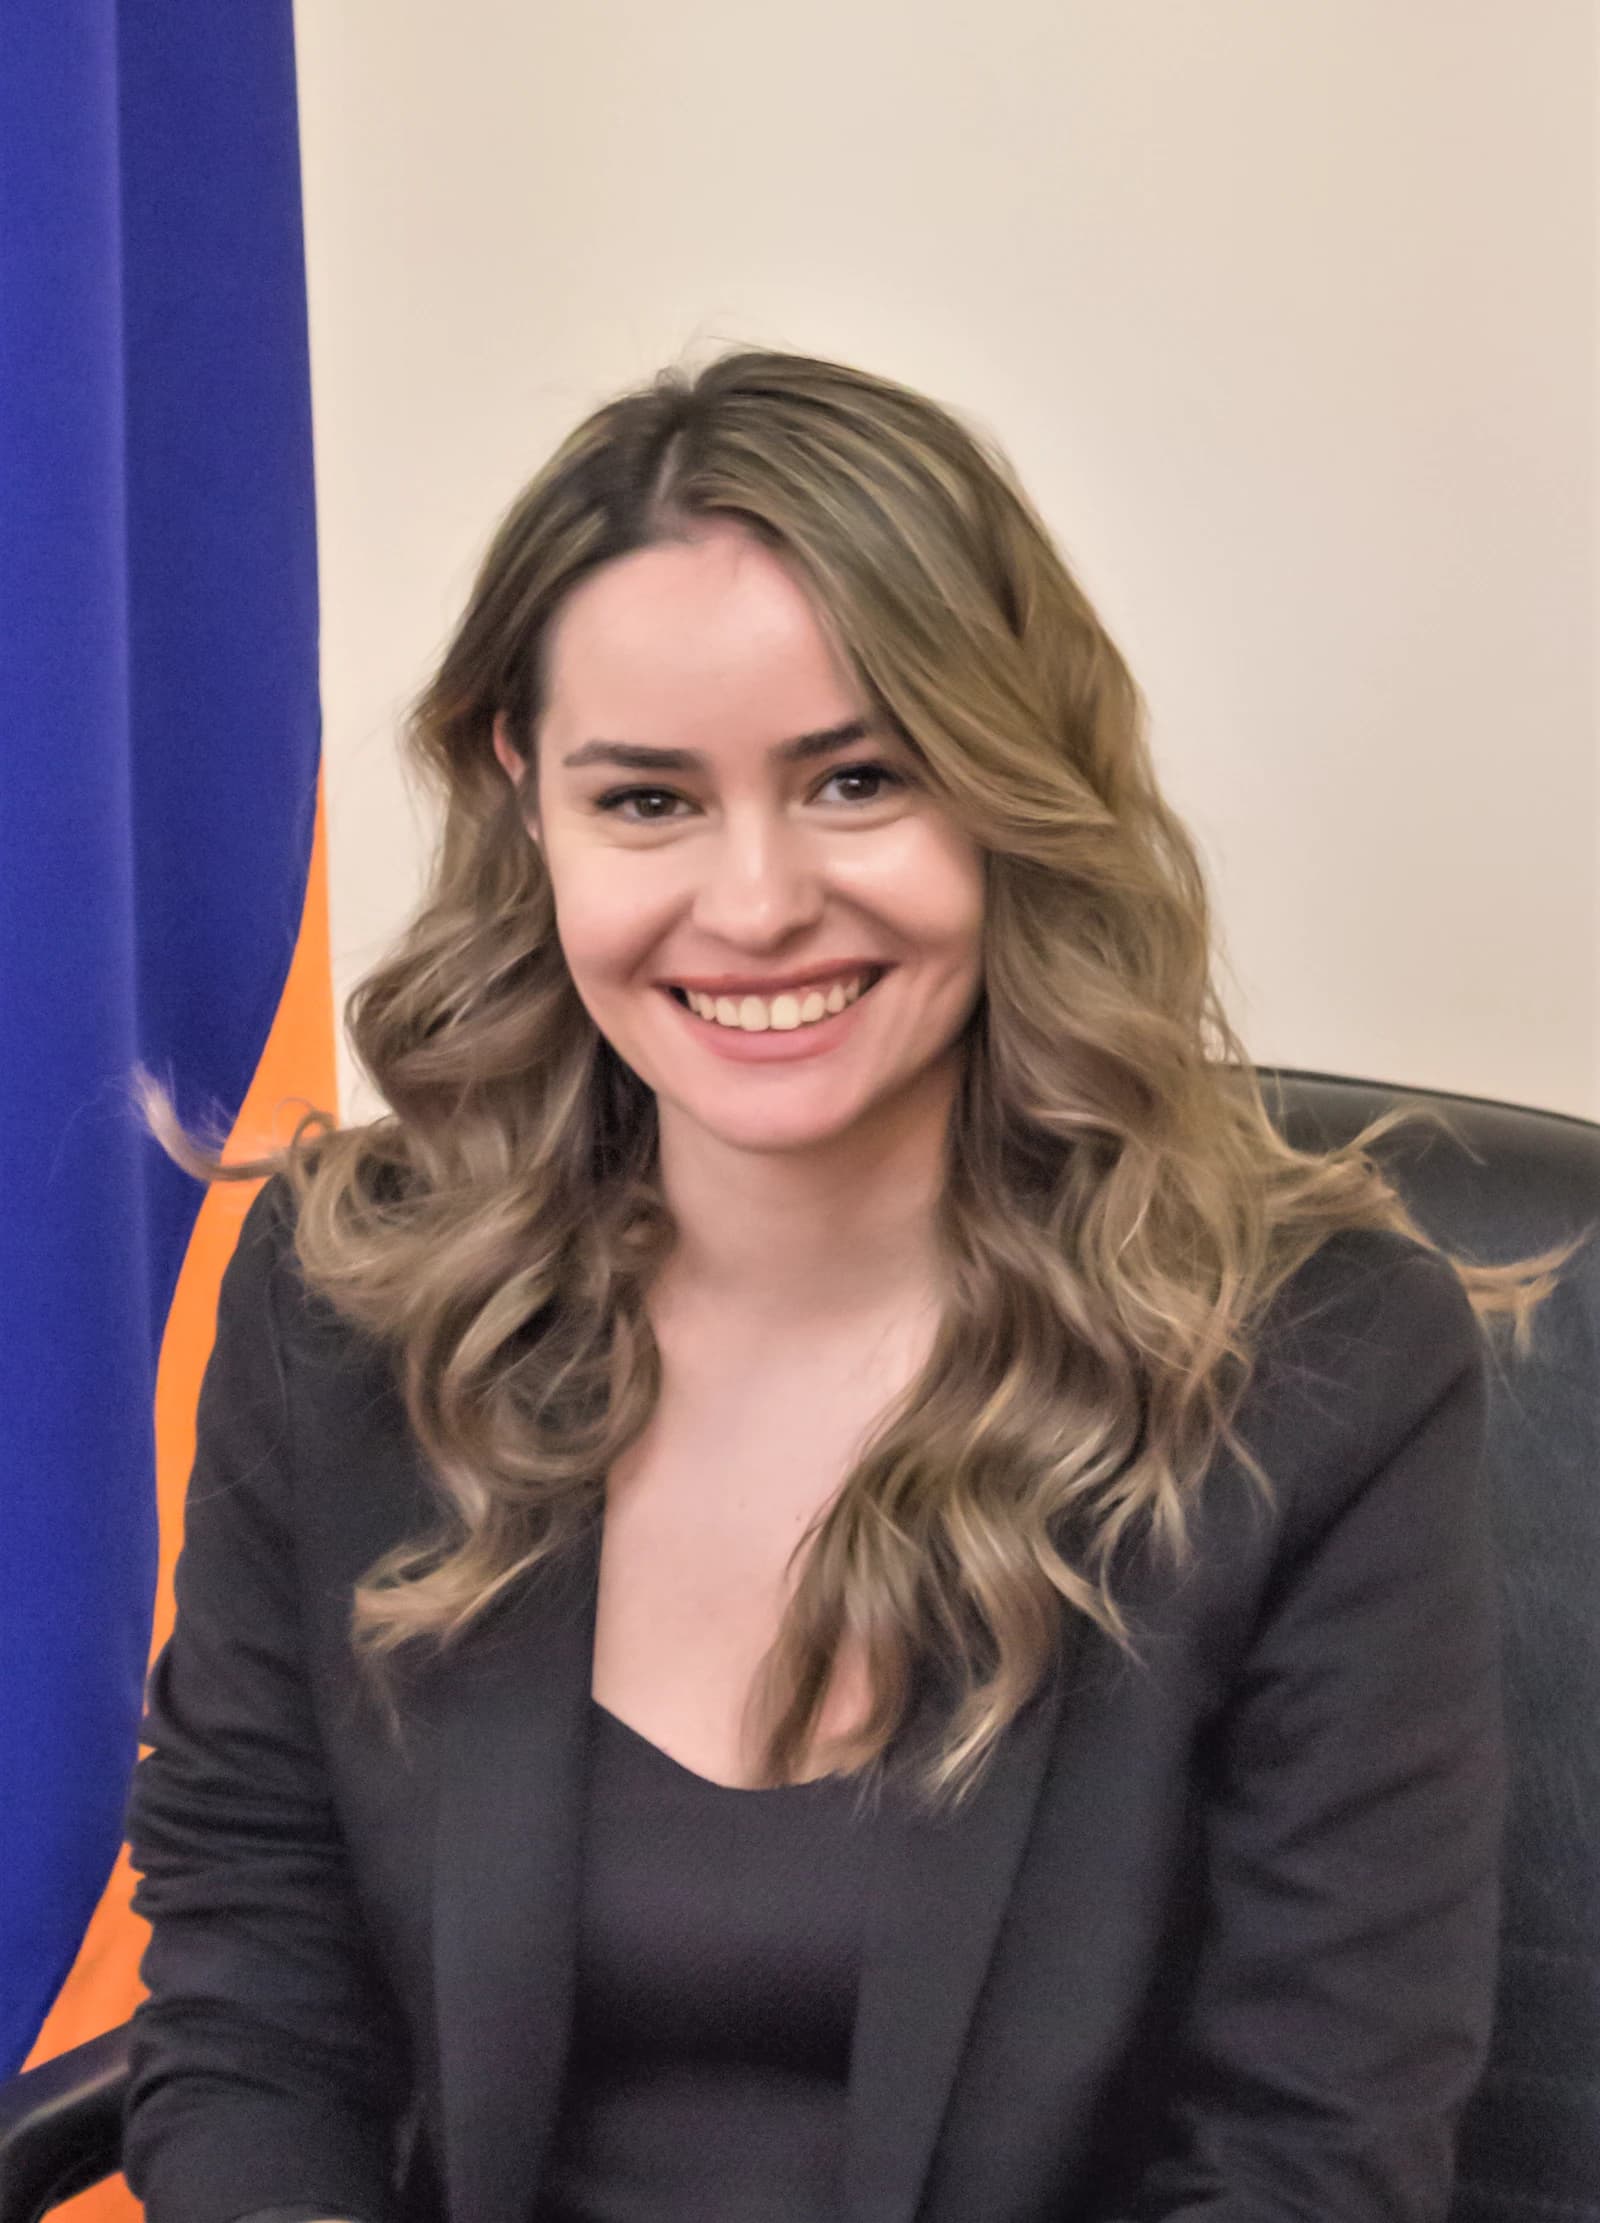
For Sona Ghazaryan, identified as a member of the Civil Contract party, the disclosure carries a political as well as financial cost. Public officials are under pressure to demonstrate that their declared assets and liabilities are consistent with the standards they expect others to follow. Any mismatch between income and obligations can become a proxy for governance concerns, even when the debt is legitimate and fully disclosed.
For investors and lenders, the more relevant takeaway is that Armenia’s household balance sheets may be more fragile than headline growth figures suggest. Mortgage exposure can support construction, banks and consumer demand when property prices are rising, but it becomes a vulnerability if wage growth slows or borrowing costs stay elevated. The case also illustrates why transparency rules matter: the market cannot price risk well if debt loads are hidden or underestimated.
The broader narrative is one of leverage under pressure — in personal finances, in politics and in the credit system. If more disclosures reveal similar income-to-debt gaps, it would reinforce the case for caution on consumer credit quality and housing demand. If, instead, borrowers are able to service and refinance such obligations, it would suggest the housing market remains supported despite the strain. Either way, the numbers are likely to keep debt and disclosure standards in focus.
| Entity | Gains | Losses |
|---|---|---|
| Mortgage lenders | ▲Interest income | ▼Credit-risk exposure |
| Property owners | ▲Access to financing | ▼Higher leverage burden |
| Civil Contract / officials | ▲Transparency credibility | ▼Political scrutiny |
| Banks / housing market | ▲Loan demand | ▼Stress if repayments weaken |
