Hanmi Semiconductor’s first shipment of its FC Bonder 75 marks a real commercial entry into one of the fastest-growing bottlenecks in AI computing: advanced packaging.
Hanmi Semiconductor Ships FC Bonder 75
That matters because the AI boom is no longer just a contest over chips, but over how many of those chips can be packed together, wired and cooled fast enough to meet explosive demand. The market has fixated on GPUs and memory, yet the hidden constraint is assembly capacity for 2.5D and high-density packaging, where equipment suppliers can become the toll roads of the AI capex cycle.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 26, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Hanmi’s move gives it a foothold in a market that should keep expanding as AI servers, high-bandwidth memory and accelerator clusters push manufacturers deeper into advanced packaging. The company has been building around thermal compression and bonding tools, and the FC Bonder 75 is aimed at next-generation AI semiconductors that require tighter alignment and higher precision than legacy logic chips.
The timing is important. Samsung Electronics and SK Hynix remain central to Korea’s memory and semiconductor ecosystem, but the bigger investment story is shifting toward the equipment layer that sells into the AI build-out regardless of which chip designer wins. That is where asymmetric returns often show up first: suppliers with qualified tools, sticky customer relationships and recurring upgrade demand can capture more durable margins than the headline chipmakers themselves.
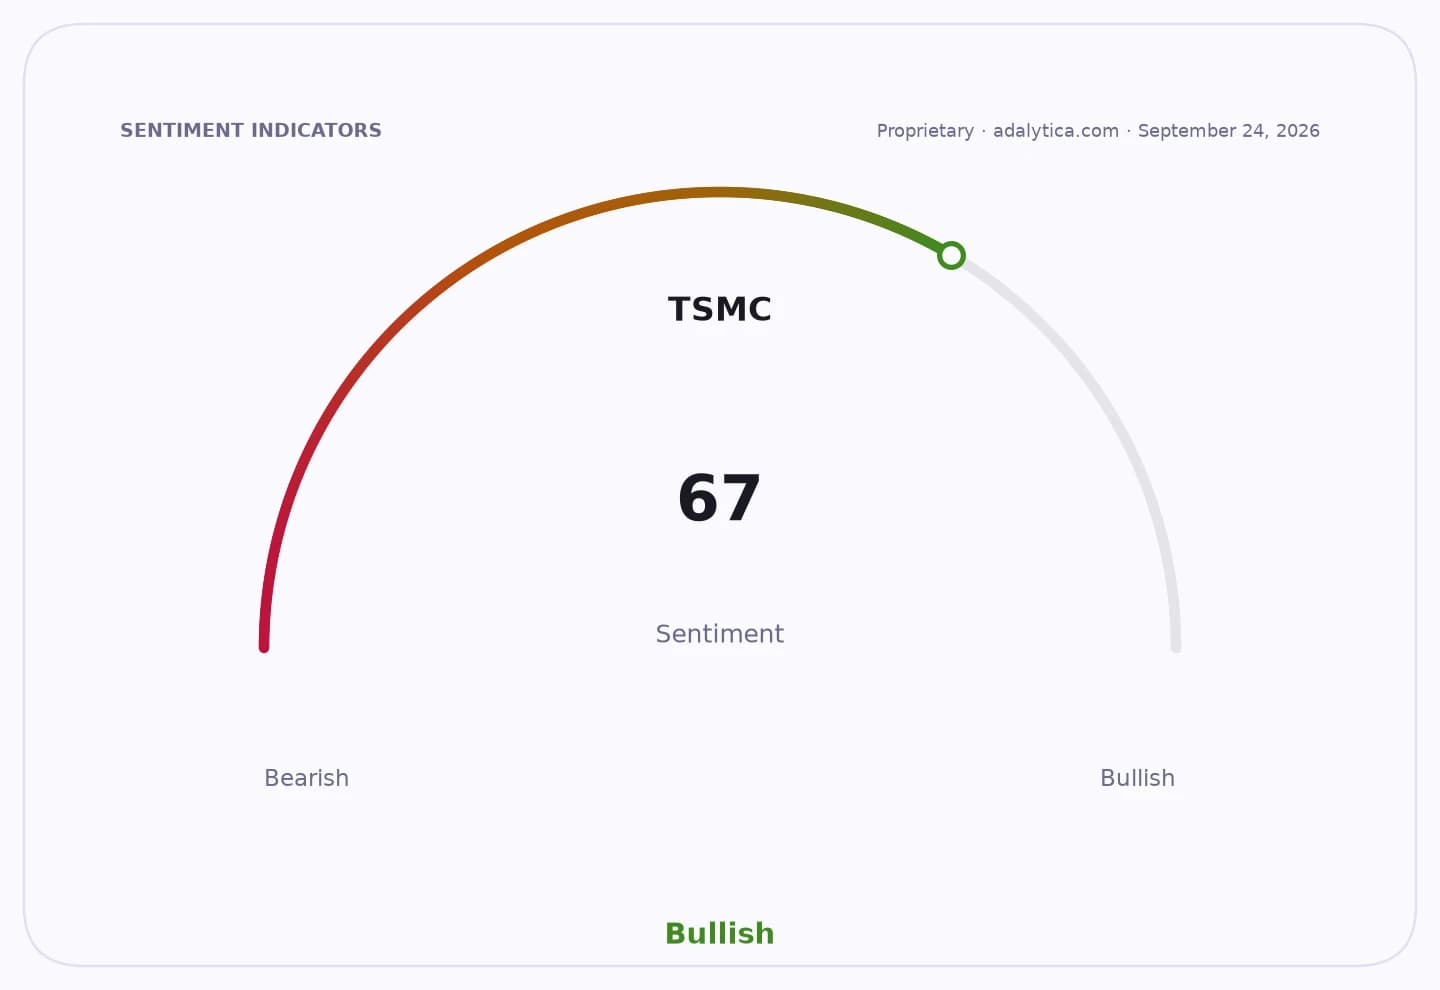
Investor sentiment around the broader AI trade remains strong. Adalytica’s TSMC earnings sentiment snapshot is in greed territory, underscoring how much confidence remains in the foundry and packaging cycle, even as NVIDIA sentiment has softened into fear. That divergence is exactly what investors should watch: enthusiasm is rotating from pure chip names toward the manufacturing infrastructure that makes AI scale possible.
The stock market has already rewarded Korea’s semiconductor complex, with Samsung Electronics and SK Hynix both trading well above their 50-day moving averages and near the upper end of recent ranges. But the next leg of this trade may belong to the less obvious enablers — packaging equipment, materials and precision automation — where order momentum can lag the headline AI cycle before snapping higher.
For investors, the thesis is simple: if AI infrastructure spending remains exponential, then advanced packaging capacity becomes one of the scarcest assets in the chain. Hanmi’s first shipment suggests the company is moving from promise to monetization, and that is when the market starts to rerate suppliers from story stocks into industrial beneficiaries of a multi-year capex wave. The opportunity is not just in AI chips; it is in the equipment that makes them shippable.
| Entity | Gains | Losses |
|---|---|---|
| Hanmi Semiconductor | ▲First revenue milestone | ▼Pure-play chip hype trade |
| AI chipmakers | ▲More packaging capacity | ▼Supply bottlenecks |
| Samsung Electronics | ▲Equipment ecosystem strength | ▼Margin pressure from capex |
| SK Hynix | ▲HBM demand support | ▼Packaging constraints |