ASML is telling investors the AI buildout is still running into a key chokepoint: advanced chipmaking capacity. The Dutch lithography giant lifted its 2026 sales forecast to €43 billion-€45 billion from €36 billion-€40 billion and increased its gross margin outlook to 54%-56% after reporting stronger-than-expected second-quarter results, underscoring that demand for AI chips is translating into more orders for the tools needed to make them.
ASML Raises Outlook on Strong AI Chip Demand
That matters because ASML sits at the center of the semiconductor supply chain. Its extreme ultraviolet, or EUV, systems are indispensable for the most advanced logic chips used in AI accelerators, so a stronger outlook from ASML is one of the clearest reads on whether the AI spending boom is broadening from chip designers into the equipment makers that must expand capacity to support it.
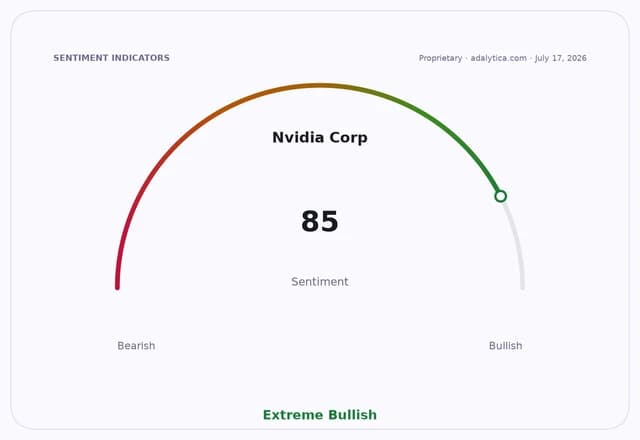
Sentiment IndicatorsⓘProprietary · adalytica.com · July 17, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The company reported second-quarter net sales of €9.3 billion and net income of €2.9 billion, while the raised full-year guidance implies the order pipeline remains healthy even as some parts of the chip sector have worried about timing and supply constraints. ASML shares, which have climbed sharply this year, are still trading below their recent highs after the stock slipped to €1,758.63 on Friday from a close of €1,989.44 on June 30, with the 50-day moving average around €1,718.7 signaling the shares remain technically supported despite recent volatility.
The read-through is broader than ASML. Nvidia, the biggest AI-chip beneficiary, has seen sentiment spike to “Greed” with extreme awareness, while TSMC has also raised sales and spending plans as it races to meet demand for advanced AI processors. Together, the signals point to a supply chain still expanding rather than topping out, with equipment makers, foundries and GPU vendors all benefiting from continued capital spending.
For investors, the key question is whether AI demand keeps forcing foundries and chipmakers to spend aggressively enough to sustain ASML’s order growth into 2027. The next catalyst is whether AI infrastructure spending, customer capex plans and any export-control or macro slowdown interrupt the upgrade cycle.
| Entity | Gains | Losses |
|---|---|---|
| ASML | ▲Higher sales and margin outlook | ▼Capacity constraints ease slowly |
| Nvidia | ▲Strong AI chip demand | ▼Valuation risk if spend slows |
| TSMC | ▲More advanced-node orders | ▼Heavy capex burden |
| Chip buyers | ▲Faster supply expansion | ▼Higher equipment costs |
