JPMorgan has begun coverage of Atalaya Mining with an overweight rating and a 1,330p price target, implying about 30% upside and sending the stock 3.9% higher as investors reprice the copper producer’s growth and valuation story.
Atalaya Mining gains JPMorgan overweight call
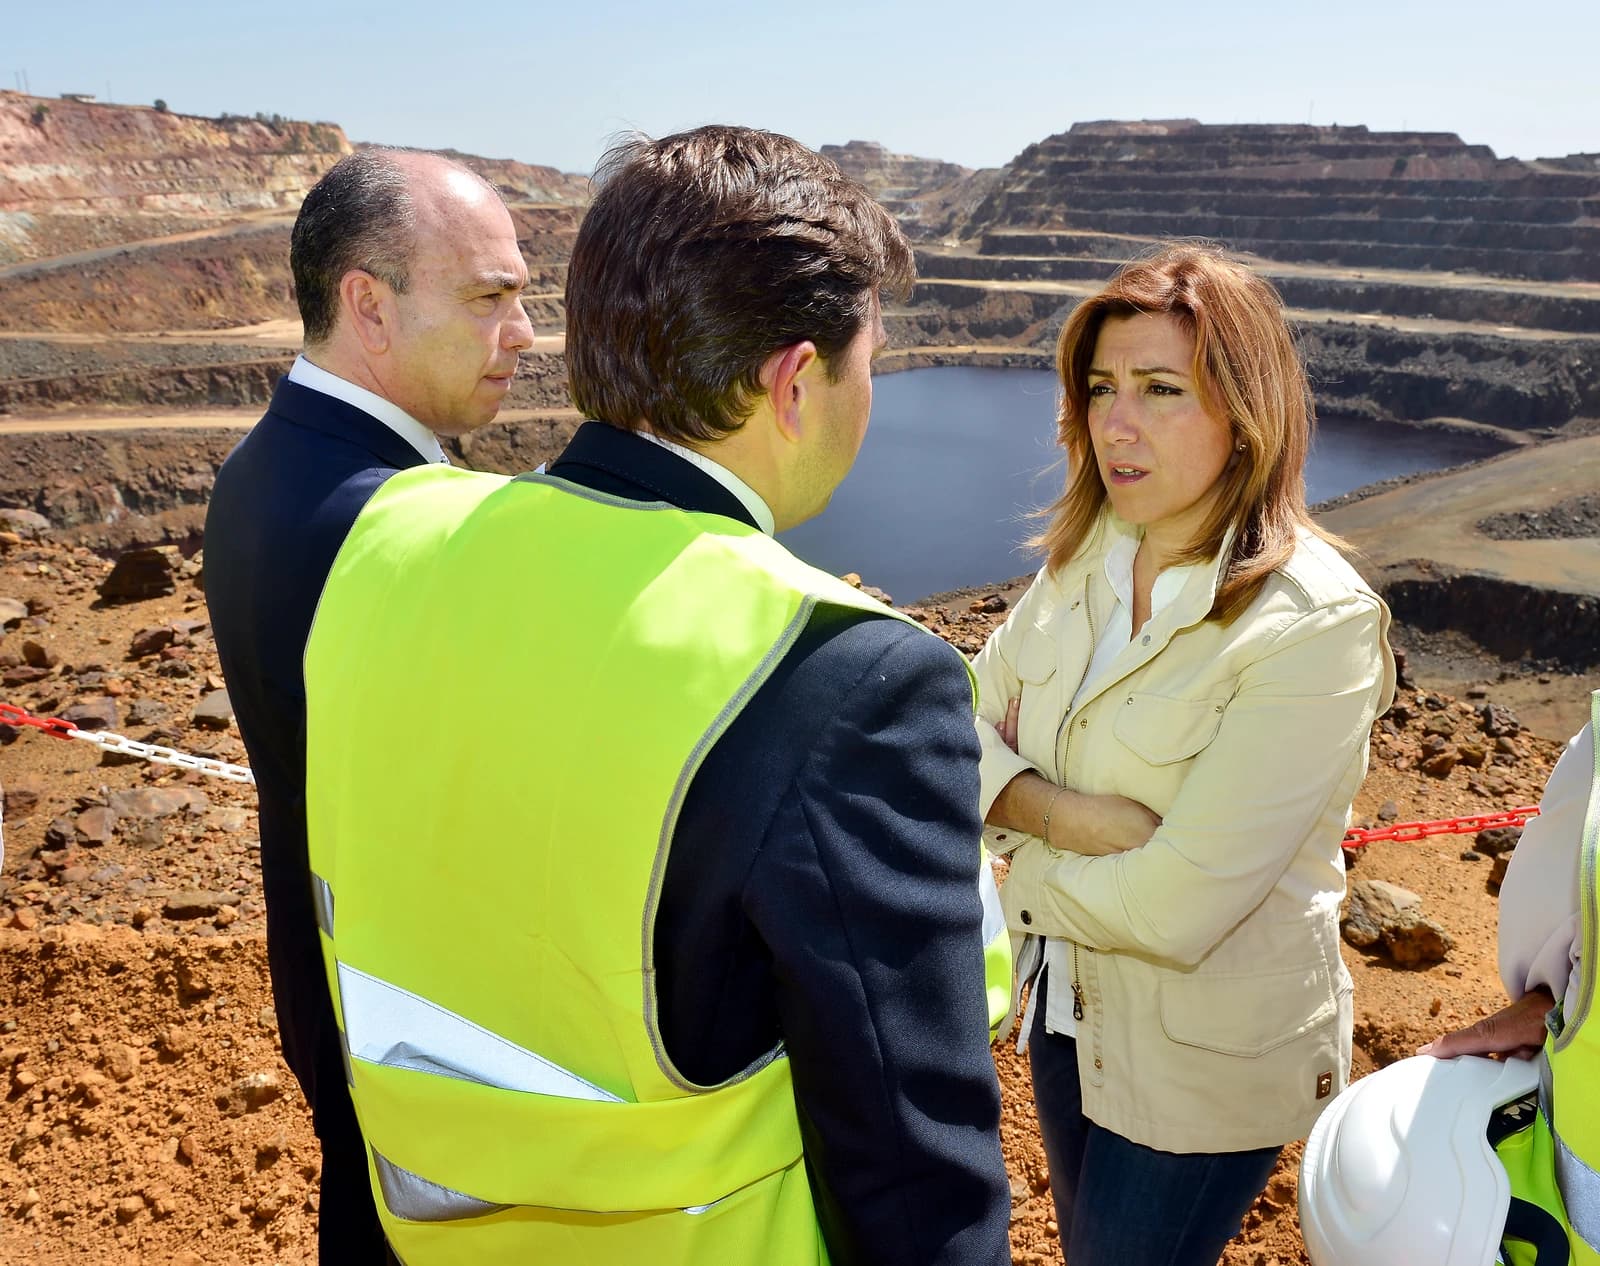
The call matters because Atalaya is one of the few pure-play copper names based in the European Union, giving it direct exposure to a metal that sits at the center of electrification, power grids and Europe’s Critical Raw Materials agenda. That domestic footprint gives the company strategic appeal at a time when policymakers are pressing to secure supply chains closer to home.
JPMorgan said Atalaya’s medium-term plan to lift production to about 100,000 tonnes of copper equivalent a year could come mainly from the greenfield Touro project in Galicia and brownfield expansion work around Riotinto, its historic mine in Andalusia. The bank framed that growth as attractive because it comes with relatively low capital intensity, a combination that could help margins and support a higher valuation if execution holds.
The broker also pointed to Atalaya’s cheap multiple versus mid-cap copper peers, estimating the shares trade at 4.5 times and 3.0 times 2026 and 2027 enterprise value to EBITDA on spot prices. For investors, that means the stock may be pricing in less of the upside from higher volumes and copper’s strategic importance than comparable miners.
Longer term, JPMorgan said Atalaya could benefit from further consolidation in the Iberian Pyrite Belt and from sulphide leaching initiatives, both of which could add optionality to growth without a heavy capital burden. The next focus for the market will be whether the company can deliver on Touro, advance Riotinto expansion and convert its EU supply-chain advantage into a sustained rerating.
| Entity | Gains | Losses |
|---|---|---|
| Atalaya Mining | ▲Higher valuation support | ▼Current discount to peers |
| JPMorgan | ▲New bullish call validated | ▼Risk of execution disappointment |
| Copper bulls / EU supply seekers | ▲More domestic supply exposure | ▼Dependence on imported material |
| Peer mid-cap copper miners | ▲Sector re-rating could lift all | ▼Atalaya may look cheaper and more attractive |