Australia’s banking sector is facing a fresh compliance reckoning after AUSTRAC said it has made hundreds of referrals amid a sweeping mortgage fraud probe, raising the odds of costly investigations, tighter lending standards and lower loan growth.
AUSTRAC mortgage fraud probe hits Australian banks
That matters because mortgage lending is still one of the most important engines of profit for banks, and fraud pressure can quickly turn into slower approvals, higher compliance spending and more conservative underwriting. For investors, the key question is not just who is exposed today, but whether this becomes a longer-lasting drag on mortgage banking margins and customer acquisition.
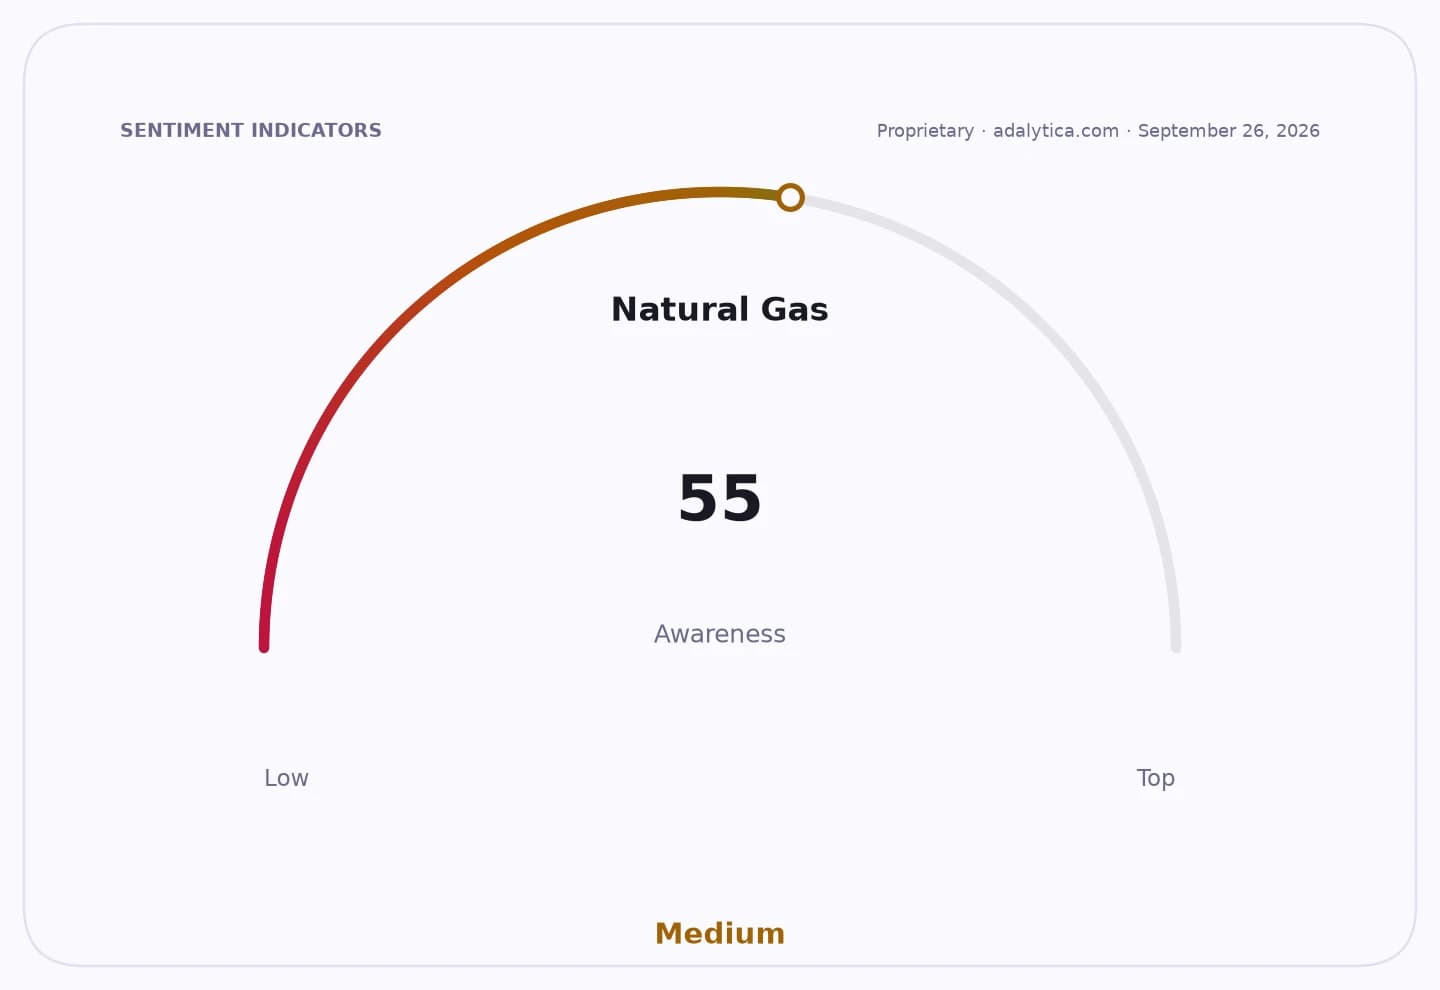
Sentiment IndicatorsⓘProprietary · adalytica.com · August 18, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The probe also lands at a sensitive time for financial stocks globally. U.S. bank shares, tracked by the Financial Select Sector SPDR Fund, have recently been steady, while large lenders such as Wells Fargo have recovered sharply from earlier weakness. But the broad message from Australia is the same one investors keep hearing elsewhere: banks can grow only as fast as they can police the system.
AUSTRAC, Australia’s financial-crime watchdog, has referred hundreds of matters as part of an escalating investigation into mortgage-related fraud. The scale suggests this is not a handful of isolated bad actors but a wider network that may have exploited weaknesses across loan origination, identity checks and downstream monitoring. The news follows a broader crackdown on bank fraud networks that has already led to arrests and exposed how criminals are using increasingly sophisticated tactics to target both institutions and consumers.
For banks, the direct economic hit comes from the cost of enforcement and remediation. But the bigger risk is second-order: when regulators step in, lenders often respond by slowing approvals, hardening documentation requirements and pulling back from higher-risk borrowers. That can crimp volumes in a business that depends on scale and efficiency. In Australia, where housing finance is central to the banking model, even modest changes in risk appetite can ripple through earnings.
Investors should also pay attention to the reputational side of the story. Mortgage fraud probes tend to damage trust in the lending process, which can be especially painful for banks competing for broker-sourced business or trying to expand in consumer finance. If the investigation uncovers governance failures rather than just criminal conduct, the costs can broaden into fines, compensation and management distraction.
The sector backdrop does offer some cushion. Bank shares have generally benefited from resilient earnings and, in the U.S., a still-favorable technical picture for some lenders has kept investors engaged. Wells Fargo, for example, has traded above both its 50-day and 200-day moving averages in recent sessions, while the broader bank ETF has also held above its longer-term trend. But fraud risk is not a market-timing issue; it is a compounding issue. Banks that can demonstrate strong controls are more likely to protect margins over years, not quarters.
For long-term investors, the takeaway is straightforward: mortgage fraud probes usually do not change the banking system overnight, but they do separate the lenders with durable underwriting discipline from those forced to spend more just to keep up. That makes the biggest winners the institutions that can defend trust and process at scale, while the losers are the banks that rely too heavily on growth without enough control. Worth watching, especially if the referrals lead to formal actions or broader industry-wide rules.
| Entity | Gains | Losses |
|---|---|---|
| Well-controlled banks | ▲Stronger trust | ▼None directly |
| Regulators/AUSTRAC | ▲More enforcement reach | ▼More workload |
| Mortgage borrowers | ▲Cleaner lending process | ▼Tighter credit access |
| Banks with weak controls | ▲None | ▼Fines, slower growth |