Households in Dhaka are still paying for gas they are not receiving, underscoring how Bangladesh’s energy shortfall has moved beyond a temporary supply hiccup into a broader economic drag that is stoking inflation and eroding trust in public utilities.
Bangladesh gas shortage keeps Dhaka bills high

The immediate issue is not a lack of demand but a failure to match supply with a population dependent on piped gas for cooking and daily life. The existence of 56.3 million cubic meters in reserve has not translated into lower consumer bills because the bottleneck lies in deliverability, infrastructure and the cost structure of the domestic gas system. In practical terms, inventories and reserves only ease pressure if they can be brought to market through functioning transmission and distribution networks, and if regulators are willing to let the benefit flow through to end users.
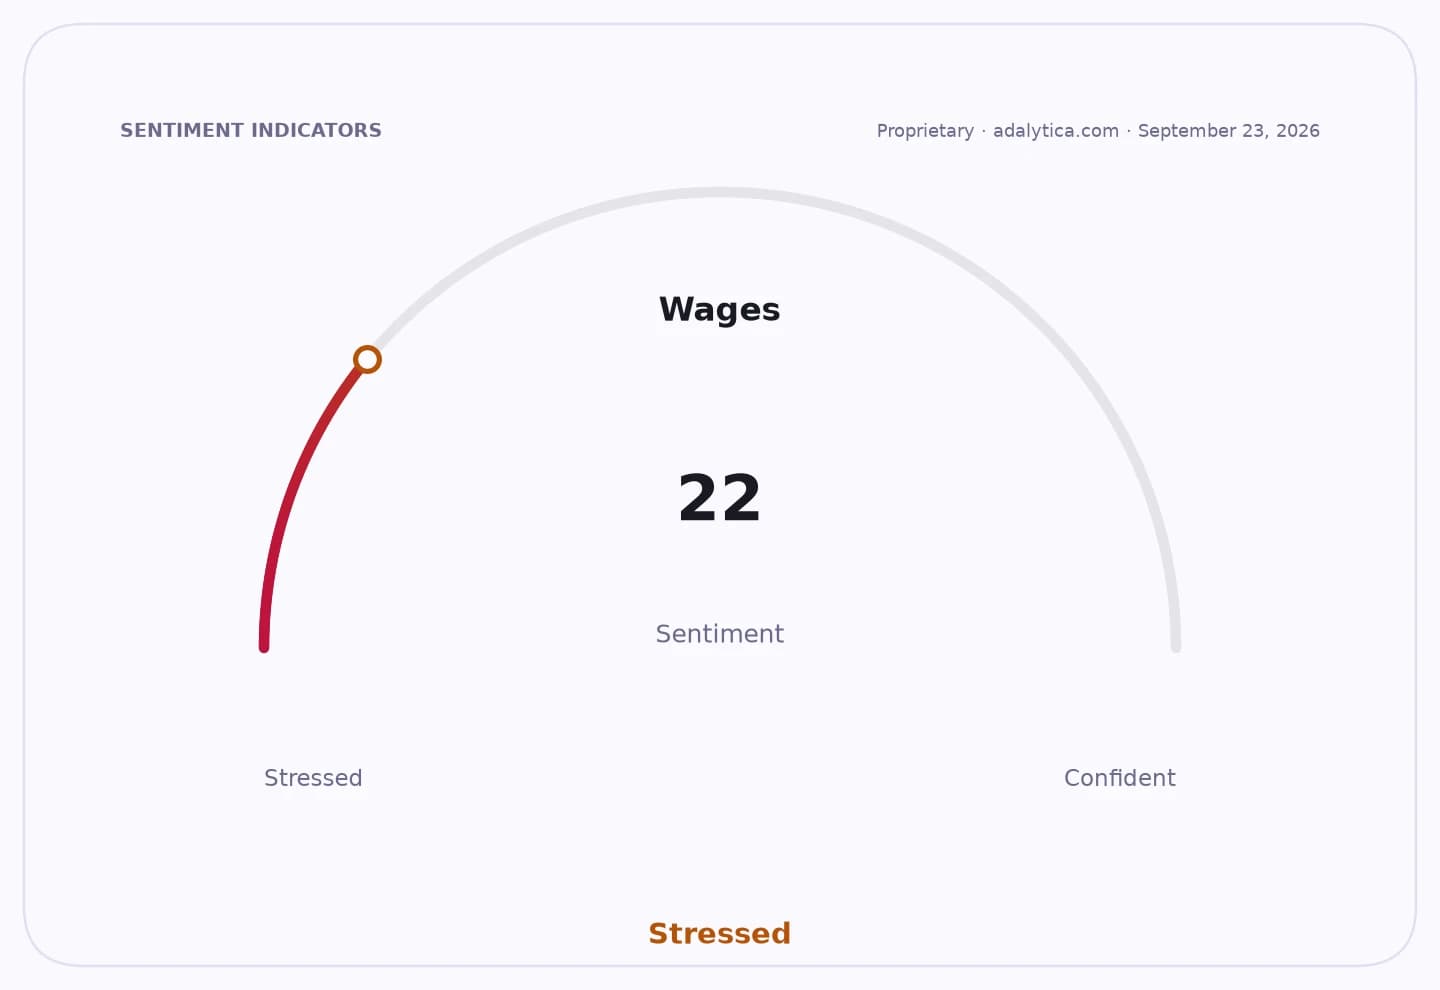
Sentiment IndicatorsⓘProprietary · adalytica.com · September 20, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That disconnect matters economically because energy is a core input to household budgets and business operating costs. When consumers continue to pay without getting service, disposable income is squeezed and inflationary pressure becomes more persistent. For a country already sensitive to imported fuel costs and foreign-exchange constraints, a malfunctioning gas market can amplify broader macro stress by keeping utility costs elevated even when supply conditions appear to improve on paper.
For investors, the story cuts across energy infrastructure, utilities and inflation-sensitive assets. Gas distributors and state-linked utilities face political pressure to explain why bills remain unchanged, while any company tied to LNG imports, transmission or distribution must contend with the risk of slower tariff pass-through, payment delays and public backlash. The market also has to weigh whether officials respond with price relief, subsidies or emergency supply measures, any of which would carry fiscal costs.
The broader narrative is one of an energy system under strain from constrained supply, weak infrastructure and rising public frustration. Officials have acknowledged efforts to ease the shortage, but the central challenge is structural: adding reserves does not automatically reduce bills if the system cannot reliably move gas to consumers. Until Bangladesh can improve delivery, diversify supply and reform pricing, the gap between what the state says is available and what households actually receive is likely to remain a source of economic and political pressure.
| Entity | Gains | Losses |
|---|---|---|
| Households in Dhaka | ▲No immediate gains | ▼Higher bills, poor service |
| Bangladesh utilities | ▲Preserved revenue flow | ▼Public anger, credibility hit |
| Energy importers/infrastructure firms | ▲Potential policy support | ▼Payment and tariff risk |
| Consumers and small businesses | ▲None | ▼Inflation pressure, tighter budgets |