Bank Handlowy is expected to report a 41% drop in third-quarter net profit, a sign that rising credit costs are starting to bite even as the broader banking sector remains near the top of investors’ watchlists for earnings and dividends.
Bank Handlowy Faces 41% Q3 Profit Drop
The decline matters because Polish lenders have benefited from a period of strong rates and healthy loan demand, but that cushion is becoming harder to rely on as provisions and impairment charges climb. For investors, the key question is whether the profit slump marks a one-off clean-up in the loan book or the start of a more persistent drag on returns on equity and payout capacity.
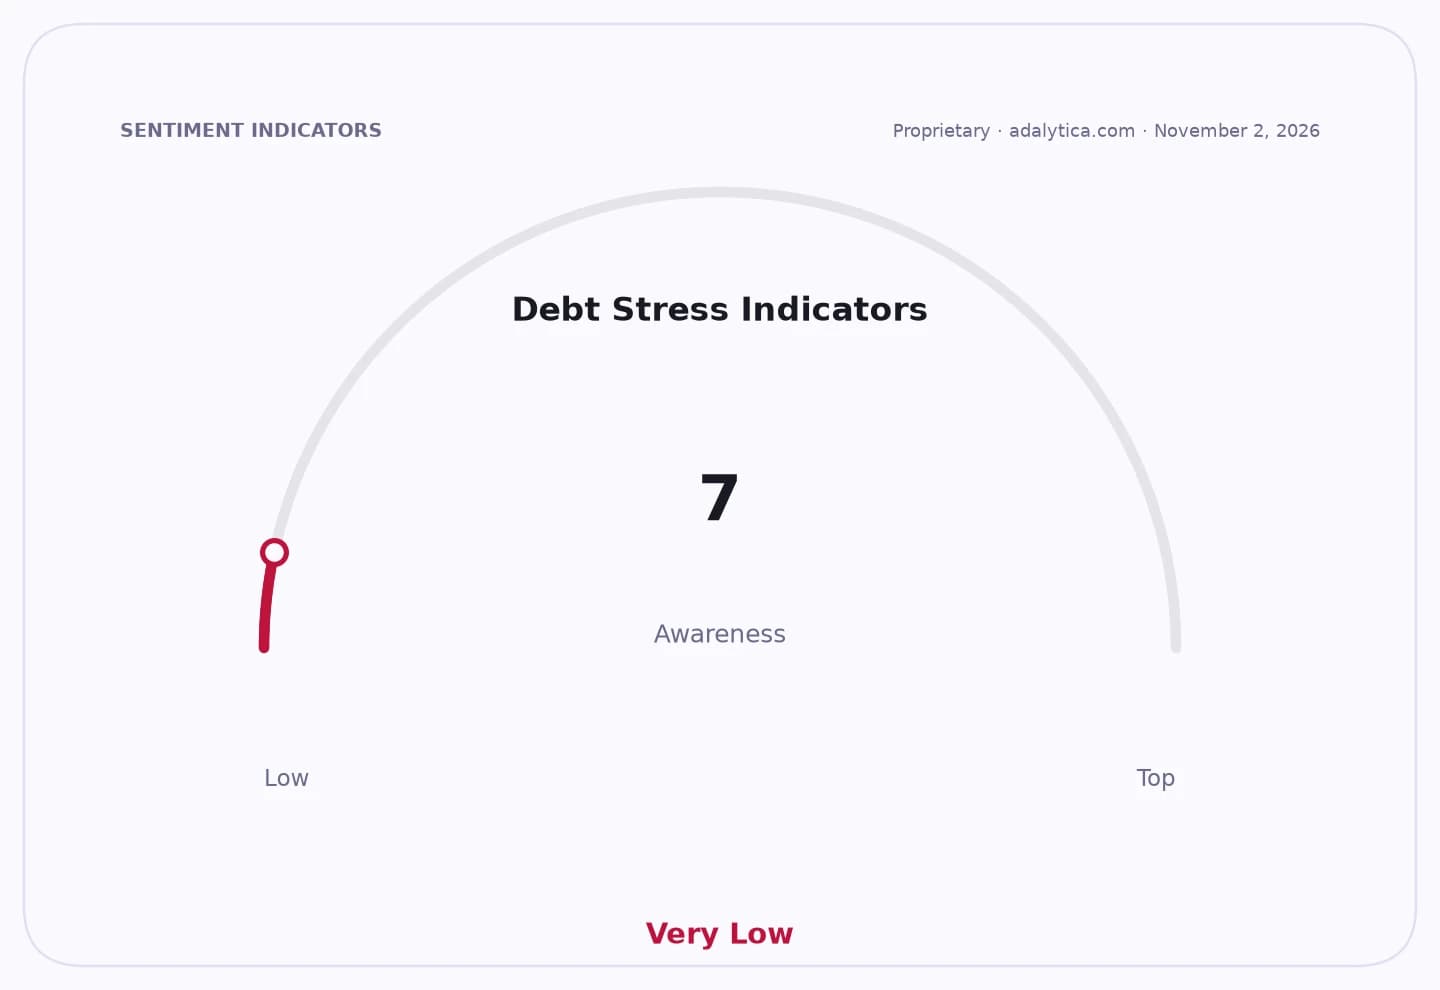
Sentiment Indicators
The wider backdrop is mixed. Banking shares have generally held up better than the broader market, with investors still drawn to balance-sheet strength, capital generation and dividend potential. But recent earnings from peers have underscored how quickly credit costs can erode profits: National Australia Bank posted a 13.4% fall in full-year cash profit, blaming nearly doubled impairment charges, while large global lenders including JPMorgan and Citigroup have continued to emphasize the sensitivity of results to loan losses and funding dynamics.
For Bank Handlowy, a sharp year-on-year profit decline would likely reflect a combination of higher risk costs and a tougher comparison base rather than any collapse in core lending activity. That distinction matters. If the hit is driven mainly by provisioning, the market may look through it as a temporary reset. If margin pressure is also building, the earnings downgrade would carry more weight for valuation, especially in a sector where investors have been paying up for resilience and capital returns.
The stock has already shown that the market is willing to punish banks when earnings momentum weakens. Bank Handlowy’s shares have been volatile this year, and technical indicators point to some cooling after a strong run, with the 50-day moving average still below recent prices but momentum flattening. That leaves the bank exposed if the results disappoint.
Investors will focus on whether management keeps guidance intact on net interest income, credit quality and capital distribution. A profit drop of this size would not by itself rewrite the investment case, but it would test the durability of the earnings recovery and the pace at which Polish banks can keep rewarding shareholders while absorbing higher credit costs.
| Entity | Gains | Losses |
|---|---|---|
| Bank Handlowy | ▲strong earnings base | ▼41% profit drop |
| Bank shareholders | ▲possible dividend visibility | ▼near-term earnings pressure |
| Borrowers | ▲potential easing focus | ▼tighter credit standards |
| Peer lenders | ▲sector comparison support if results hold | ▼risk of broader sentiment drag |