Bitcoin is back to behaving more like a macro hedge than a high-beta tech proxy, but investors are also confronting a familiar warning that the rally may be moving into the part of the cycle where drawdowns deepen.
Bitcoin Hits Four-Month High as Macro Hedge
The world’s largest cryptocurrency hit a four-month high of $82,262 this week before easing back to about $79,700 on Friday, extending a rebound that has taken it out of a $60,000-$70,000 range that held since early June. The move has mattered because it suggests Bitcoin is once again being used by some investors as a store of value in a period of rising bond-market stress and renewed concern over currency debasement, rather than simply as a speculative risk asset.
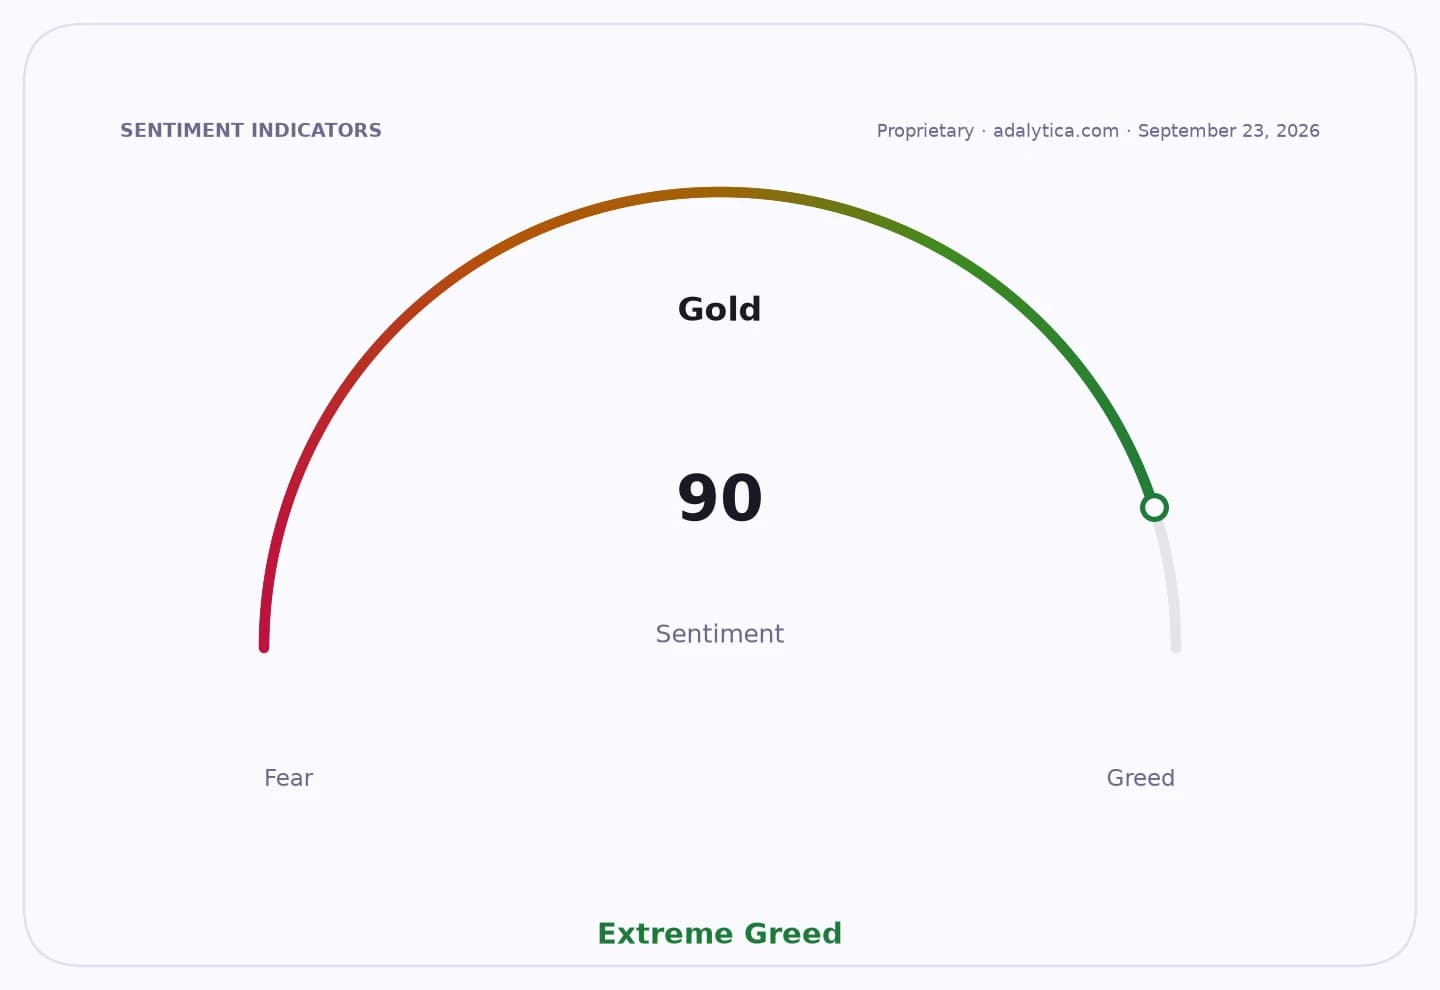
Sentiment IndicatorsⓘProprietary · adalytica.com · September 5, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That shift has coincided with a surge in Treasury yields and growing unease over the US fiscal outlook. Treasury Secretary Scott Bessent’s proposal to increase buybacks of long-dated bonds has stirred talk of “financial repression,” while the 30-year yield has climbed to its highest level in nearly two decades. Against that backdrop, Bitcoin’s 90-day correlation with gold has neared a six-year high, according to Bitwise’s André Dragosch, reinforcing the idea that the cryptocurrency is trading more like an “amplified version of gold” when macro anxieties dominate.
For investors, the distinction is important. If Bitcoin is increasingly tethered to gold’s haven-like role, it could benefit from the same forces that support bullion: debt concerns, geopolitical risk and expectations that central banks will ultimately have to accommodate higher funding costs. But it also means Bitcoin may be vulnerable to the same shifts in macro sentiment that drove gold’s own volatility around recent US jobs data. Adalytica’s Bitcoin Fear & Greed Index remains in neutral territory at 46, while awareness is still flagged as fear, suggesting the market is not yet in a broad speculative excess phase even after the latest rally.
The bear case is that Bitcoin’s recent strength may be less durable than the price action suggests. Traders watching the four-year cycle theory argue that Bitcoin’s market structure often peaks and troughs in roughly four-year increments tied to its halving schedule. Fidelity’s fourth-quarter crypto outlook noted that, if the pattern holds, the next bear-market low could come as soon as November, four years after the last bottom in November 2022. Galaxy’s Alex Thorn has gone further, saying historical analogies point to a base-case drawdown bottom in the $40,000-$46,000 range sometime between now and the fourth quarter of 2026, though not as a formal forecast.
The cycle thesis is not universally accepted. Fidelity’s Chris Kuiper said the timing is imprecise and does not necessarily imply a slide later this year, arguing that a long holding period has historically been the most rewarding approach for Bitcoin investors. That view reflects a broader bull case: if the market continues to treat Bitcoin as scarce digital collateral in an environment of persistent fiscal stress and elevated real rates, the asset could keep drawing inflows from investors seeking an alternative to fiat exposure.
Still, the current setup leaves Bitcoin at an important inflection point. It has regained the character of a macro hedge at the same time that cycle-focused investors are warning the market may be entering a vulnerable period. For now, the asset is being pulled between two narratives: one that sees it as digital gold with room to extend higher, and another that says the calendar, not the macro backdrop, could soon start to matter more.
| Entity | Gains | Losses |
|---|---|---|
| Bitcoin bulls | ▲Haven demand | ▼Cycle-risk downside |
| Gold | ▲Safe-haven flows | ▼None |
| Short-term momentum traders | ▲Breakout trade | ▼Reversal risk |
| Four-year cycle skeptics | ▲Macro-driven thesis | ▼Timing uncertainty |