Following Bitcoin “whales” in the options market did not beat a random strategy over five years, underscoring that large trades in crypto derivatives are more likely to hedge risk or express complex structures than to provide a clean directional signal.
Bitcoin options whales fail to beat random trading
That matters because Bitcoin’s options market has become a bigger part of price discovery as BlackRock-era institutional money, exchange-traded funds and broader Wall Street participation pull more capital into the asset. If the biggest trades do not reliably predict the next move, investors chasing flow alone may be paying up for noise rather than alpha.
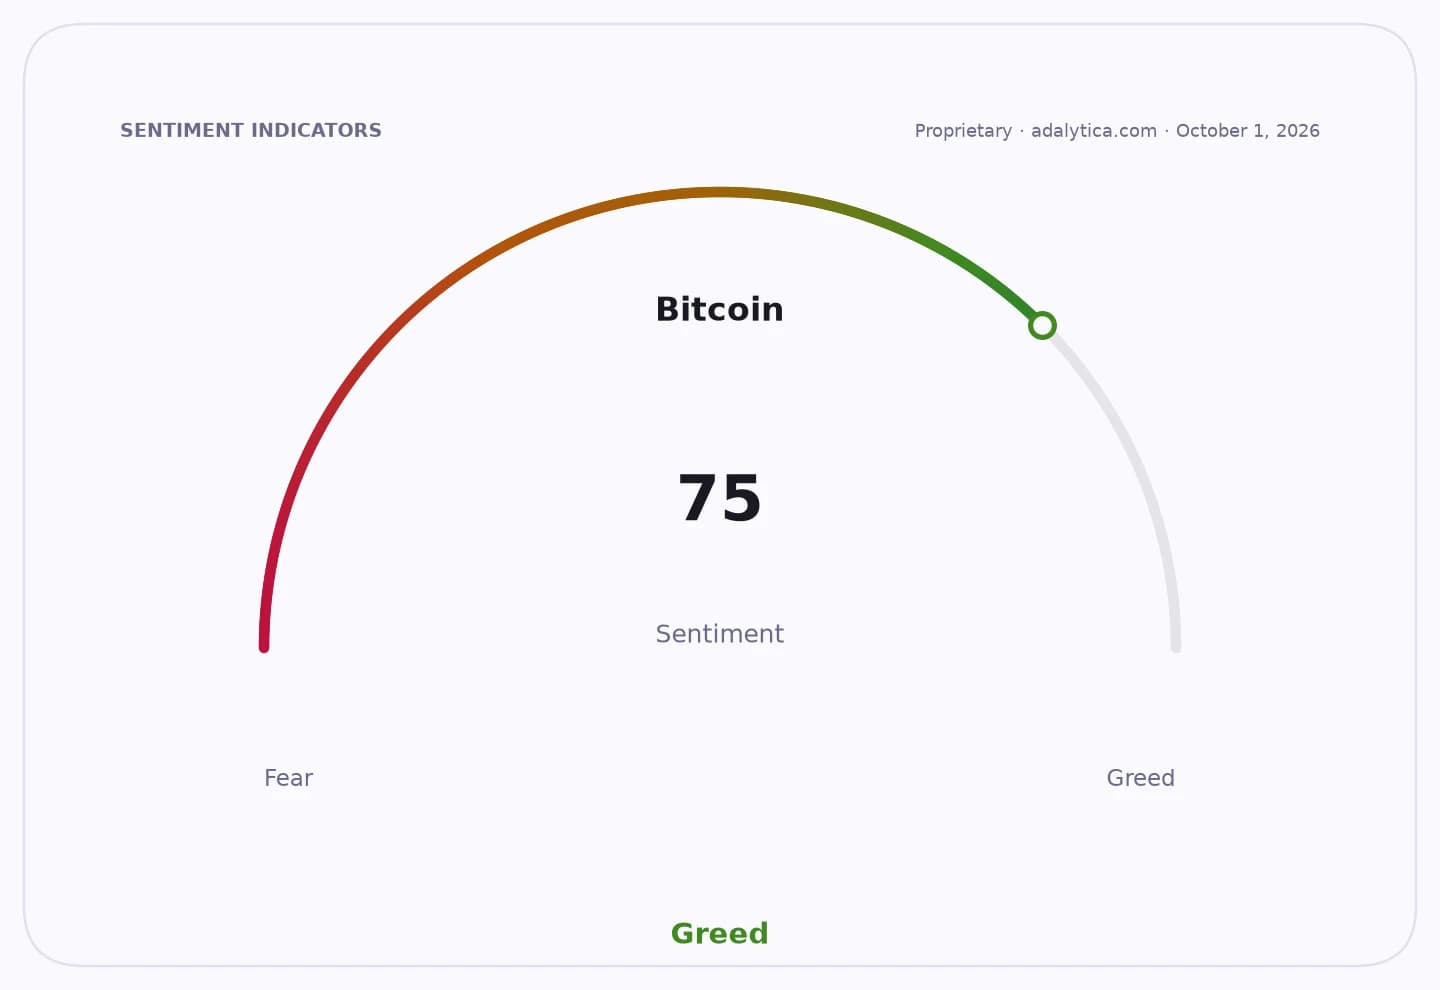
Sentiment IndicatorsⓘProprietary · adalytica.com · October 2, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The finding fits a market that has remained highly volatile despite deeper institutional adoption. Bitcoin was last around $84,606.98, after surging from $62,702.10 in early February and rebounding from a recent low near $76,974.45, while the 50-day moving average sits at $77,696.08 and the 200-day at $71,321.83, a sign of a still-intact longer-term uptrend.
But the short-term technical picture looks stretched. Bitcoin’s relative strength index was 76.3 in the latest reading, which conventional technical analysts would view as overbought, even as the price trades above both moving averages and near the upper end of its recent Bollinger Band range.
That tension helps explain why copying large options traders can disappoint. In crypto, as in other markets, block trades often reflect hedges, spreads and volatility bets rather than simple calls on direction. A trader buying protection or structuring a position around calendar risk can look bullish or bearish on the tape without actually holding a directional edge.
The broader message for investors is that bitcoin is maturing as an institutional asset, but its derivatives market still rewards caution. Adalytica’s Bitcoin Fear & Greed snapshot shows sentiment at 79, in “Greed,” after a 77-point jump over 30 days, a backdrop that can lure momentum buyers even as the crowd grows crowded.
If the pattern holds, the next test for bitcoin will be whether ETF flows and macro risk appetite can keep supporting the rally without help from any supposed “whale” signal. For investors, the takeaway is to treat big options prints as context, not a shortcut.
| Entity | Gains | Losses |
|---|---|---|
| Long-term Bitcoin holders | ▲Benefits from institutional adoption | ▼Faces volatility |
| Options “whales” | ▲Can hedge or structure trades | ▼Do not provide easy directional edge |
| ETF inflows | ▲Support liquidity and demand | ▼Lose if sentiment cools |
| Short-term signal chasers | ▲None | ▼Risk false momentum trades |