Brazil’s economists are now expecting inflation to stay hotter next year even as growth cools, a combination that keeps the central bank boxed into a restrictive policy stance and raises the cost of capital for the real economy.
Brazil inflation expectations rise as growth cools
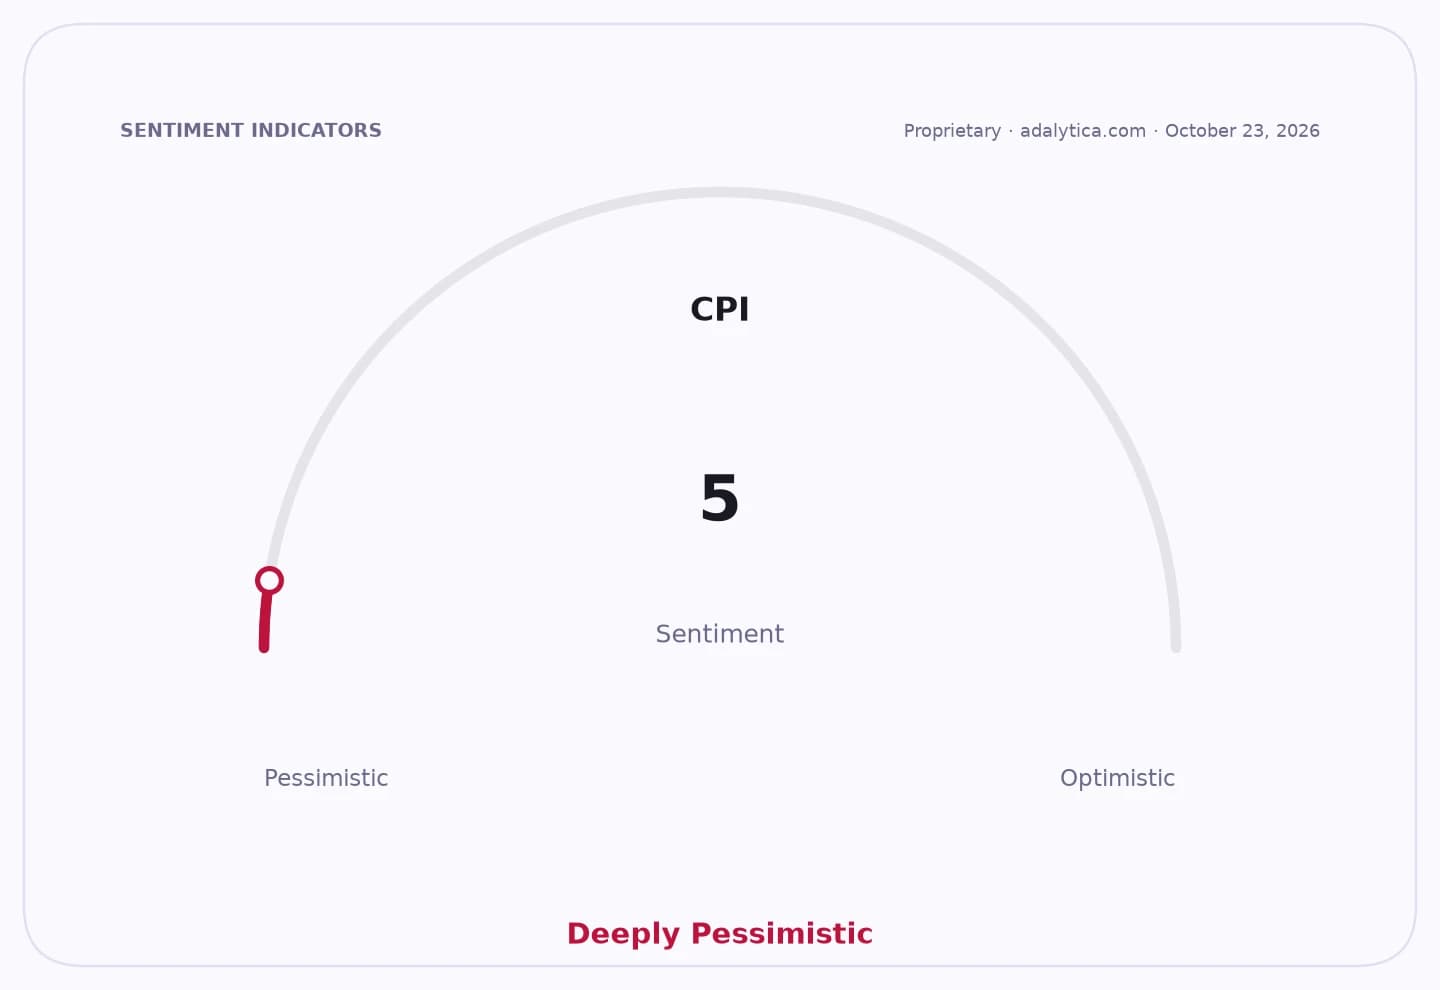
The latest Focus survey shows the market consensus for 2026 inflation edging up to 4.32% from 4.30%, while the 2026 GDP view was trimmed and growth expectations were cut further out to 2027 and 2028. That matters because Brazil is already running well above its 3% inflation target, with this year’s forecast still at 5.22%, far beyond the tolerance band. In other words, the economy is being asked to slow down before price pressures are fully contained.
For investors, the message is straightforward: Brazil’s easing cycle is likely to remain shallow and data-dependent, not the aggressive rate-cut story the market would prefer. The survey left the policy rate outlook unchanged at 13.25%, implying two quarter-point cuts in November and December from the current Selic rate of 13.75%. Even so, inflation expectations stubbornly above target mean any policy relief will likely be limited, which supports elevated real yields and keeps pressure on duration-sensitive assets.
That setup has clear market consequences. Higher-for-longer rates tend to favor banks with strong deposit franchises and punish leveraged domestic sectors that depend on cheaper credit, from construction to rate-sensitive consumer names. It also complicates valuation for Brazilian equities more broadly, because softer growth and sticky inflation are a poor mix for earnings multiples. The real may find some support from the central bank’s caution, but that comes at the cost of slower credit creation and weaker cyclical momentum.
The deeper narrative is that Brazil is confronting a familiar emerging-market bind: inflation remains too stubborn to allow meaningful monetary easing, yet growth is losing steam. Until inflation expectations start moving decisively back toward target, the central bank will prioritize credibility over stimulus. For investors, that means positioning for a market where rates stay elevated, GDP disappoints, and the best opportunities are likely to be in exporters, balance-sheet strength and companies that can pass through pricing without losing demand.
| Entity | Gains | Losses |
|---|---|---|
| Brazilian banks | ▲Higher net interest income | ▼Slower loan growth |
| Exporters | ▲Weak real support | ▼Sluggish domestic demand |
| Consumer cyclicals | ▲— | ▼Higher borrowing costs |
| Bondholders | ▲High carry on real yields | ▼Inflation erodes returns |