Canada’s biggest lenders are moving together to develop Canadian dollar-based digital money, a step that could modernize domestic payments without forcing customers out of the regulated banking system.
Canadian Banks Explore Tokenized Deposits
Bank of Montreal, CIBC, National Bank, Royal Bank of Canada, Scotiabank and TD Bank are jointly exploring tokenized deposits, a structure that would record conventional bank deposits on a distributed ledger and let them move between institutions more quickly and programmatically. The first phase is aimed at interbank transfers, a sign the banks want to solve the plumbing first before pushing the product to households or businesses.
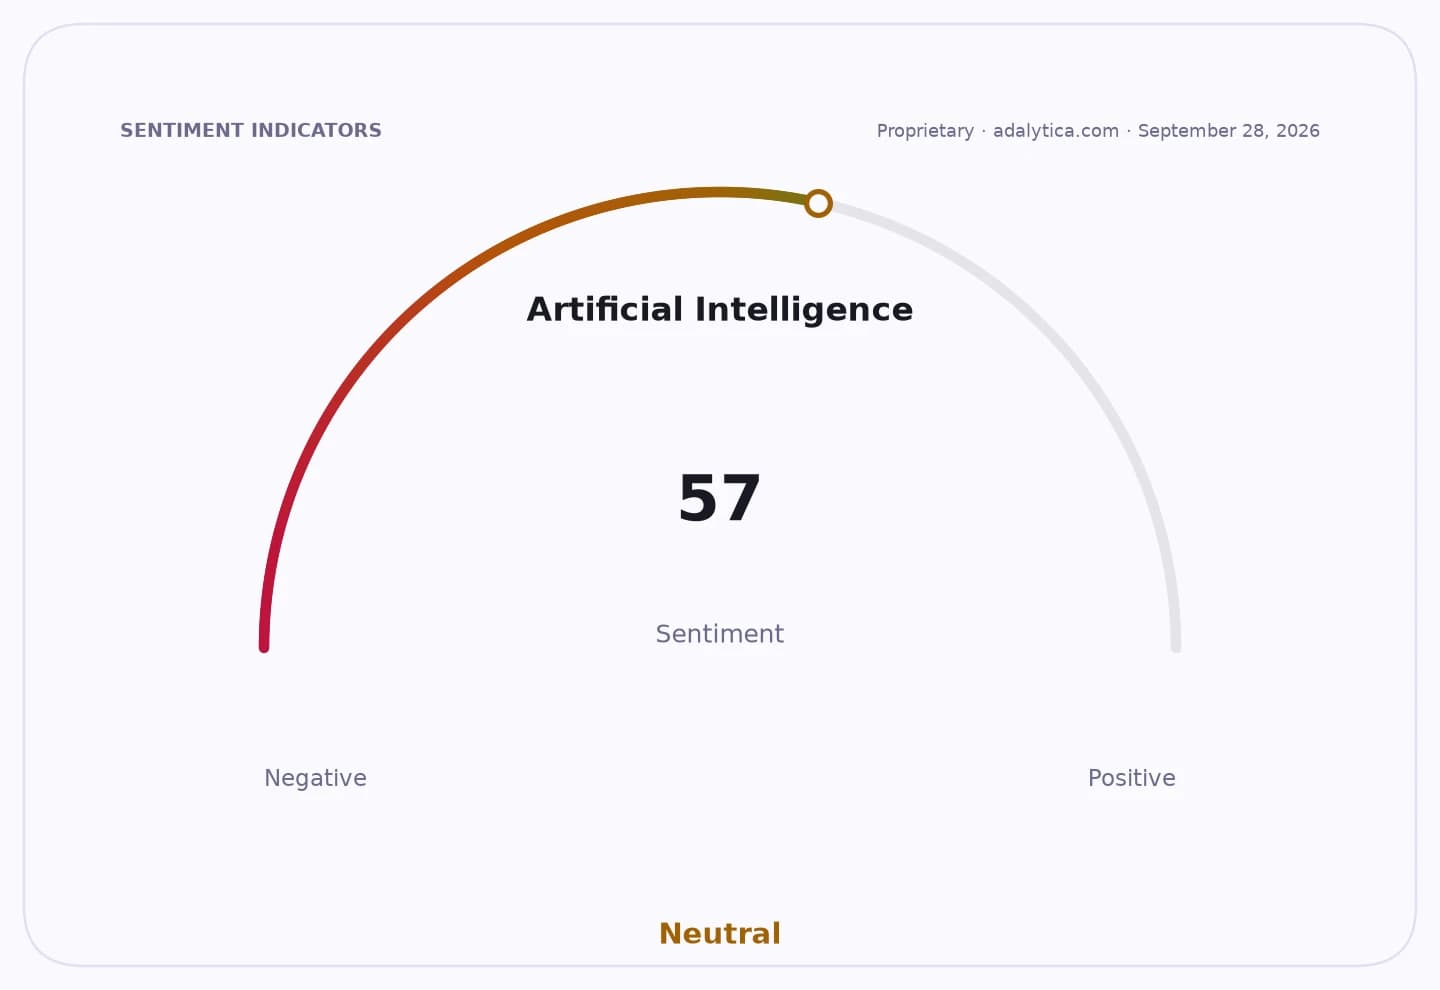
Sentiment IndicatorsⓘProprietary · adalytica.com · September 26, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The economic significance is less about creating a new currency than about improving the speed and efficiency of money already inside the system. Tokenized deposits can settle payments faster, cut back-office friction and support programmable transactions, all while keeping the deposits on bank balance sheets and under existing regulatory oversight. That makes the initiative materially different from private stablecoins or central bank digital currency proposals, because it preserves the funding base that supports lending and liquidity in the Canadian banking system.
For investors, the project is a double-edged development. On the bullish side, it gives Canada’s major banks an opportunity to defend their deposit franchises, reduce transaction costs and potentially open new fee-generating payment services. It may also help the lenders keep pace with global peers experimenting with blockchain-based settlement as digital payments become more competitive. On the bearish side, tokenization could compress margins over time if faster, cheaper payments reduce the economics of traditional transfer and cash-management services, while the costs of building shared infrastructure may take time to monetize.
The move comes as large banks worldwide search for ways to keep deposits relevant in a payments market increasingly shaped by real-time rails, digital wallets and tokenized assets. Canada’s approach is notable because the country’s biggest banks are coordinating rather than racing each other, which could speed adoption if regulators are comfortable with the model. It also fits a broader trend in which commercial banks are trying to retain control over settlement infrastructure rather than ceding it to fintech platforms or non-bank issuers.
RBC, TD and the rest of the group are coming into the project from a position of strength in their core franchises, with shares of the major lenders still trading above long-term trend levels despite recent volatility. Royal Bank’s stock, for example, remains above its 200-day moving average even after pulling back from earlier highs this month, while TD and Scotiabank have also held above their longer-term averages. That suggests investors continue to view the banks as stable financial infrastructure names, making any credible digital-payments initiative more about strategic optionality than a near-term earnings catalyst.
The key question is whether the banks can move from a proof of concept to a common market standard. If they do, tokenized deposits could become one of the clearest examples of how traditional banking is adapting to digital money without abandoning the deposit-based model that underpins credit creation. If they do not, the initiative risks becoming another pilot in a sector that has often talked faster than it has shipped.
| Entity | Gains | Losses |
|---|---|---|
| Big Canadian banks | ▲Faster payments, lower settlement costs | ▼Upfront build costs |
| Corporate and retail clients | ▲Quicker transfers, programmable cash flows | ▼Less benefit from legacy rails |
| Fintech rivals | ▲New integration opportunities | ▼Moat pressure on payments |
| Traditional payment networks | ▲Broader digital adoption | ▼Volume and fee pressure |