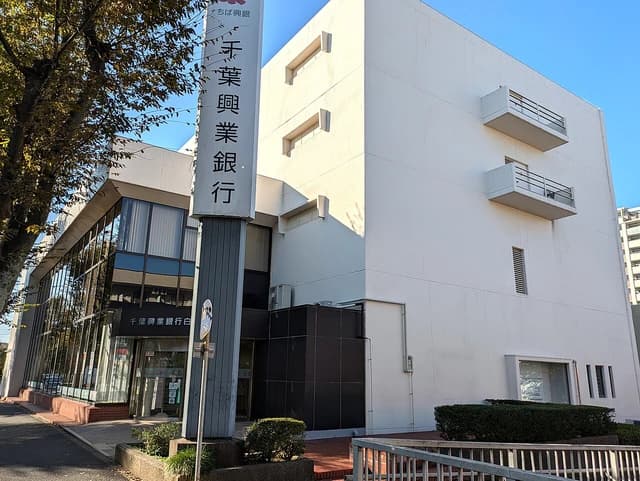
Chiba Kogyo Bank is moving aggressively to pull in deposits through online branches, a sign that Japan’s regional lenders are being forced to compete harder for funding as interest rates rise and the cost of cash becomes more important.
Chiba Kogyo Bank Uses Online Branches for Deposits
That matters because deposit gathering is now a front-line issue for banks, not a back-office one. In a higher-rate environment, the lender that secures stable, low-cost funding has more room to protect margins, extend loans and avoid being squeezed by rising mobilization costs. The banks that fail to attract sticky deposits risk paying up for money, even if official policy rates remain relatively low.
The broader backdrop is a tightening battle for household and corporate cash across Japan’s banking system. The seed headline points to Chiba Kogyo Bank, the highest-rate lender in Kanto, leaning on online branches to widen its reach beyond traditional local banking relationships. That is a rational move in a market where depositors have become rate-sensitive and where digital channels can lower acquisition costs while expanding access beyond a branch network.
For investors, the message is bigger than one regional bank. Japan’s higher-rate cycle is creating winners and losers inside the financial sector. Banks with strong deposit franchises, efficient digital distribution and disciplined funding costs should keep outperforming. Those dependent on expensive wholesale money or slow-moving branch networks may see margins erode as competition intensifies.
The macro backdrop reinforces that view. In Japan, even modest rate normalization can have an outsized effect on bank behavior, because lenders that spent years operating in near-zero-rate conditions now have to compete for deposits more aggressively. That shifts the investment case away from balance-sheet inertia and toward operating leverage, funding discipline and customer acquisition.
If Chiba Kogyo Bank’s online push works, it could become a template for other regional lenders looking to defend net interest income without relying solely on old-school branches. The market should treat this as an early signal that Japan’s banking competition is entering a more digital, more yield-sensitive phase. For investors, the best opportunities are likely to be in banks that can attract deposits cheaply while others are still paying up.
| Entity | Gains | Losses |
|---|---|---|
| Chiba Kogyo Bank | ▲More deposits, lower funding risk | ▼Higher sales and digital rollout costs |
| Regional Japanese banks with strong digital reach | ▲Sticky funding, wider lending capacity | ▼Smaller banks with weak franchises |
| Savers and depositors | ▲Better deposit rates | ▼Borrowers facing higher loan costs |
| Banks reliant on expensive funding | ▲— | ▼Margin pressure, deposit outflows |