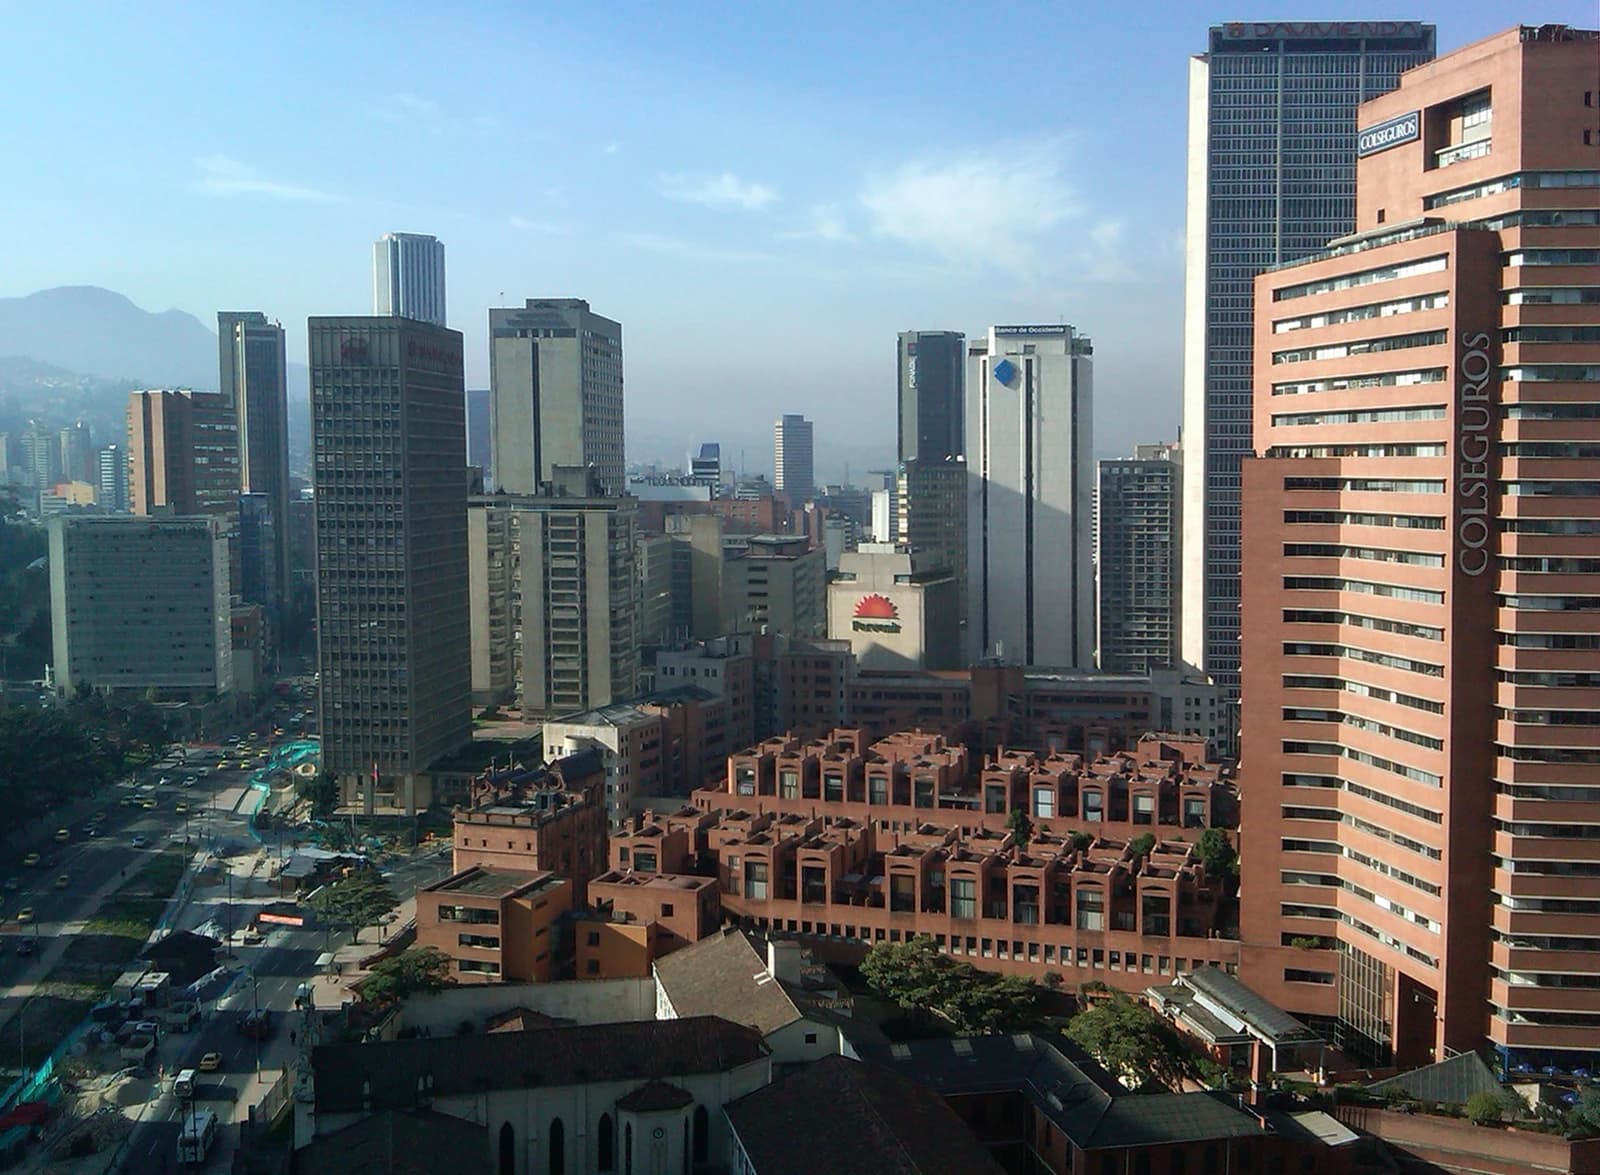
Colombia’s public debt office exchanged $11.15 billion of TES on Thursday in a move designed to push maturities further out and relieve near-term pressure on the government’s strained financing calendar.
Colombia debt office swaps $11.15 billion in TES
The swap is economically significant because it gives the state more breathing room at a time when liquidity is tight and the debt profile is heavily concentrated in the next few years. By replacing securities due soon with longer-dated paper, the government reduces the amount it must refinance in the short term and smooths repayment peaks that could otherwise force it to borrow at punitive rates.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 3, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The exchange was the first of three planned this year, with follow-up operations set for Oct. 29 and Nov. 26. Officials are trying to manage a 2027 maturity wall of about 78 trillion pesos, making the rollover program a key part of fiscal stabilization rather than a routine market transaction.
Of the total swapped, 8.6 trillion pesos came from longer-term TES in pesos and inflation-linked UVR paper, with the government taking back bonds maturing in March 2027 and replacing them with securities due between 2029 and 2062. Another 2.5 trillion pesos came from short-term TCO notes maturing in October, November and January 2027, which were exchanged for paper due between July and September 2027.
The coupons and yields underline why the Treasury is moving now. The securities it took in were yielding between 12.5% and 13.5% in nominal terms, while UVR-linked paper carried rates of 5.9% to 7%, showing the cost of rolling debt in a high-rate environment.
For investors, the deal is a credit-quality signal as much as a liability-management exercise. Colombia is trying to avoid a sharper funding squeeze, and the success of the next two swaps will help determine whether the sovereign can keep its maturity profile under control without pressuring domestic bond markets further.
Bond traders will also watch whether the operation supports demand for longer-dated Colombian paper and eases stress in the short end of the curve. The next test comes with the October and November exchanges, which will show whether investors are willing to keep extending duration to the government on the terms it needs.
| Entity | Gains | Losses |
|---|---|---|
| Colombian government | ▲Lower near-term repayment pressure | ▼Higher future-duration exposure |
| TES investors | ▲Longer-dated sovereign paper | ▼Near-term liquidity in shorter bonds |
| Short-term bondholders | ▲Reduced immediate refinancing risk if exchanged | ▼Give up shorter maturities |
| Credit markets | ▲Smoother maturity profile | ▼Visibility on funding stress remains a risk |