The European Central Bank leaves borrowing costs unchanged at 2.5% on Thursday, keeping the focus on when policymakers may resume tightening after the Federal Reserve has already signaled a pause and U.S. markets are digesting a sharp split in Big Tech earnings reactions.
ECB Holds Rates at 2.5% as December Hike Looms
That matters because the ECB’s decision lands at a moment when investors are trying to price a longer-for-higher-rate backdrop without choking off growth. A December rate increase remains on the table, according to Bundesbank President Joachim Nagel, which would keep pressure on euro-zone borrowing costs even as inflation data still show prices elevated and energy risks linger.
Sentiment Indicators
For markets, the immediate effect is to keep the euro-zone policy outlook tighter than many had expected after the Fed’s hold. The DAX has already pushed above 26,000 points on the prospect of an ECB that stays restrictive, a backdrop that tends to support the euro and financial stocks while weighing on rate-sensitive sectors such as property and consumer discretionary names.
The policy wait-and-see comes as investors also parse a heavy earnings slate. Microsoft jumped after its latest numbers, helped by expectations that its AI and cloud spending can keep revenue growth strong, while Alphabet tumbled, underscoring how unforgiving the market is becoming toward heavyweight tech names that fail to clear a high bar on advertising, cloud or AI monetization.
That divergence is showing up in the tape. Microsoft’s shares have rebounded to 530.61 after closing near 556 earlier in the week, with conventional technical indicators still showing it above both its 50-day and 200-day moving averages. Alphabet, by contrast, is under pressure around 284.78, well below its 50-day average and with its relative strength index near 20, a level that points to deeply oversold conditions after the selloff.
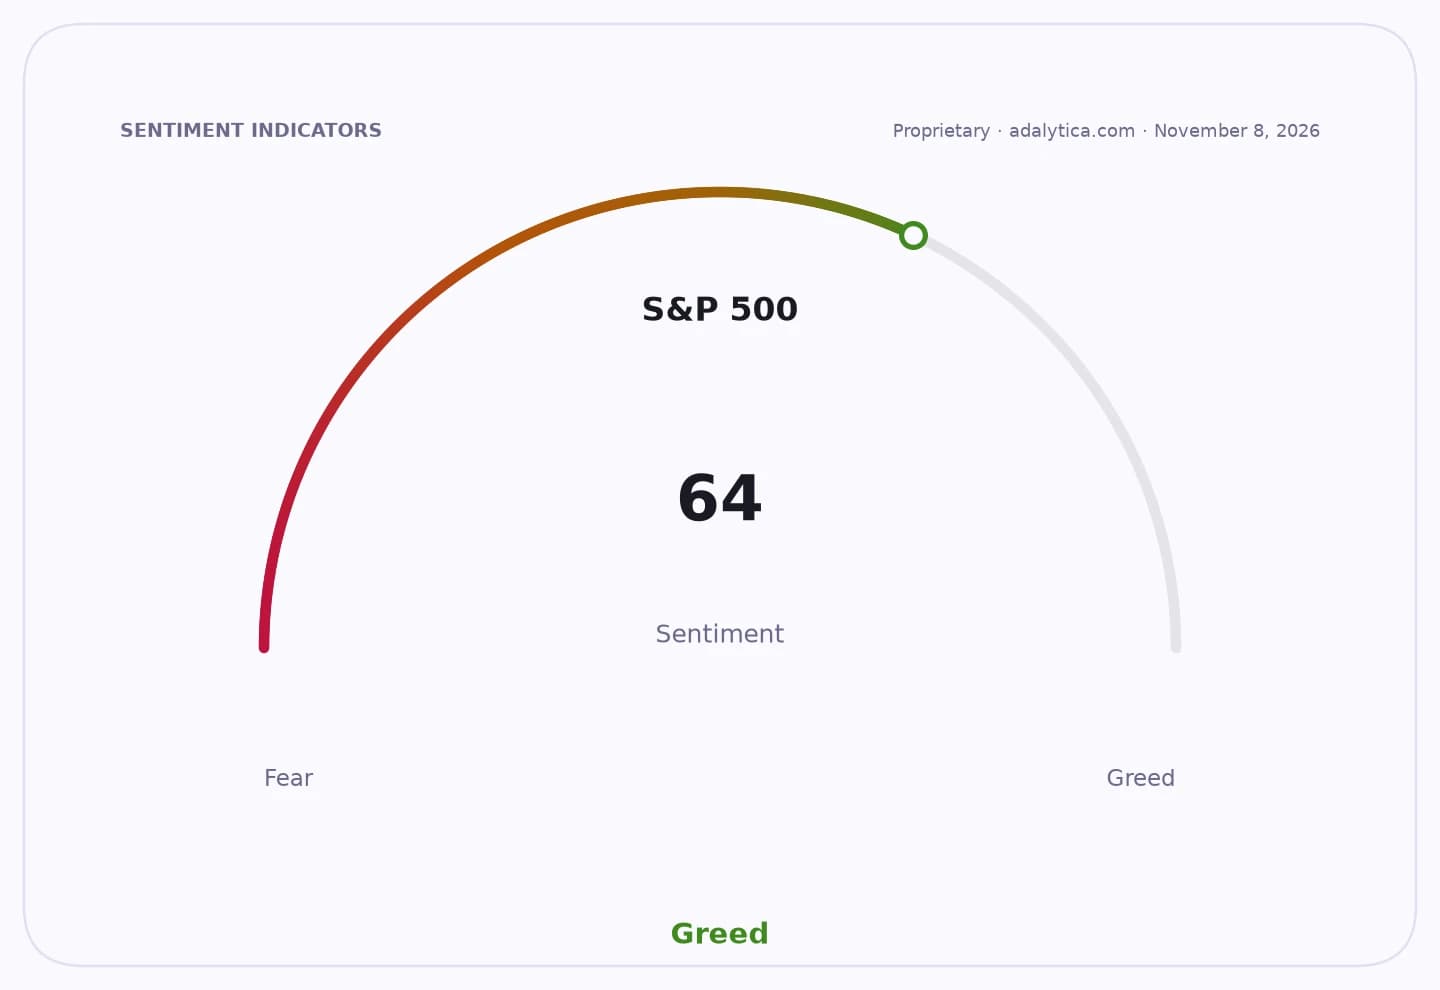
Broader market sentiment remains mixed but still elevated around large-cap equities, with Adalytica’s S&P 500 trade signals showing “Extreme Greed” in awareness even as sentiment sits at neutral. That suggests investors are still willing to chase earnings winners, but only selectively, and it raises the stakes for every major macro print and central-bank comment into the end of the year.
The next catalyst is the ECB’s press conference and any fresh guidance on December, followed by the next round of inflation data and more Big Tech results, which will determine whether the current split between rate winners and losers widens further.
| Entity | Gains | Losses |
|---|---|---|
| ECB hawks | ▲Tighter policy credibility | ▼Softer growth hopes |
| Euro-zone banks | ▲Wider rate margins | ▼Borrowers and rate-sensitive sectors |
| Microsoft shareholders | ▲AI/cloud optimism | ▼None directly |
| Alphabet shareholders | ▲Oversold rebound potential | ▼Earnings disappointment risk |